I cleared out my elderly neighbor’s townhouse to sell it. Here’s how I dealt with mountains of stuff


When my elderly neighbor, who I’ll refer to as Susan, moved to assisted living following a bad fall, her niece reached out to discuss the sale of Susan’s Carroll Gardens townhouse; a home that had been in their family for nearly a century. 

As the owner’s friend and neighbor, and a real estate agent at CORE, I was happy to help. I agreed to swing by the house to meet with the niece and her husband, trustees of the estate, while they assessed the condition of a home they had not been invited inside for years.

The couple, we’ll call them Terri and Jim, expressed different priorities. He wanted to sell the property “as is” without removing any of the copious personal contents from Susan’s long life.

“It’s a gutter,” he said. “Let the buyer deal with the junk.” 

Terri said she wanted “to do right by” her aunt, and was looking for advice. She needed to sell, but how to get from here to there was overwhelming to her. “Please, take anything you can use! There’s so much good stuff.” She held up a shirt to show me. “You’d look cute in this!’ she said.


[Editor’s Note: Brick Underground’s Inside Stories feature first-person accounts of interesting, real-life New York City real estate experiences. Have a story to share? Drop us an email. We respect all requests for anonymity.]


Nudging aside piles of clothes, linens and pillows, I found a small patch of bedspread where I parked myself as I met with them. There were dusty photos, scattered broaches, and an old rabbit-eared tv within my immediate sight. The rest of the three-story, two-family townhouse was equally cluttered with possessions from generations that lived there over the years.

The sale would pay for Susan’s assisted living, and the trustees were anxious to dispose of the property as quickly as possible. As retired snowbirds managing two homes in two states, the responsibility of executing this additional transaction was daunting.

Caption

Among the vintage finds given away were, from left to right, a U.S. army uniform, Susan’s signature floral housecoats, and her 1950s wedding dress.

Earning their trust

Susan, who recently turned 90, had been my neighbor for a dozen years. I’ve known her since before I was married and became a mom. My daughter and I would visit with her as she swept her stoop, or painted her fence, wearing one of her signature floral housecoats—she had about 30 of them.

We endured the covid pandemic together and had watched our Carroll Gardens neighborhood transform: Whole Foods arrived, landmark businesses shuttered, and a waterfront promenade rose on the banks of the Gowanus. I wanted to do right by her too.

I had relevant experience: I had dissolved two estates for my own aging family members and brokered an estate purchase on the Upper West Side. I presented Terri and Jim with an offer. 

“If you sell this home without emptying, staging and photographing it properly, you will leave tens of thousands of dollars on the table at sale,” I explained. “I’ll make it easy for you to say yes. Take what you want and leave the rest to me.” 

They agreed.

Caption

A view of the dining table mid-clean out.

Clearing the cache

From my work as an agent, I know that major life transitions don’t always line up with market trends. It’s a tough market for unrenovated properties, and yet demand for services involved in preparing an estate sale in NYC are on the rise.

According to Attom Data, transactions involving trusts jumped 17 percent in three years accounting for approximately 28 percent of Manhattan sales in 2024. Property Shark reported that 38 percent of all NYC real estate is owned by seniors, 65 years and older. And NAR noted that failing to declutter a property for sale costs sellers an average of three times the days-on-market and up to 10 percent of the sale price.

Entire industries have cropped up around estate-turnovers: junk removers, salvage and consignment shops, and non-profit organizations have moved mountains of once-loved furniture, clothing, technology and household items from NYC estates into the local community, and unfortunately, into landfills. 

A two-week deadline

I gave myself two weeks to clear the house, scheduling repairs, cleaning, photography, and listing activation to keep me on task. Once every drawer had been opened, cabinet scoured, and closet overturned, I bid out the job of “junking” it all to three local businesses who came back with comparable quotes—all in the $5,000 range. 

That felt steep and the waste was a bit heartbreaking, so I challenged myself to rehome as much of it as possible, aspiring to keep the gently used household goods out of a landfill. How many free donation pickups could I arrange without losing valuable time? It was worth a try, and the results surprised me.

How to give things away

I turned to Facebook Marketplace, BoCoCa’s Buy Nothing group, Etsy creators, Ebay collectors, and even passers-by to move truckloads of stuff to anyone who could pick up. Individuals, businesses, and non-profits turned up to cart away free items, one-by-one, by the bag, by appointment, and from the curb. 

A five-piece, mid-century bedroom suite went to a Park Slope neighbor who figured the cost of renting a U-haul to move it was worth the two-hour investment. A seven-piece dining set appealed to a Queens-based Facebook Marketplace shopper, though getting it out through the window proved to be a feat of amateur engineering. A garden statue of St. Anthony required two people to carry to the curb, where it attracted the attention of a local photographer before disappearing under cover of night. I later found a black-and-white photo of my client’s father posed beside the statue, bursting with pride.

On Instagram I discovered a Missouri-based Etsy Store that refurbishes and resells wedding fashions. They covered the shipping for a 1950s wedding dress and beaded headpiece. An Ebay seller came to collect a vintage army uniform. A kitchen table and appliances were re-homed by CHIPS. Pounds of clothes, linens, purses and shoes were collected by St. Mary’s clothing drive. An antique radio credenza was repurposed for an Alexis Bittar commercial. Religious relics, dishes, cookware and utensils, card tables and games, power tools, grill and more moved swiftly out of the home and into the community. 

Setting up an on-site office made things infinitely easier. I greeted pickup appointments and groused at the ghosters and flakes. Yes, the flake-rate was high. If you’re doing something similar, set your expectations accordingly and advertise as a “first-come, first-served” operation. It’s wild to discover how many people will actively engage with you on Facebook Marketplace and then never show. 

The bulk of the estate found new homes across the neighborhood where my client’s family set down roots and lived out generations. When I close my eyes, I can picture her floral housecoats peppering the landscape of BoCoCa’s stoop sweepers, her armoire storing costumes at a Greenpoint community theatre, her holiday decorations rewarding students in district elementary schools, and on and on. 

Reaping rewards

In the end, Junkluggers carted away 1.5 trucks worth of stuff, instead of the six originally estimated, of obsolete technology, a defunct bar fridge, some broken irreparable furnishings, opened pantry items, and hazardous waste (like paint cans and unlabeled cleaners).

Dissolving a few estates has taught me the benefit of re-homing gently used things. The effort is rewarded not only in dollars; it expanded my community, introducing me to local organizers, volunteers, artists, designers, teachers, residents, and business owners. 

The house went to market on schedule and was under contract within two weeks. It sold for more than $2 million—all cash—because once the property was cleared, buyers could easily see its potential. 

By thrift and resourcefulness, collaboration and expertise, I helped secure my client’s future, breathed new life into treasured possessions, and deepened my appreciation for this unique place, where one person’s collection of “junk” finds its way to a hundred to treasure it.



Source link

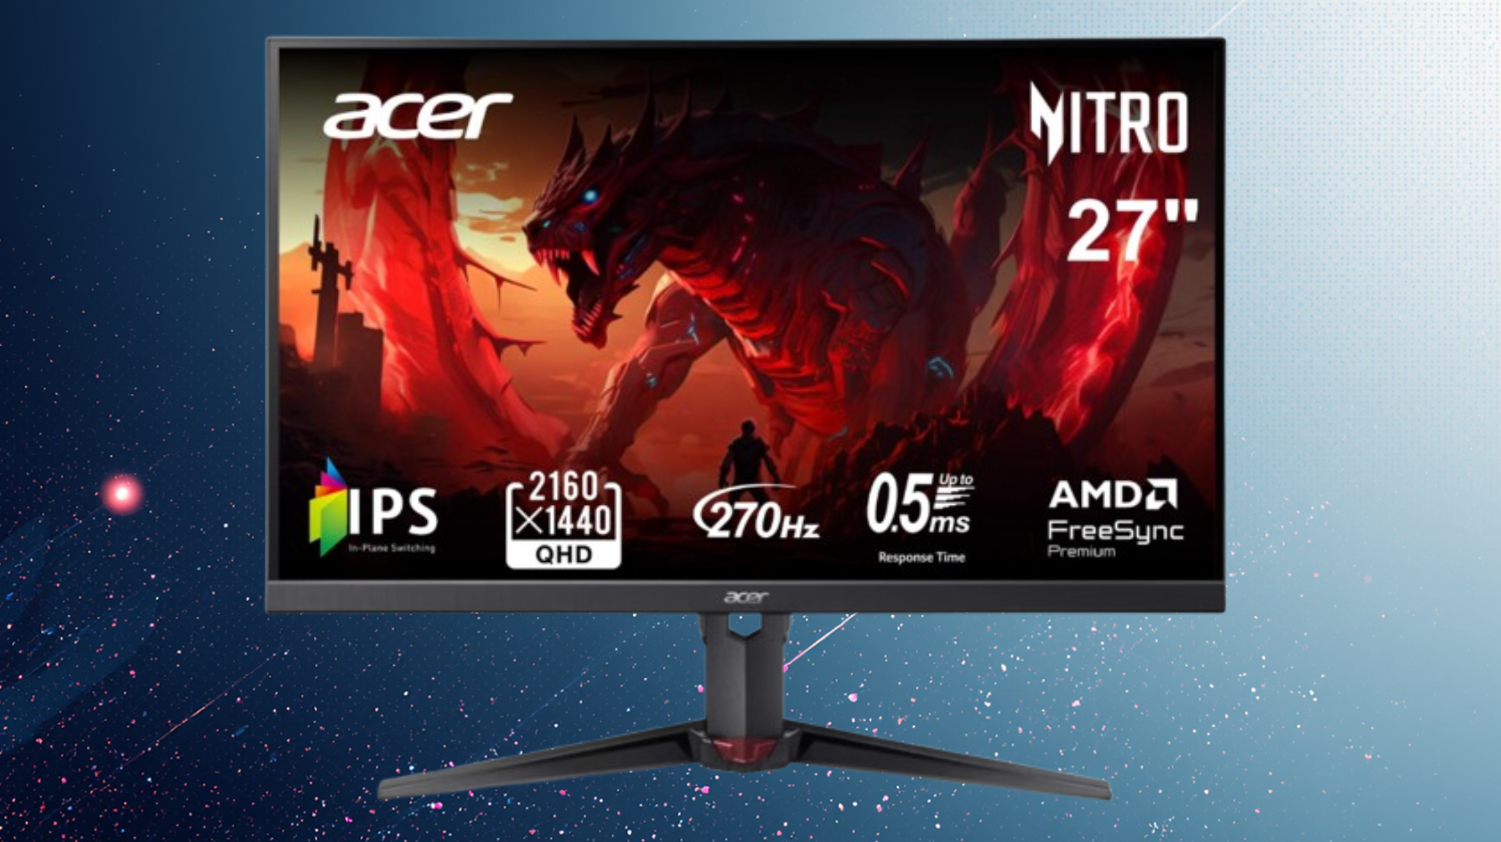
Upgrade your gaming experience with this 27-inch Acer 1440p 270Hz panel that’s an incredible 45% off — just $179 buys an awesome IPS monitor with AMD FreeSync Premium and 1ms response time


While RAM, video cards, and storage have become the most expensive parts of a PC build or upgrade, monitors haven’t really flinched price-wise. They can still offer a tangible upgrade, whether for gaming or productivity, for your PC. After all, you are staring at it the entire time you use your PC. Acer is currently offering an incredible deal on the Nitro (XV270U). Just $179 (a whopping 45%/$150 off the $239.99 MSRP) buys a 27-inch 2560×1440 IPS panel with a wicked-fast 270 Hz refresh rate without breaking the bank.


Source link

Beat the Switch 2 storage crisis with this $99 512GB microSD Express card — Amazon deal slashes 33% off high-performance Samsung P9


The flash shortage has driven up prices for nearly all consumer storage devices. Fortunately, for a limited time, Nintendo Switch 2 owners have a rare opportunity to secure a high-performance Samsung P9 512GB microSD Express card for just $99.99, the original MSRP before the shortage began. Amazon’s $50 checkout discount makes this deal even more enticing, since the microSD Express card typically retails for $149.99.


Source link

3 Things You Can Actually Control About Your Mortgage Rate Right Now


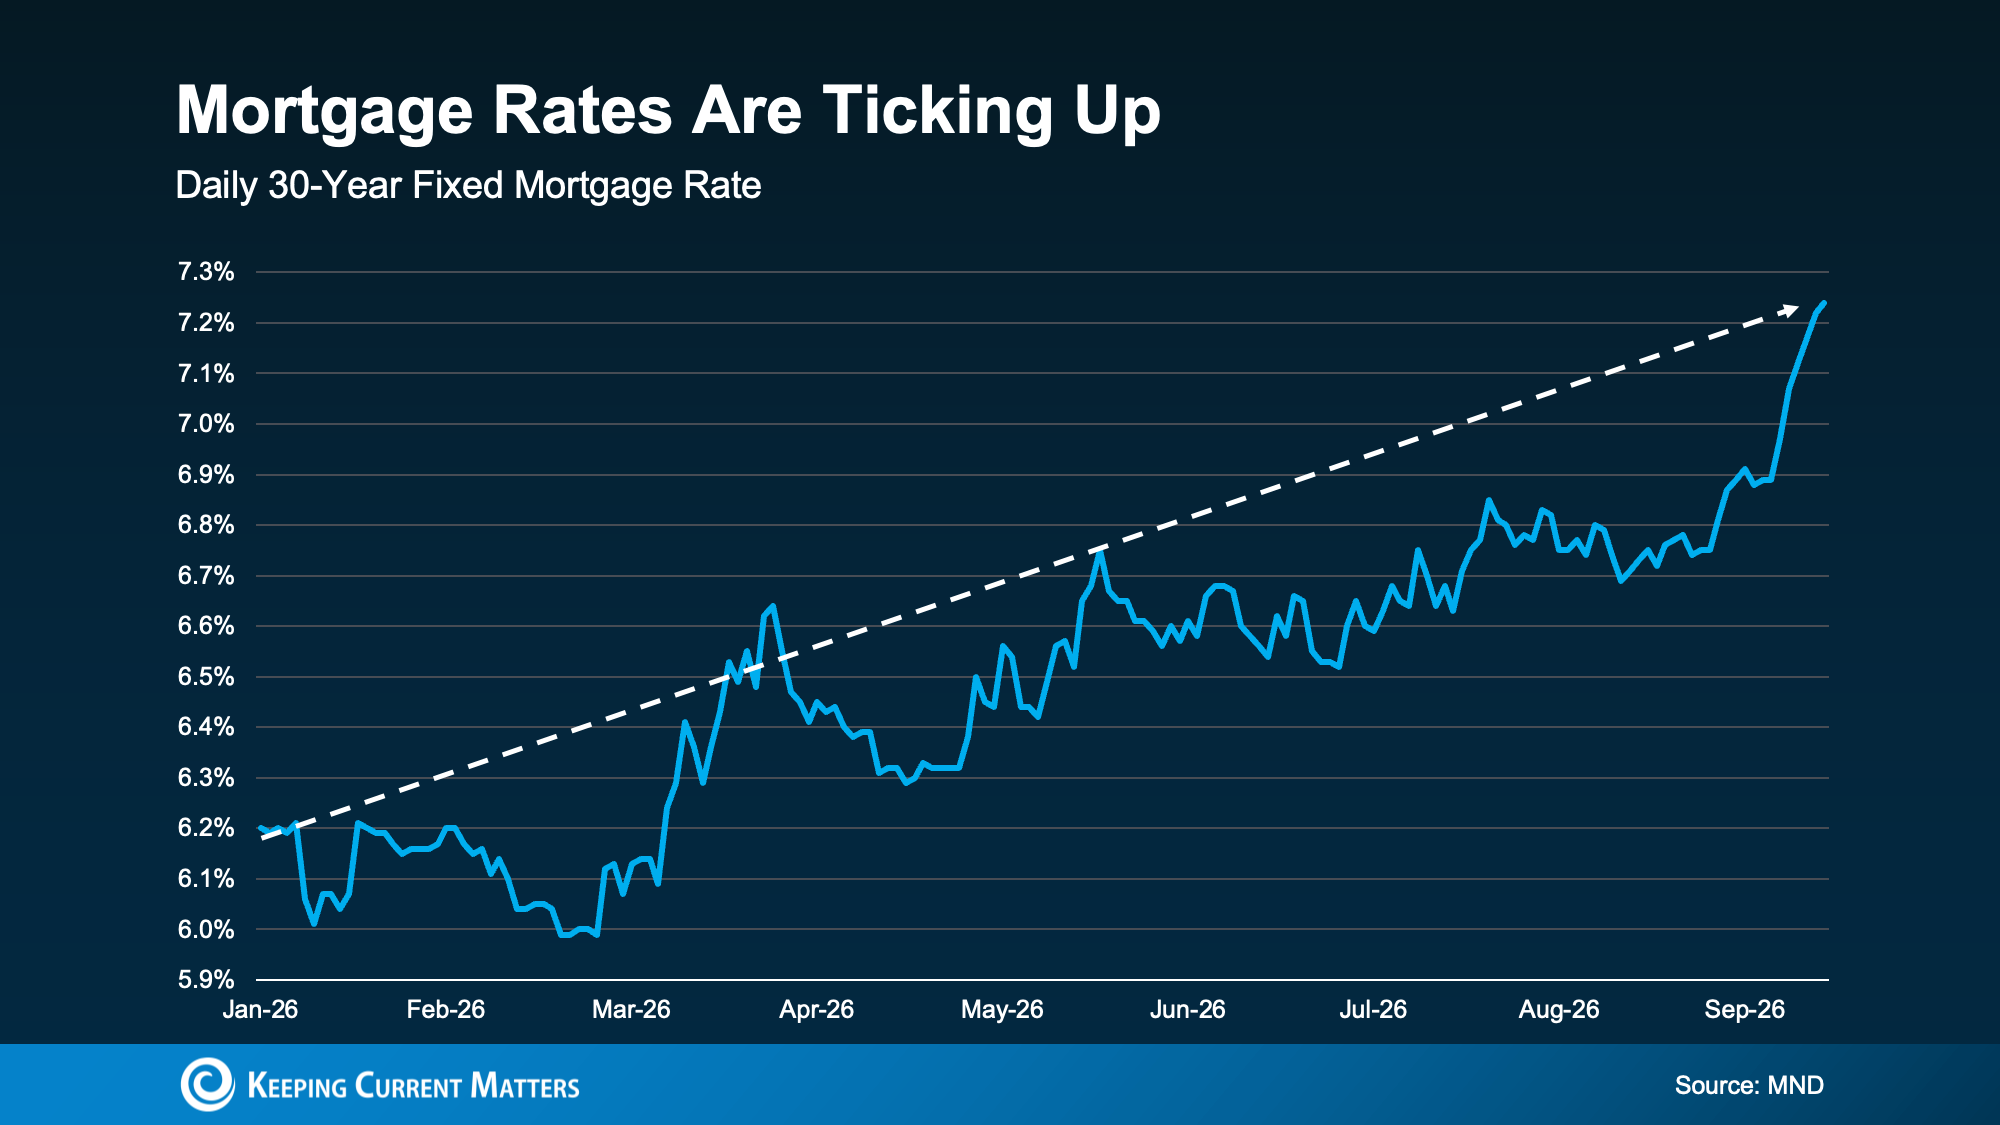
If you’re trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and wait for them to go down.

For now, though, they’re headed the other way. Mortgage News Daily data shows how rates have risen this year (see graph below):

a graph of a moving rate

And if you’re wondering why? There are actually a number of reasons. 

Mortgage rates are impacted by the situation overseas, economic data, inflation numbers, oil prices, and even decisions from the Federal Reserve (who recently decided to hike their Fed Funds Rate – which often affects mortgage rates too). As Danielle Hale, Chief Economist at Realtor.com, explains:

“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”

Now, that’s probably not what you wanted to hear. But, it doesn’t mean there’s nothing you can do. While you can’t control where rates go from here, you absolutely can control several things that shape the rate you actually get. 

So where should you focus? Let’s walk through it.

Work on Your Credit Score

Your credit score plays a big role in the rate you qualify for, and even a small improvement can make a real difference in your monthly payment. As Freddie Mac puts it:

“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.“

So, make sure you do what you can to keep your credit score up. If you’re not sure where your score stands right now, or how to improve it, talk to a trusted loan officer.

Explore Your Loan Options

The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each come with their own requirements and rates, and your term (15, 20, or 30 years) changes both your payment and the total interest you’ll pay. The structure matters, too. A fixed-rate loan holds the same rate over time, while an adjustable-rate loan usually starts lower and can move later on. Bankrate explains it this way:

“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.“

It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision. You may even want to talk to multiple lenders to see how the options vary. 

Consider a Newly Built Home

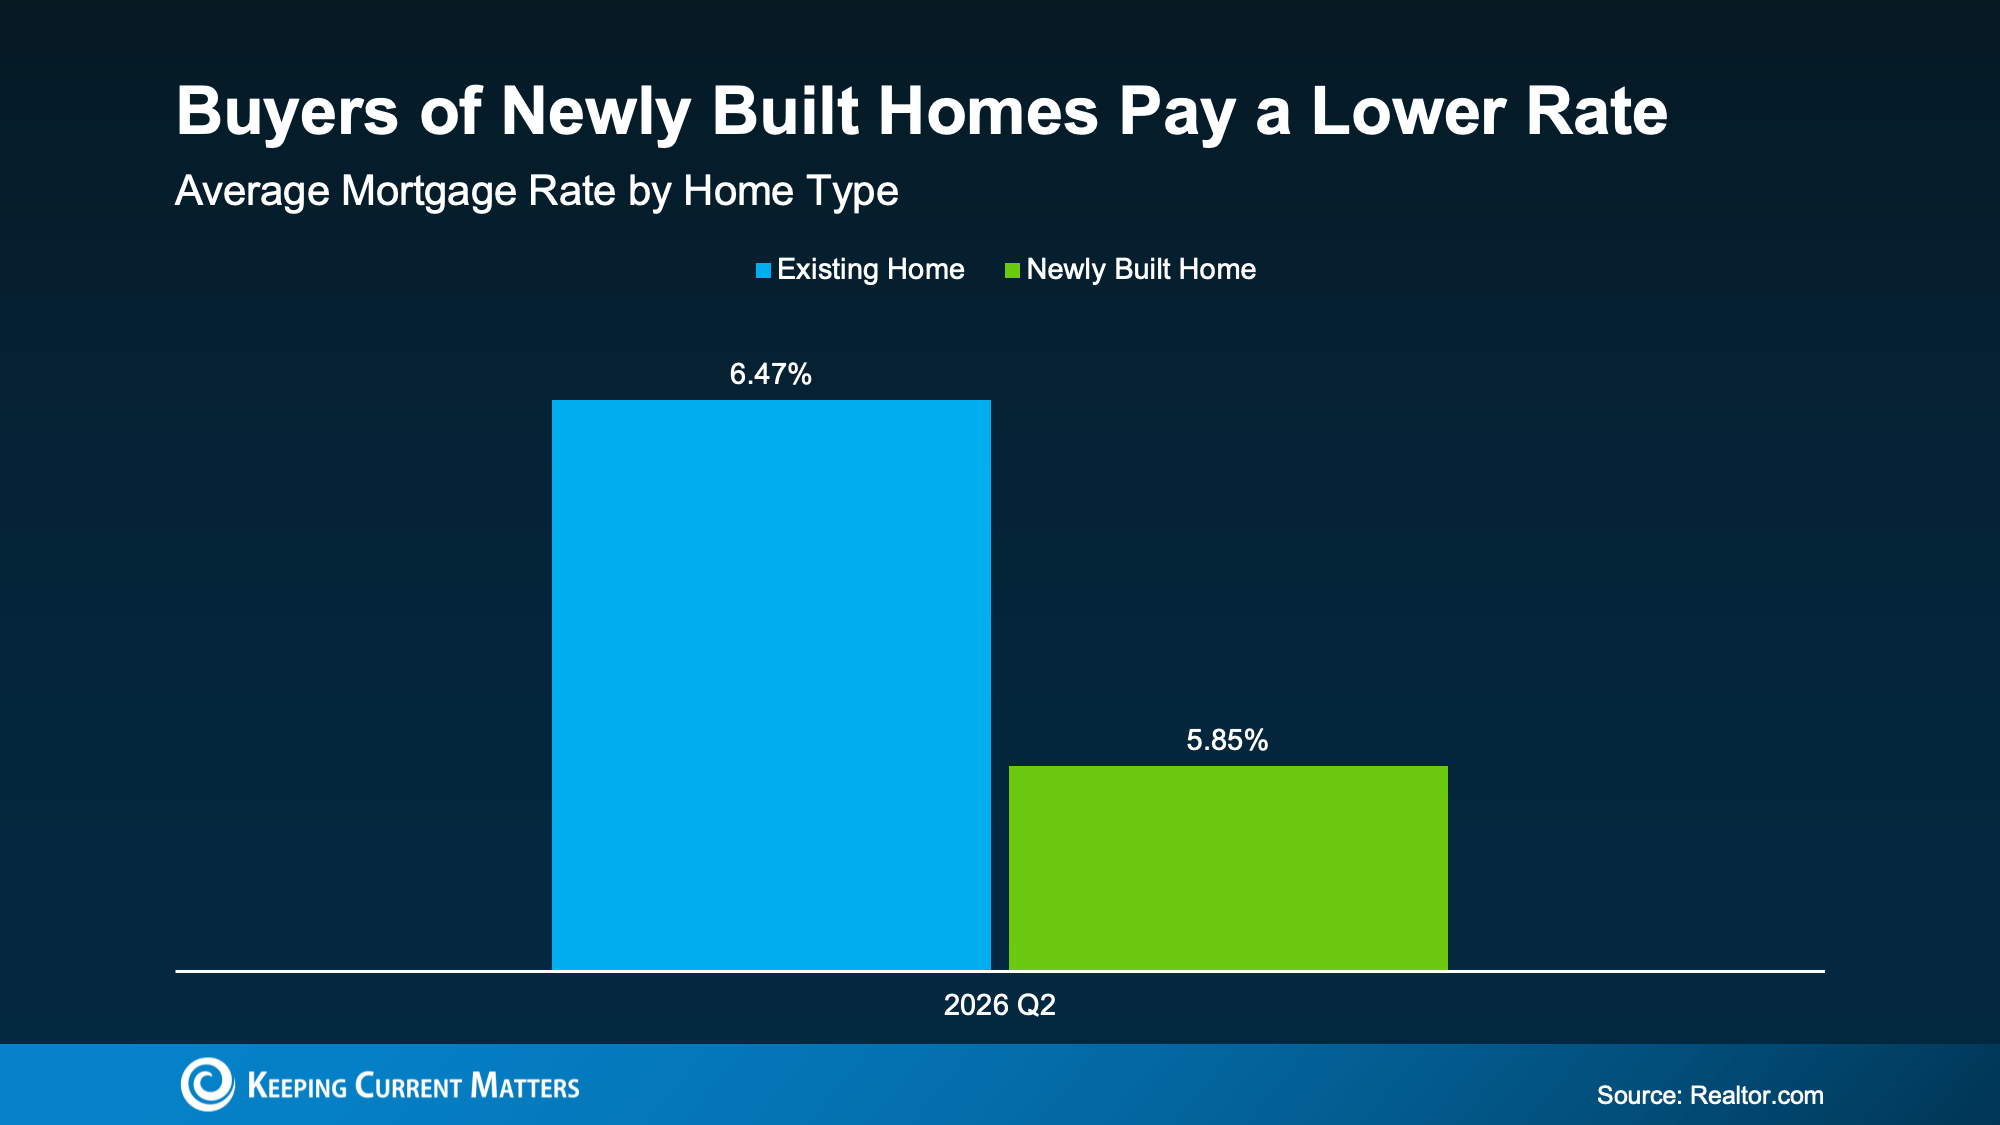
Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down mortgage rates, which lowers your monthly payment. It’s just one way they’re trying to attract buyers and get their homes sold.

According to Realtor.com, buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):

a graph of a graph showing a number of houses

If a lower rate is your goal, it may be worth asking your agent to show you some new build communities that are offering this type of incentive locally.

Bottom Line

You can’t control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for. And when you’re ready to make a move that fits your budget, connect with a local real estate agent.


Source link

My landlord is taking me to court for not paying rent and I’m planning on using AI to prepare for the case. Is that a good idea?


My landlord is taking me to court for not paying rent and I’m planning on using AI to prepare for the case. Is that a good idea?

Using AI instead of getting legal advice from an actual human is only something you should consider as a last resort.

“Cautiously I say no, it’s not a bad idea,” said attorney Ronald Languedoc, a partner at Himmelstein Gribben and Joseph who specializes in tenant law. He said that if you are representing yourself in housing court, consulting a chatbot is an option if you can’t get a lawyer or want to do some initial research to find out if you have a case, but turning to a real lawyer is always a better bet. (Free legal assistance is available to low-income New Yorkers facing eviction through NYC’s Right to Counsel.)

However, you should understand that the more you rely on AI research, the greater the likelihood that you will be led down the wrong path and served incorrect information, Languedoc said. “It may not be that effective to use if you don’t know how to frame the question.”


[Editor’s note: Realty Bites tackles your NYC rental questions. Have a query for our experts? Drop us an email. We respect all requests for anonymity.]


Chatbots are trained to be agreeable, which could mean an AI model might bake your faulty assumptions into its responses. Models can generate fake citations or cases as supporting evidence, so it’s important to double check any information by reading the case law yourself. AI chatbots may also misinterpret what a case says or lack the nuance for understanding which cases are relevant to your legal issue. 

Some cases are most likely too complicated for large language model chatbots, especially cases involving NYC’s rent regulation or rent stabilization rules, Languedoc said. 

Other pitfalls to watch for

A judge can sanction you for using AI if your filings cite nonexistent cases or laws. A group of NYCHA tenants learned this the hard way in 2025, when a judge said he would deny an injunction to protect their homes from demolition because their AI-generated brief referenced cases that didn’t exist. 

“Judges have been getting harder and harder on attorneys and even tenants who submit papers to the court based on AI research that they haven’t checked, and it turns out to be inaccurate,” Languedoc said. 

Tenant attorney Altagracia Pierre-Outerbridge, founder of Outerbridge Law and a Brick sponsor, said that AI often misses when it instructs a tenant on how to address a court. That could lead to you inadvertently irritating the judge responsible for your case.

Pierre-Outerbridge said that practiced attorneys know the housing court judges as individuals, including what arguments won’t convince them. “AI doesn’t know the humans,” she said. The false confidence you get from your AI research may make you appear arrogant, which won’t endear you to lawyers or court officials. 

Using AI to prepare for your meeting with a lawyer

Sometimes tenants arrive at attorney consults armed with pages of AI-generated responses, but those take time for your lawyer to go through, which could end up costing you money.

“If the information is correct, then we already know it. If it’s incorrect then it’s going to waste my time,” Outerbridge-Pierre said. 

Languedoc said it can be frustrating for attorneys, who sometimes feel like AI is acting as an unhelpful third party in his discussions with a client. “You wonder if the client is really being better served or not,” he said.

However, these tools can be useful for parsing your own records or summarizing them, Pierre-Outerbridge said. AI can allow you to quickly combine data points into a digestible format such as a timeline.

“It’s good if you don’t want to look at your email for three years worth of messages about leaks,” she said. “It’s good if you have a lot of information and you want to tie it up.”


Source link

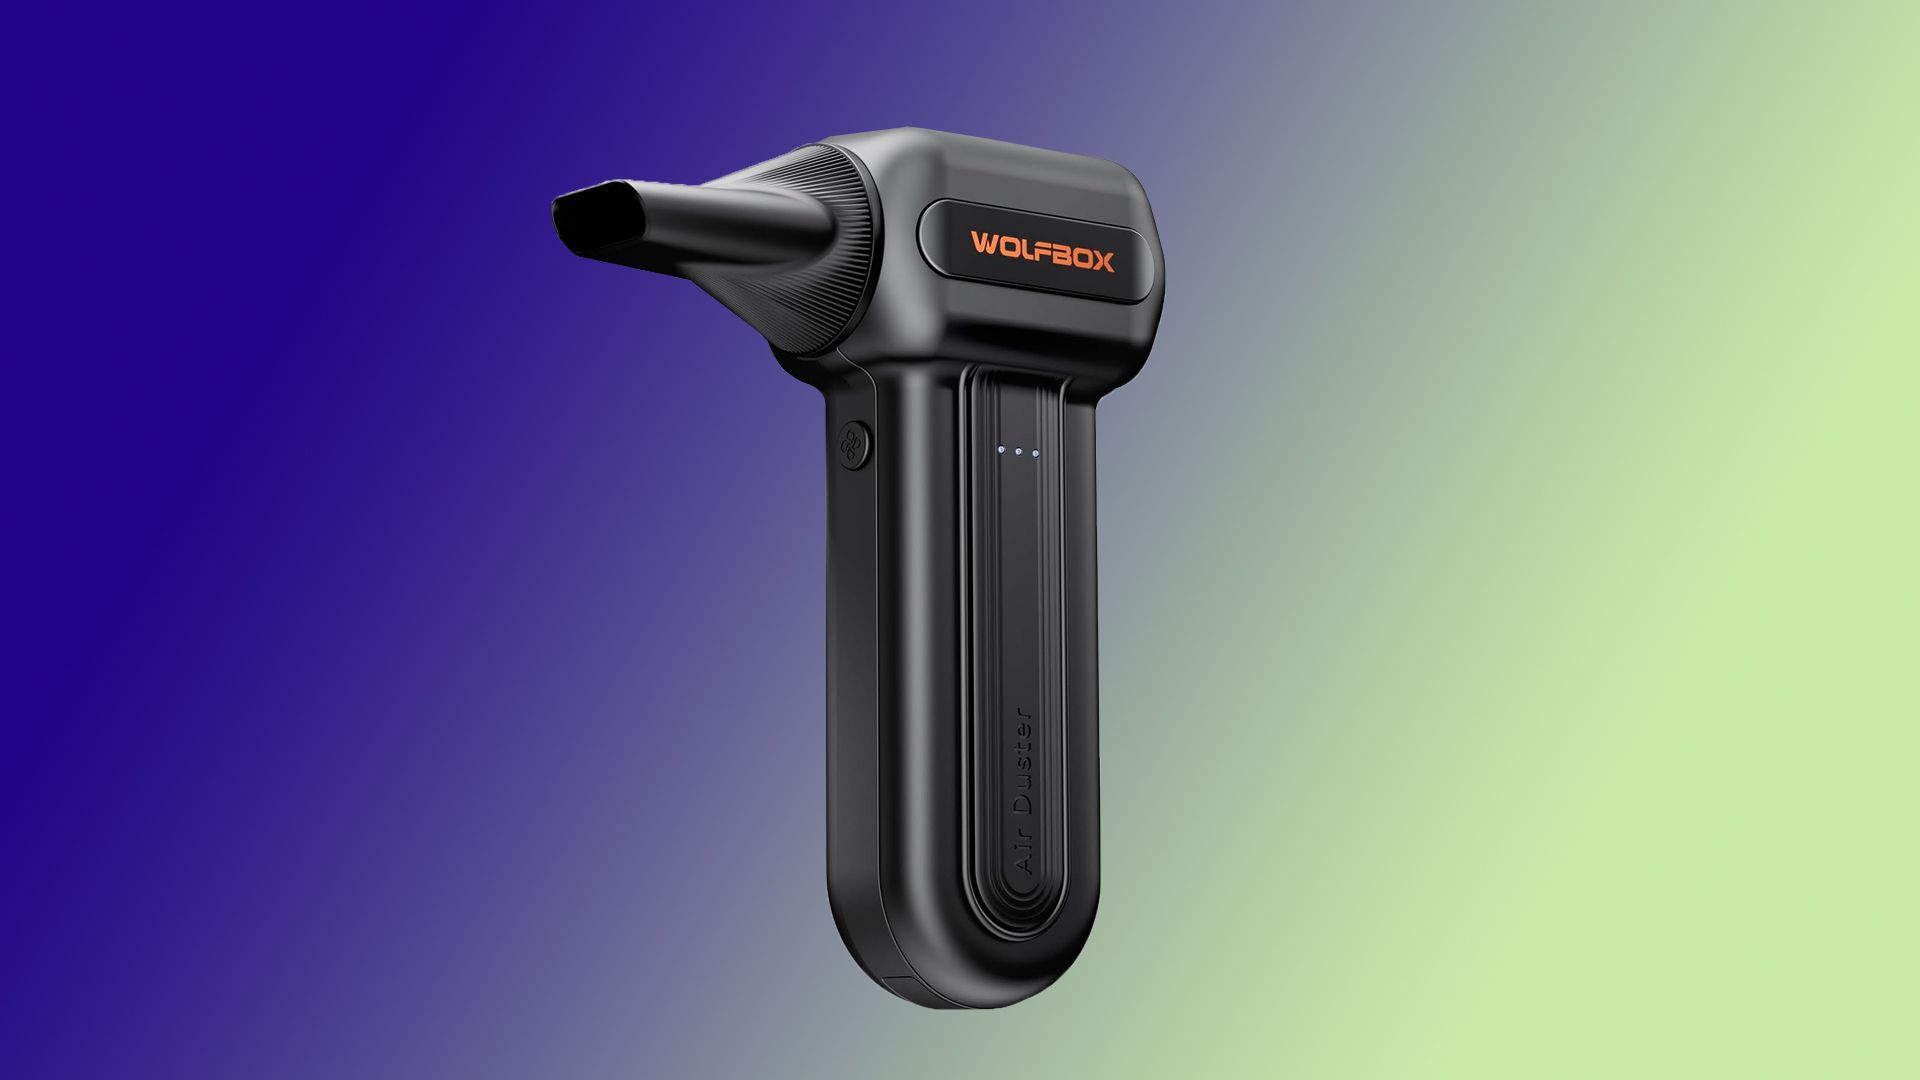
Give your PC the deep clean it deserves — the Wolfbox MF60 Air Duster with up to 110,000 RPM drops to $33.99


Dust buildup is one of the primary causes of performance throttling and it is highly recommended to clean your PC as part of its regular maintenance. One of the easiest ways to keep your system dust-free is to invest in a powerful air duster. Right now the Wolfbox MF60 is currently available at a 32% discount on Amazon, bringing the price down from $49.99 to just $33.99.


Source link

What is the tenant blacklist? Can it prevent me from renting in NYC?


Searching for an apartment in New York City is always challenging—even more so if you’ve ever been involved in a housing court case in the past. This can land you on the dreaded tenant “blacklist,” with the possibility of being shunned by prospective landlords.  

But thanks to changes to New York’s rent laws in 2019, landlords can no longer refuse to rent to someone solely based on housing court data. These changes matter for many tenants facing eviction or seeking an affordable place to live.

Read on to learn how the tenant blacklist affects NYC renters.


[Editor’s note: An earlier version of this article was published in September 2025. We are presenting it again with updated information for September 2026.]


What is the tenant blacklist? 

If you end up in NYC housing court for any reason, your name will typically come up in court data searched by tenant screening bureaus, known as TSBs. The collected data is often called the tenant blacklist, even though it isn’t actually a list. Instead, companies gather this public information and provide it, along with credit reports, to landlords when they screen tenants during the rental application process.

How can you end up on a tenant blacklist?

One lingering consequence of the pandemic is that it drove thousands of tenants into legal disputes with their landlords, leaving more New Yorkers with a housing court record in their rental history.

Another reason you could end up in housing court is nonpayment of rent, including withholding rent to force your landlord to make repairs—an essential tenant right.

The problem is the housing court record doesn’t tell the whole story. It shows that a tenant had a dispute with a landlord, but not necessarily why the case was brought, who was in the wrong, or how it was ultimately resolved. In other words, the tenant could end up flagged simply for being in housing court—even when they had a legitimate reason for being there. 

And unlike information reported by consumer reporting agencies, which is subject to time limits under the the Federal Fair Credit Reporting Act, housing court data is not limited to any particular time period. That means it could potentially remain part of the publicly available record indefinitely. 

How do you get off a rental blacklist?

Landlords can’t refuse to rent if they find out you have a complicated tenant-landlord history. When this law changed in 2019, the intention was to ensure renters would feel confident bringing legal actions against a negligent landlords. Landlords who use housing court information to screen incoming tenants now face a fine of up to $1,000 if the attorney general investigates a complaint. 

Despite the legal protection, if you think your name will come up in a NYC housing court search—either erroneously or not—there are valid reasons to try to get your name removed.

Attorney James B. Fishman, a partner at FishmanLaw Group, said it’s still possible a landlord will come up with another reason to reject you if they see your name in housing court data. He added that the law preventing discrimination for involvement in housing court only applies in New York State, so if you move elsewhere, your record is available to an out-of-state landlord.

“If you are interested in formalizing an agreement with your landlord about moving out of your apartment, be sure that it does not permit the landlord to commence a housing court proceeding unless you fail to honor the agreement,” Fishman said.

According to tenant attorney Sam Himmelstein, a partner at Himmelstein Gribben & Joseph (now retired), if the relationship between the former landlord and tenant is cordial, the settlement terms can include a condition that the landlord provide a letter of recommendation and a positive reference. You can attach this letter to future rental applications. 

How do you avoid the tenant blacklist?

If you have a lawsuit pending and an attorney lined up, you may be able to contact the landlord’s attorney and ask them to list you only as John or Jane Doe instead of your real name so the housing court information remains anonymous. According to Himmelstein, most landlords will agree to do so. 

In addition to being anonymous, you might be able to get the other side to sign an out-of-court settlement agreement whereby the landlord would only file a court case if you breach the settlement agreement. “That way, there wouldn’t even be a filing, which is the safest scenario,” he said. It can be harder to get landlords to sign such an agreement, but most will still do it, Himmelstein said. 

Instead of taking a case to housing court, another route is a tenant-initiated housing part action. This is where you sue your landlord for failing to comply with housing law, typically this is done for cases involving building repairs. A housing part action is pretty straightforward: A tenant fills out a form to request an apartment inspection for violations. The city sends an inspector, and the landlord can face steep fines if violations are found. If the court finds in the tenant’s favor, the landlord must make the repairs by a specific time.

What are my rights as a renter? 

Banning the use of publicly available data is problematic. For starters, anyone can access this information. Landlords still want to screen tenants, and some may think the benefit of weeding out troublemakers is worth the risk if they get caught. 

In fact, Fishman said landlords will use pretexts other than a housing court case to deny someone an apartment and avoid violating the law. “As a result, these tenants cannot show that they’ve been damaged by an inaccurate credit report and therefore cannot sue under the Federal Fair Credit Reporting Act,” he explained. 

The law doesn’t allow a tenant to sue a landlord for using court data to deny an application, but the Attorney General has made moves to crack down on tenant blacklisting. A settlement against Clipper Equity, a real estate company that denied applicants with past housing court records, was a recent effort to eliminate the practice. If you think you have been discriminated against in this way, you can file a complaint with the Attorney General’s office. 

If you have served time, a 2025 law that makes it illegal for most landlords and brokers to turn down renter applications based solely on conviction history. The Fair Chance for Housing Act (FCHA) aims to prevent housing discrimination against renters who have a criminal conviction and done their sentence, a bias that contributes to housing instability and homelessness. For more, read: “New law aims to give NYC renters who served time a fair chance at housing.”

What information can NY landlords ask for? 

New York landlords and property managers have been forced to adjust their screening processes and should no longer request eviction or housing court information. Instead, they will likely raise other standards, like minimum credit scores or income-to-rent ratios, to offset their risks.

Most NYC landlords require a photo ID, your last two pay stubs, three months of bank statements, and two years of tax returns, plus a letter of employment on company letterhead stating your job title, length of employment, salary, and any expected bonus. If you are self-employed, you’ll need a letter from your accountant, proof of any other funds like stocks or bonds, a reference letter from a previous landlord if applicable, and contact information for prior landlords. You may also be asked for personal or professional, reference letters. Check out “Need to rent in NYC? Here’s what to do before you even start looking at apartments” for more guidance. 


Source link