Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.


Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is. 

Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.

Why Dipping into a 401(k) Can Be Tempting

Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
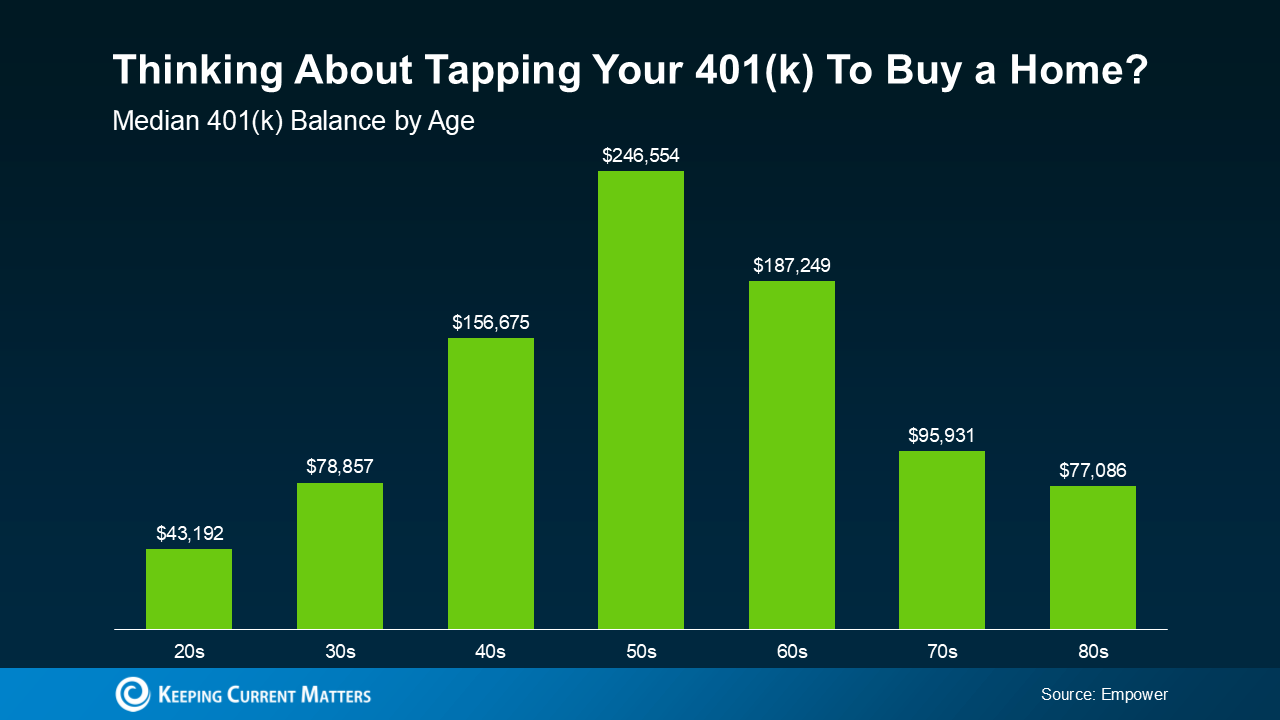
a graph of green barsAnd when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.

But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says: 

“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.“

Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):
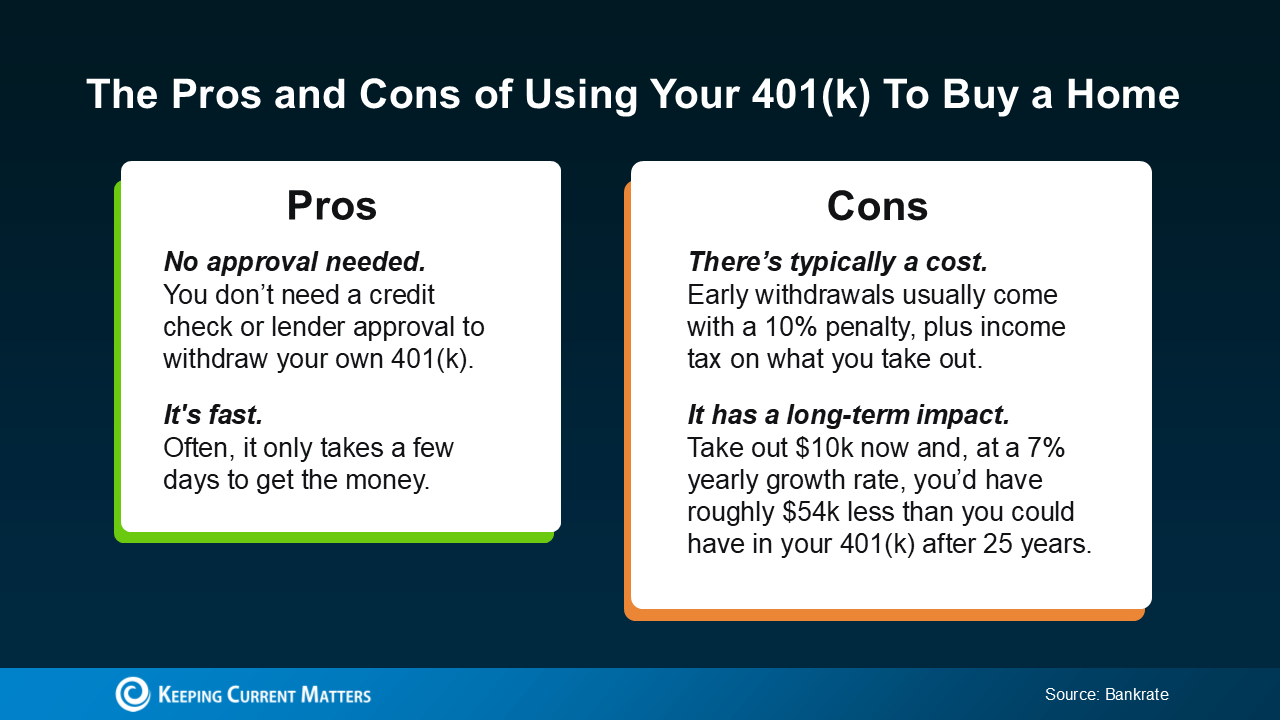
a screenshot of a computer screen

Other Options Worth Exploring First

Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:

  • Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.

  • Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.

Make a Plan Before You Make a Move

No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:

“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.“

Bottom Line

Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.

If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget. 


Source link

Worried About a Housing Crash? The Numbers Tell a Calmer Story.


A recent survey from Talker Research asked Americans to pick one word to describe how 2026 has felt so far. The winner? Stressful. And honestly, there’s been a lot going on.

So, it’s understandable if you’ve been putting off buying or selling a home until things settle down. But you may be waiting on something that’s already happened. While everything else has felt shaky, the housing market has become one of the steadiest things out there. Look at the data.

Home Prices Have Leveled Out

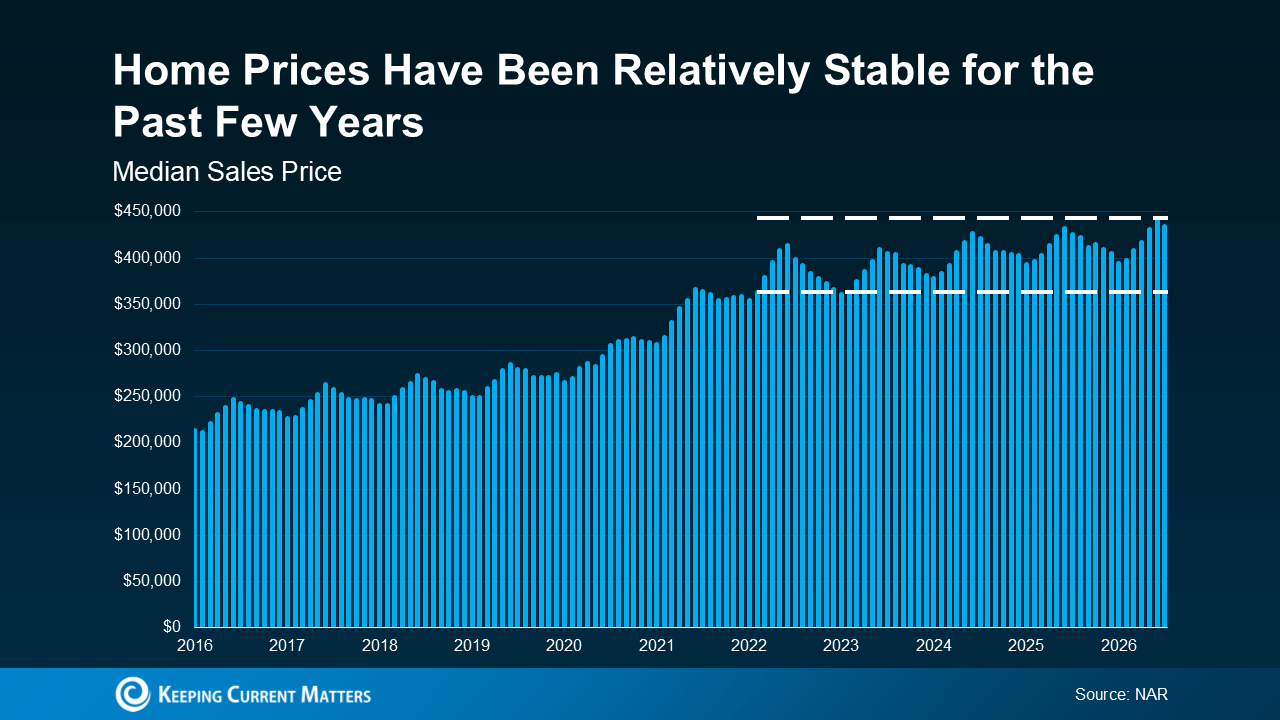
After years of fast increases, data from the National Association of Realtors (NAR) shows home prices have been remarkably steady for the past 4 years (see graph below):

a graph of blue linesAnd experts say that’s what to expect going forward, too. As Selma Hepp, Chief Economist at Cotality, explains:
“In 2026, we expect home prices to remain broadly stable, with modest appreciation at a national level.”

No wild swings. Just slow, steady growth. That’s a healthy market. Of course, that pace can vary a bit depending on where you live. But nationally, steady growth like this makes it easier to plan your budget, whether you’re buying or selling.

The Supply of Homes for Sale Has Steadied

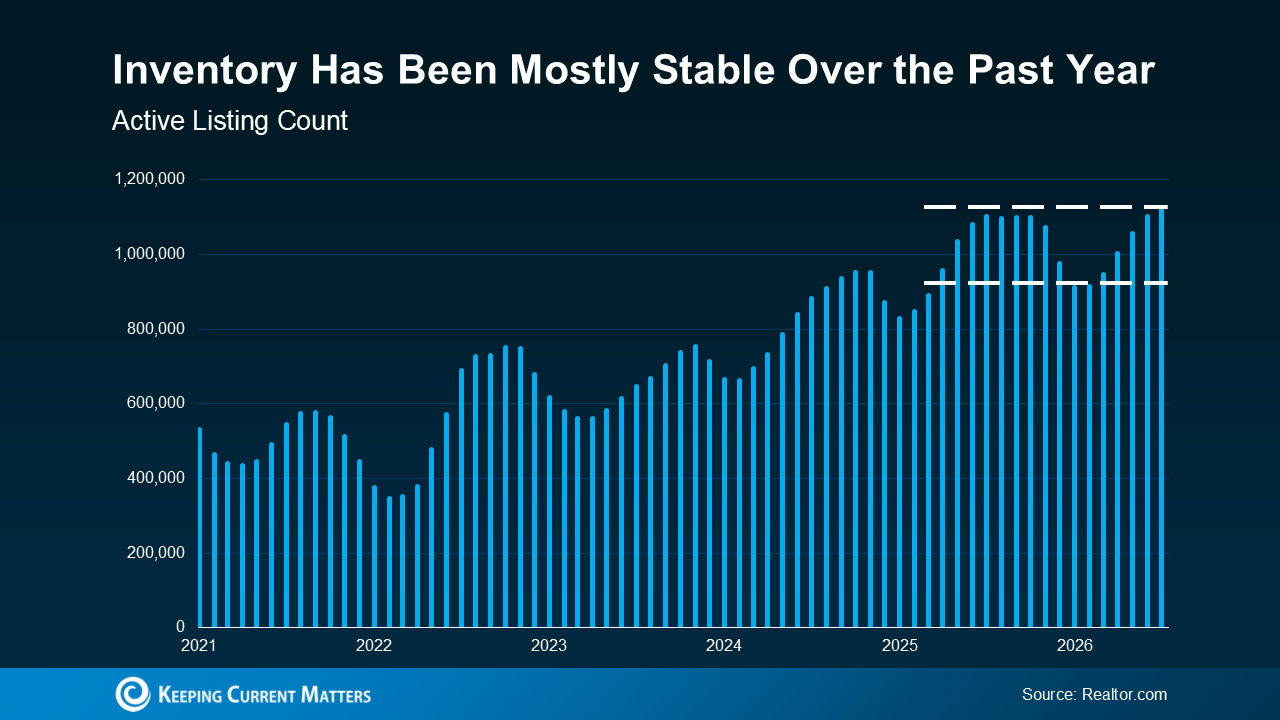
For years, the supply of homes for sale was a moving target. It dropped fast during the pandemic and has been climbing pretty reliably ever since. Now, that pace of growth has slowed down. According to Realtor.com, inventory today is very close to where it was this time last year (see graph below): 

a graph of blue linesThat’s helpful no matter which side you’re on. When the number of homes for sale isn’t changing much, you know what you’re walking into – how many options you’ll have as a buyer, and how much competition you’ll face as a seller.
Mortgage Rates Found Their Range

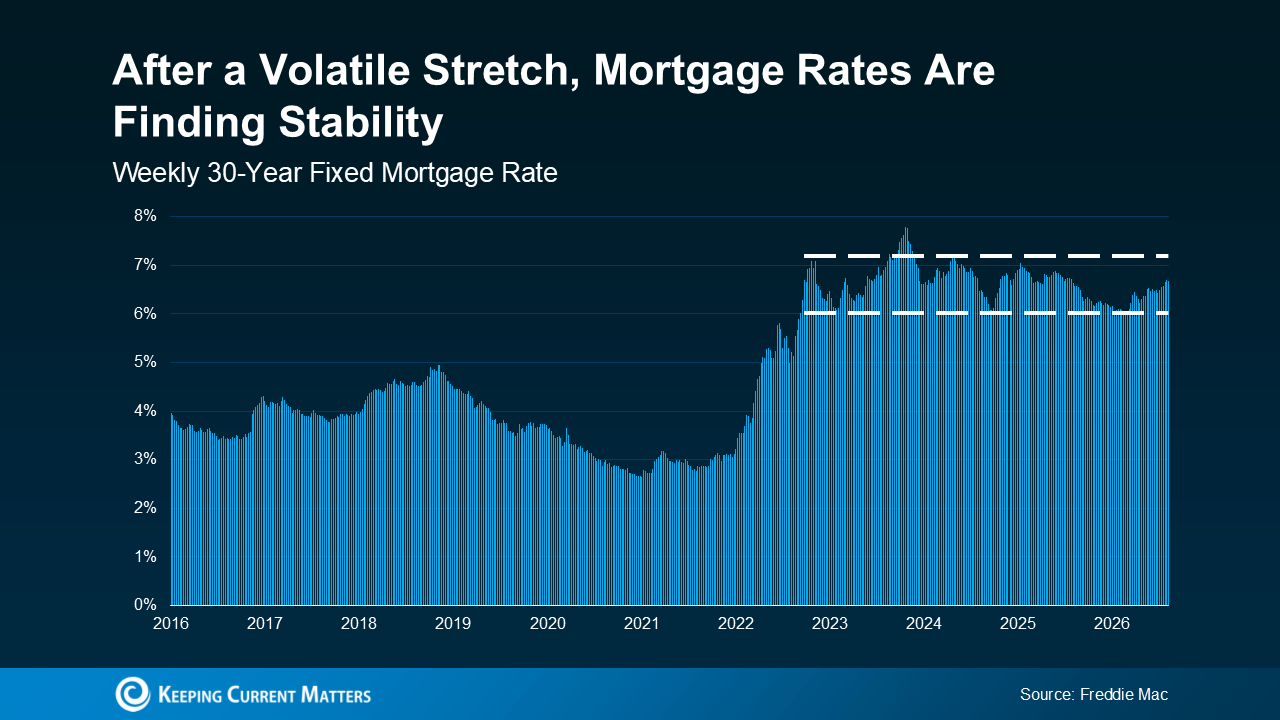
Yes, rates jumped dramatically back in 2022. But since then, Freddie Mac data shows they’ve stayed between 6% and 7% for the better part of the last 3 or so years (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph ofYes, there was one brief spike above that threshold, but overall, rates have stayed in that range for a while now. That predictability helps when you’re planning a move. 
And now that this seems to be a longer-term trend, people have accepted it as the new normal. Buyers have gotten comfortable purchasing in that range, and sellers have gotten just as comfortable listing in it.

That comfort’s important because when both sides know what to expect, they keep making moves. In other words, the market isn’t frozen waiting for something to change. It’s moving calmly.

Bottom Line

The rest of the world may feel unpredictable right now, but the housing market doesn’t have to. Prices, inventory, and rates have all found solid ground.

If stability is what you’ve been waiting for, it’s already here. Connect with a local real estate agent if you want to talk through what that means for your move.


Source link

Sellers Are Cutting Prices To Meet Buyers Where They’re At


You’re scrolling through listings on your phone and everything looks good until you see the price (or the estimated monthly payment). Then you close the app. 

Because even if you love the house, the numbers feel impossible. But here’s the thing.

Nationally, there are more homes sitting on the market than there are people out there looking. And when sellers need buyers more than buyers need sellers, that shows up in the price.

Lower asking prices. More price cuts. And homes priced for what buyers can actually afford – not what sellers hope someone might pay.

And it may be enough to make buying more doable than you’d think. 

4 Out of 10 Sellers Are Cutting Their Price 

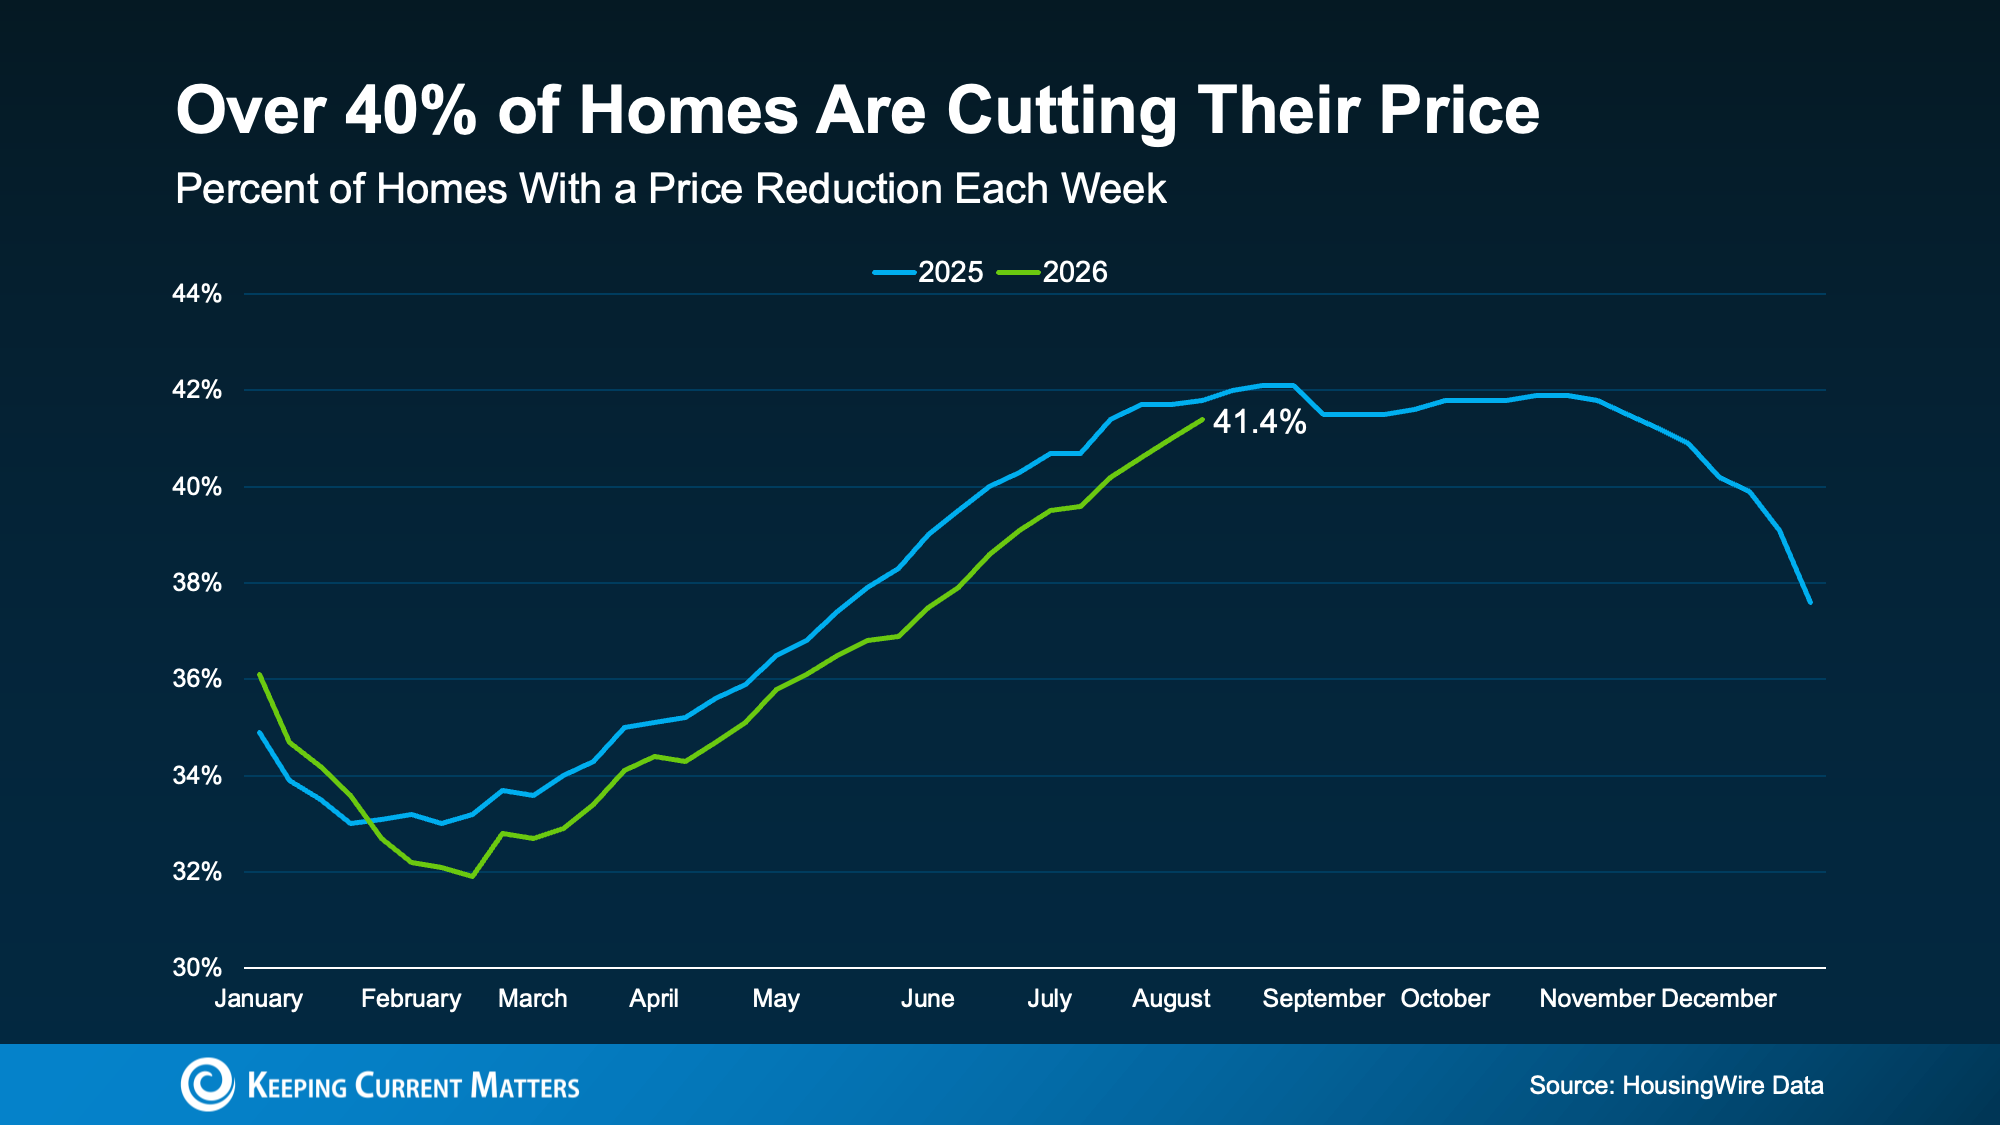
One of the clearest signs sellers are adjusting? Price cuts. HousingWire Data shows more than 40% of sellers are dropping this price.

That’s just slightly behind the volume we saw last year (see graph below):

a graph of a price reduction

That’s more than 4 out of every 10 homes listed. Think about what that means. That’s thousands of sellers deciding they’d rather lower their asking price than keep waiting for someone willing to stretch their budget. 

They know that to sell, they have to be willing to do some give and take. And when no buyers are biting, they’re pulling their biggest lever to draw buyers back in – their price. As Danielle Hale, Chief Economist at Realtor.com, explains:

“This is a market where people are adjusting and showing up rather than giving up. Sellers are meeting the market with more realistic asking prices, which is helping deals get done.”

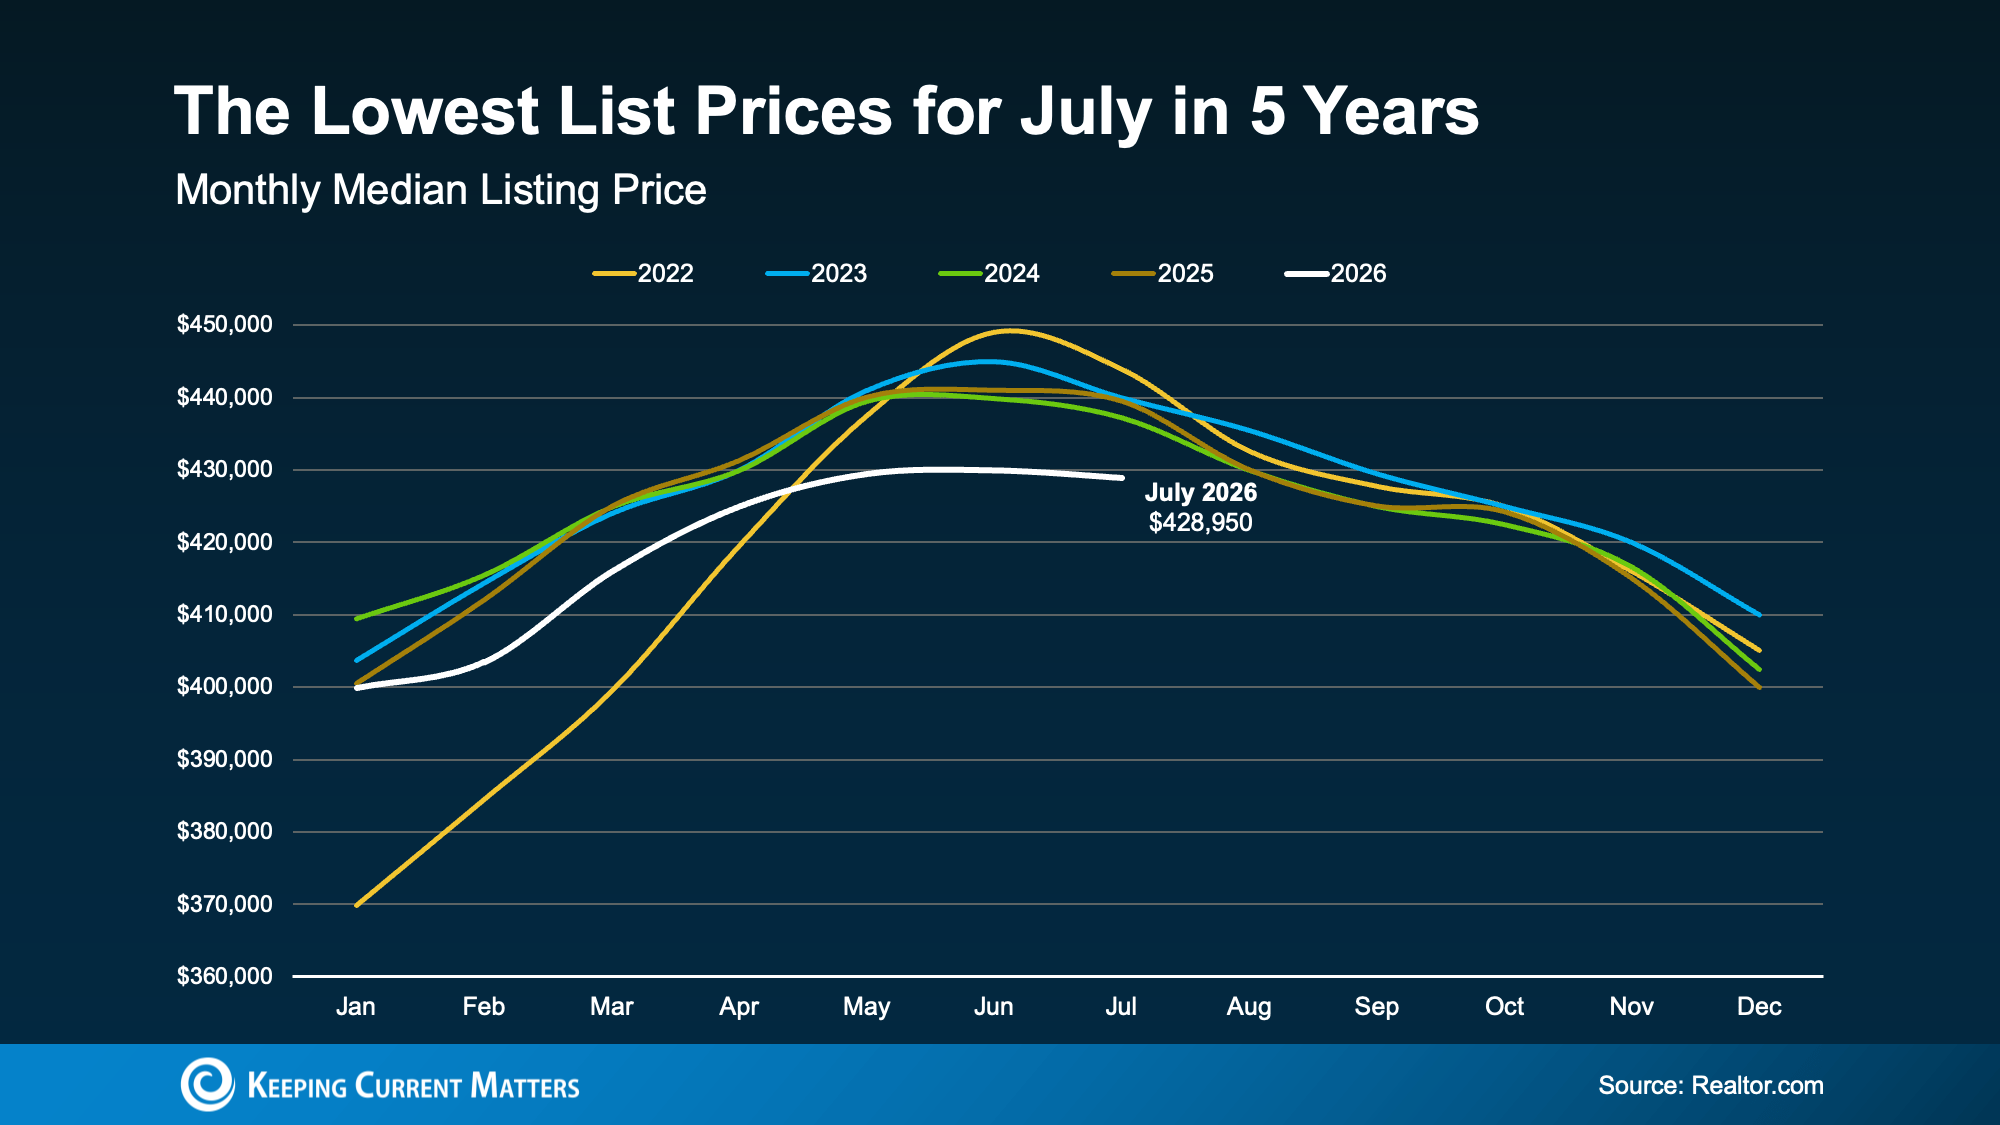
This July Saw the Lowest Median List Price for Any July in Five Years

What about the other 6 in 10 sellers? A lot of them started with a lower asking price to begin with rather than test the higher price and get crickets from buyers.

That may be why July 2026 had the lowest median list price of any July in the past five years, according to Realtor.com (see the white line in the graph below):

a graph of sales and prices

Now, that doesn’t mean home values are falling or that everything’s suddenly a steal. Prices are still above where they were before the pandemic. But what it does mean is this.

Sellers no longer banking on bidding wars or expecting buyers to pay whatever they ask. Instead, many are listing at prices that better reflect today’s market from the very beginning. 

And honestly, whether they’re pricing competitively from day one or adjusting after a few weeks on the market, the message for you is the same:

Sellers are more willing to meet you where you’re at.

Because in many markets throughout the country, you’re not fighting over a house anymore. Sellers are fighting over you. And that’s information you can use to get a better deal.

Yes, affordability can be a real challenge. And the monthly payment you take on definitely does matter. But if you’ve been assuming everything is out of budget, there may be more wiggle room than you think.

Bottom Line

Right now, sellers are flexible on the price in ways they weren’t before. Reach out to a local agent to take advantage of that flexibility.

You may be surprised by what’s available – and how willing today’s sellers are to work with buyers.


Source link

Flood proofing: 3 steps owners can take to prepare for the next big storm


Five years ago, Hurricane Ida ripped through New York City, causing 13 deaths and an estimated $781 million in repair and recovery costs. This August, violent storms have flooded the subway system and even created tornadoes.

While flooding is becoming a bigger problem for NYC as a result of climate change, there are some preventative measures that homeowners can take. Three programs for homeowners administered by the nonprofit Center for NYC Neighborhoods aim to prepare NYC residents’ homes for stormwater flooding. 

“Our goal is to help homeowners know their risk, know what resources are available, and help them find solutions,” said Aaron Sturm, CNYCN’s deputy director of resiliency. 

These three resources work together: One website helps you determine your home’s flood risk, the next program helps you identify repairs for better flood protection, and the third helps you to pay for those improvements.

Let’s dive in (but you should never walk or drive into flood waters):

This website helps NYC homeowners and buyers determine the flood risk of a particular address. It also provides accessible resources that explain flood insurance policies and how they work.

You start by plugging in any NYC address into the site’s search bar. The result displays your risk according to four different flooding maps—FEMA’s outdated flood insurance map, a coastal flood map that is more up to date, and two stormwater flooding maps from NYC’s Department of Environmental Protection. 

If you’re a renter instead of an owner, flooding should still be on your mind. Under a 2023 law, owners must disclose a building’s history of flood events. (While landlords are required to answer truthfully if you ask about past flooding, they don’t need to volunteer information about flooding from mechanical or plumbing problems, so be sure to ask.) 

It’s always a good idea to look for signs of water damage or mold when touring a potential apartment. You should also keep in mind that renters’ insurance doesn’t always cover flooding from storms, so you may need to obtain flood insurance too. 

Although Zillow removed flooding risk scores from its site in 2025, Redfin includes data from First Street, a real estate climate risk analytics site, and provides a flood factor score between on a scale of 1 to 10. 

Under this free program, engineers inspect your property for flooding vulnerabilities and suggest changes to limit the damage from storms. 

“The licensed engineer would come out, visit the home, identify any potential vulnerabilities, and then they would prepare a written report and some recommendations,” Sturm said. 

If you are in the flood zone, you’ll also get an elevation certificate, which can help make sure you aren’t overpaying for flood insurance or prove to your insurance company that improvements you made have lowered your home’s flood risk.Thenyou have the option to sit down with a housing counselor to interpret the technical report and make a plan for improvements, Sturm said. 

To be eligible for a free audit, homeowners must:

  • Own and live in a one- to four-unit residential property as their primary residence
  • Have an active home insurance policy 
  • Have a valid state ID

Although the program isn’t restricted by income level, you are also required to provide information about income and the number of household members to ensure lower income homeowners get first priority.

If an audit reveals expensive fixes are needed to protect your property from flooding, there might be money available to you to fund those changes. 

“Being in the audit program doesn’t guarantee the financing, but it does kind of tee you up to know how you can implement some of those actionable items because some of the recommendations can be costly,” Sturm said.

Through a combination of low interest and forgivable loans, this program offers eligible homeowners financing for repairs. If you qualify, you could receive up to $50,000 for repairs, as long as at least 50 percent of the repairs make your home more flood resilient.

That can include things like flood vents or vapor barriers, but also roof repairs, if the materials and structure ensure the roof is better able to withstand flooding. “Basically, you can’t redo your kitchen or just do things that are outside the scope of making your home more resilient,” Sturm said.

To be eligible, homeowners must:

  • Own a property of one- to four-units in NYC and live there as their primary residence
  • Have a household income at or below 120 percent area median income, which is currently $162,840 for a two-person household
  • Be up to date on property tax and mortgage payments 
  • Not have filed for bankruptcy in the past two years

Finally, if you live in an area that’s at high risk for flooding, you have the option to sell your home to the city and move through the city’s Resilient Acquisitions program. This summer, the Mayor’s Office of Climate & Environmental Justice began expanding outreach to new areas of Queens to gauge resident interest, although money isn’t available for buyouts just yet.


Source link

China’s YMTC aims to become the world’s largest NAND maker by the end of 2027, report says — company plans to overtake Samsung and SK hynix


Yangtze Memory Technologies Co. (YMTC) told investors and stakeholders in recent IPO preparation meetings that it aims to become the world’s largest NAND flash producer by the end of 2027, overtaking Samsung and SK hynix, according to a Financial Times report. The Wuhan-based company filed last week to raise 33 billion yuan ($4.9 billion) on the Shanghai Stock Exchange’s STAR Market, with most of the proceeds earmarked for production line upgrades and R&D.

Go deeper with TH Premium: Memory

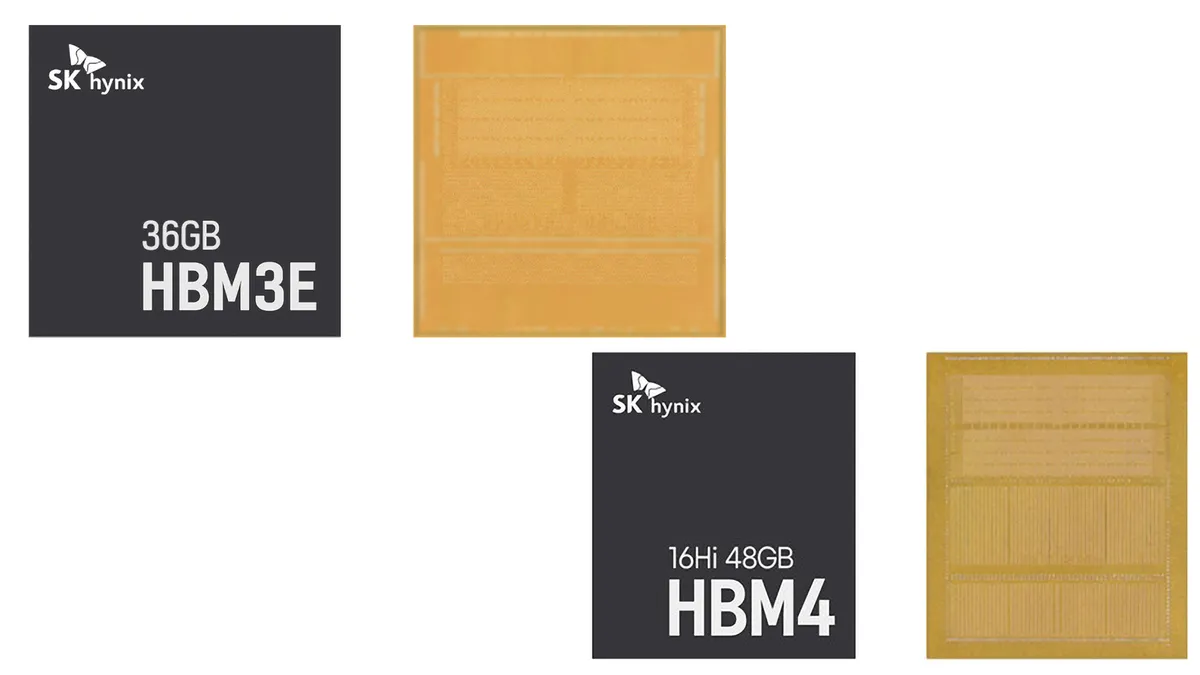
HBM3E vs HBM4

(Image credit: SK Hynix)

The target would require YMTC to nearly double its market share in 16 months. Counterpoint Research put the company at around 14% of global NAND shipments in the second quarter, level with Kioxia, against roughly 25% for market leader Samsung and 22% for SK hynix and its Solidigm subsidiary combined. Analysts currently rank YMTC third globally, and first in China, by both NAND revenue and shipment volume in the first quarter.


Source link

Resurrected RTX 3060 12GB price jumps 45% in the two months since it was revived — 2021-era GPU now costs nearly $500 across most retailers


Nvidia ostensibly brought back the RTX 3060 12GB in late June to help gamers cope with the ongoing component crisis. Since most of the world’s memory is being routed to expensive AI chips, the RTX 3060 12GB offered gamers a 12GB VRAM pool for what was supposed to be a reasonable price… if only the price remained steady. As of today, this five-year-old GPU now costs almost $500 across the world, which is just as much as the RTX 5060.

MSI’s Ventus 2X OC variant of the RTX 3060 12GB launched at just $300 on its online store and $340 on Newegg. It’s now listed for $480 in both places. That’s a 60% increase in less than two months, compared to its lowest price. Similarly, Asus’ Dual V2 OC variant was released with a $330 MSRP, which quickly rose to $360 on Newegg, and the same card is now sitting at $500, constituting a 52% price hike from launch.


Source link

Most Home Sales Close – Here’s How To Keep Yours on Track


Few things are as rattling as the thought of your home sale falling through at the last minute, right before closing. All that waiting, all that progress, out the window.

But if you’re getting ready to sell, here’s what you should know. Even in today’s market, it rarely comes to that. Buyers who are moving at today’s rates and prices are generally moving because of some big life change. That means they’re motivated, and eager to get all the way to the closing table.

According to the latest data from Redfin, only about 1 in 7 pending sales are falling through. Meaning the vast majority make it all the way to closing.

And the single biggest thing that puts a deal at risk is the one you have the most power to prevent. It just takes a little smart planning before your house hits the market.

Why Some Deals Fall Apart Before Closing

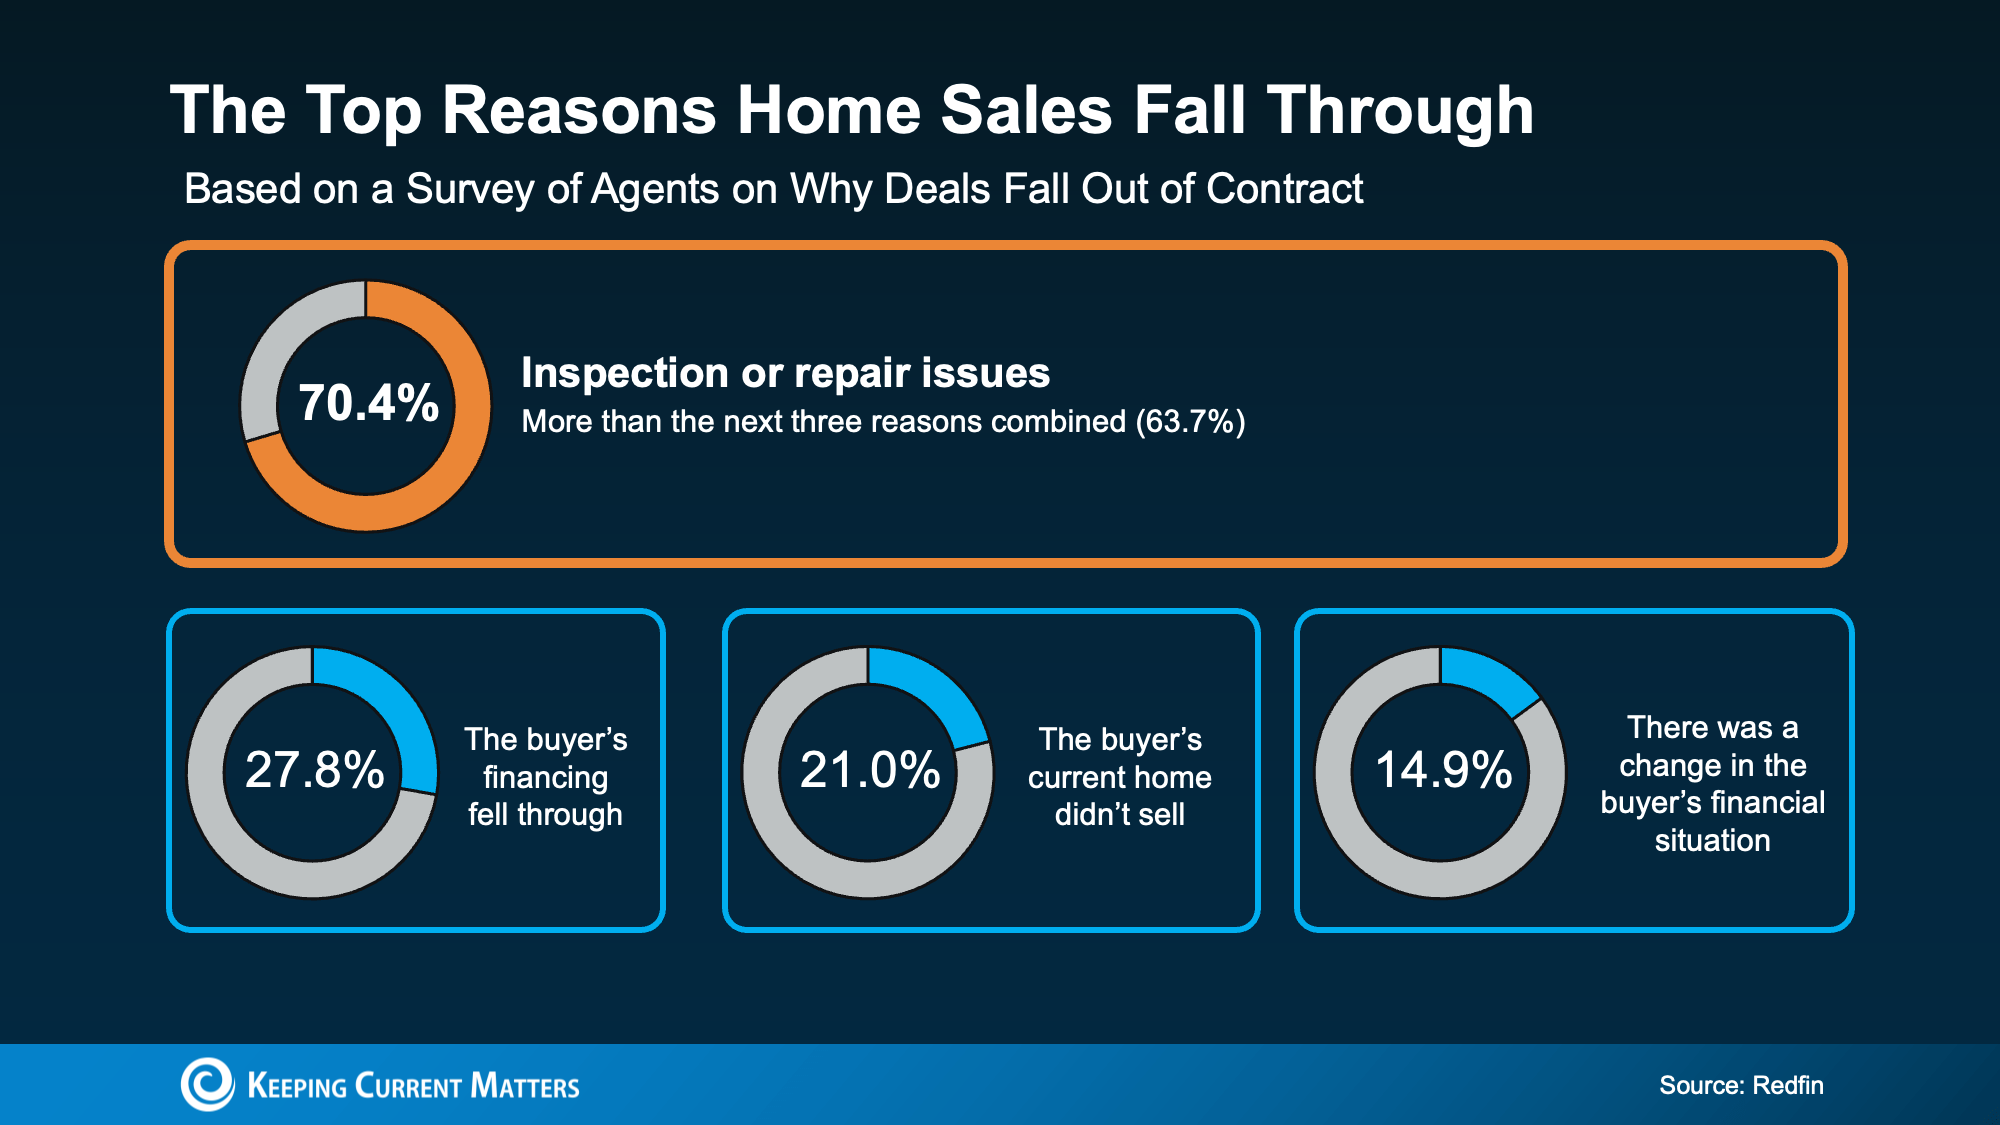
A Redfin survey sheds light on the most common things that trip up a sale (see visual below):

a blue and orange chart with text

Here’s a bit more information on each one.

  • Inspection or repair issues. This is the big one. When a buyer’s inspector finds a problem, whether with the roof, the plumbing, the foundation, or elsewhere, the buyer can push back, ask you to make repairs, request a credit so they can do it themselves, or see if you’ll lower your price. If they don’t get what they want, they may walk away from the deal altogether.

  • The buyer’s financing fell through. Their mortgage loan has to be fully approved in time for closing day. If the loan doesn’t come together, the sale can’t move forward. 

  • The buyer’s current house didn’t sell. Some buyers need to sell their own home before they can close on yours. If that takes longer than expected, you may run into some issues with your timeline or even see them give up on their move.

  • There was a change in buyer’s financial situation. A new job, a big purchase, or new debt can change what a buyer qualifies for on their mortgage loan, even after they were pre-approved.

Where Your Agent Makes the Difference

Some of those reasons are outside your control, like whether a buyer’s loan clears or whether they sell their own home in time. But according to Zillow, there are a few proactive things you can do to help make sure your sale goes as smoothly as possible:

  • Save yourself the headache and get a pre-listing inspection. That’s when you get your own inspection before a buyer gets theirs. It lets you find the big issues before a buyer’s inspector does, so you can fix them or disclose them on your terms, instead of scrambling once you’re under contract. In this situation, your agent will help you decide what’s worth addressing and what to just disclose. Handle it now, and the biggest risk to your sale is behind you before a buyer ever brings it up.

  • Look at more than just the offer price. Your agent will help you weigh the whole offer, including the buyer’s timeline and any contingencies attached. When a buyer’s offer depends on selling their own home first, the success of your sale rides on a second deal you can’t see. Sometimes, a slightly lower offer with fewer strings is the safer one. Your agent will help you weigh your options and make a plan that works well for you. 

One of those is something you can’t do until you have offers in hand, but the other is something you can get ahead of right now. The pre-listing inspection.

That relatively small cost upfront can save you the much bigger hassle of a deal falling apart later. And while getting your own inspection before listing may not make sense in every market, your agent can tell you whether it’s worth it based on your market, your house, and what buyers are prioritizing in your area.

Sometimes the smartest move is staying one step ahead.

Bottom Line

Most home sales still close, and the biggest thing that could get in the way of yours is the one thing you can actually do something about.

With the right prep, your sale has every reason to make it to the finish, and a good local agent can help you get there.


Source link