After more than a year of headlines talking about how home prices are going to crash, the latest data shows that price growth may be starting to pick back up again. And depending on whether you’re buying or selling, that shift means something different for you.
The Numbers May Be Starting To Turn
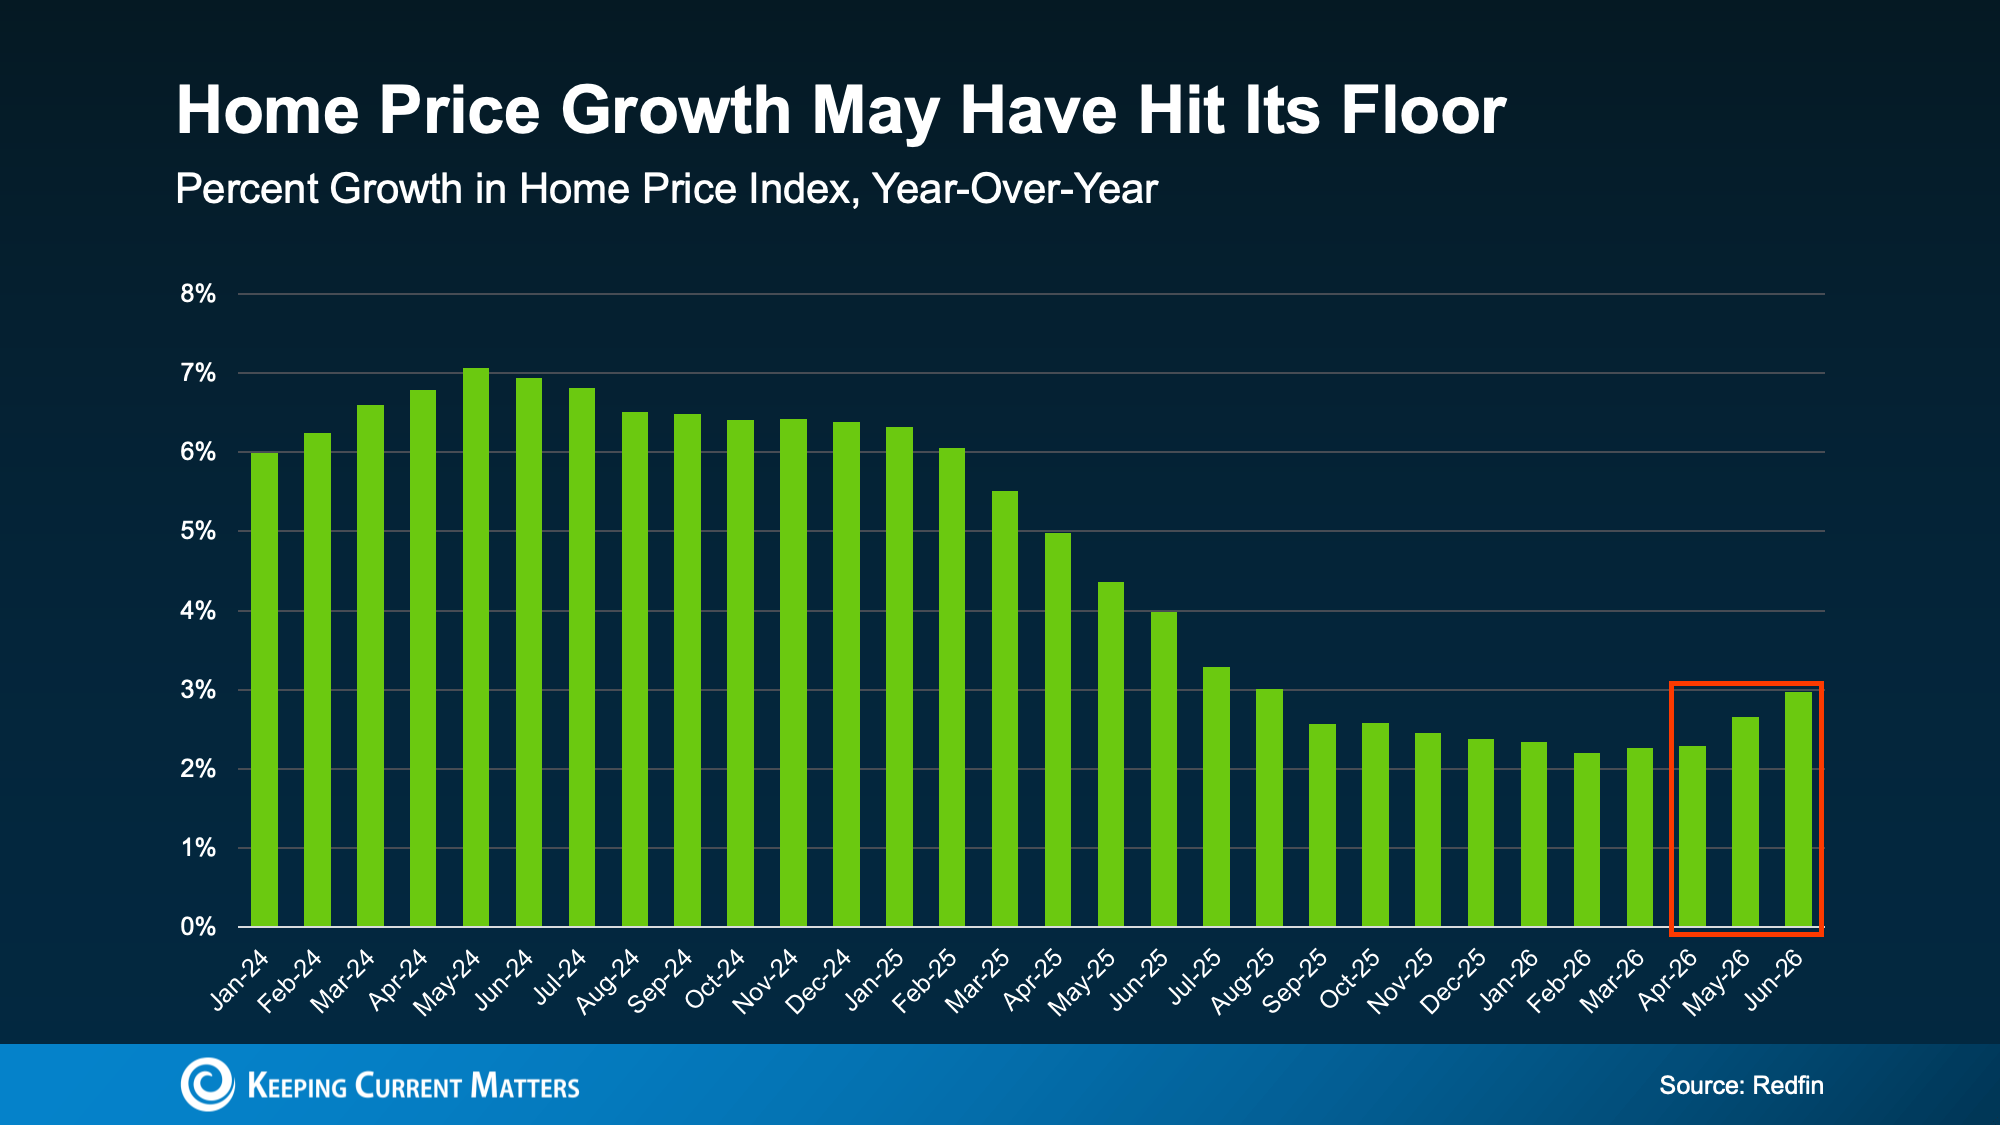
For the past couple of years, home price growth has been moderating – cooling from around 7% in mid-2024, according to Redfin (see graph below). But look at the right side of that graph. The pace of that growth appears to have hit its low point and started to turn.
While a couple months of data doesn’t necessarily mean this will be a lasting trend, there are some other signs that this could continue.
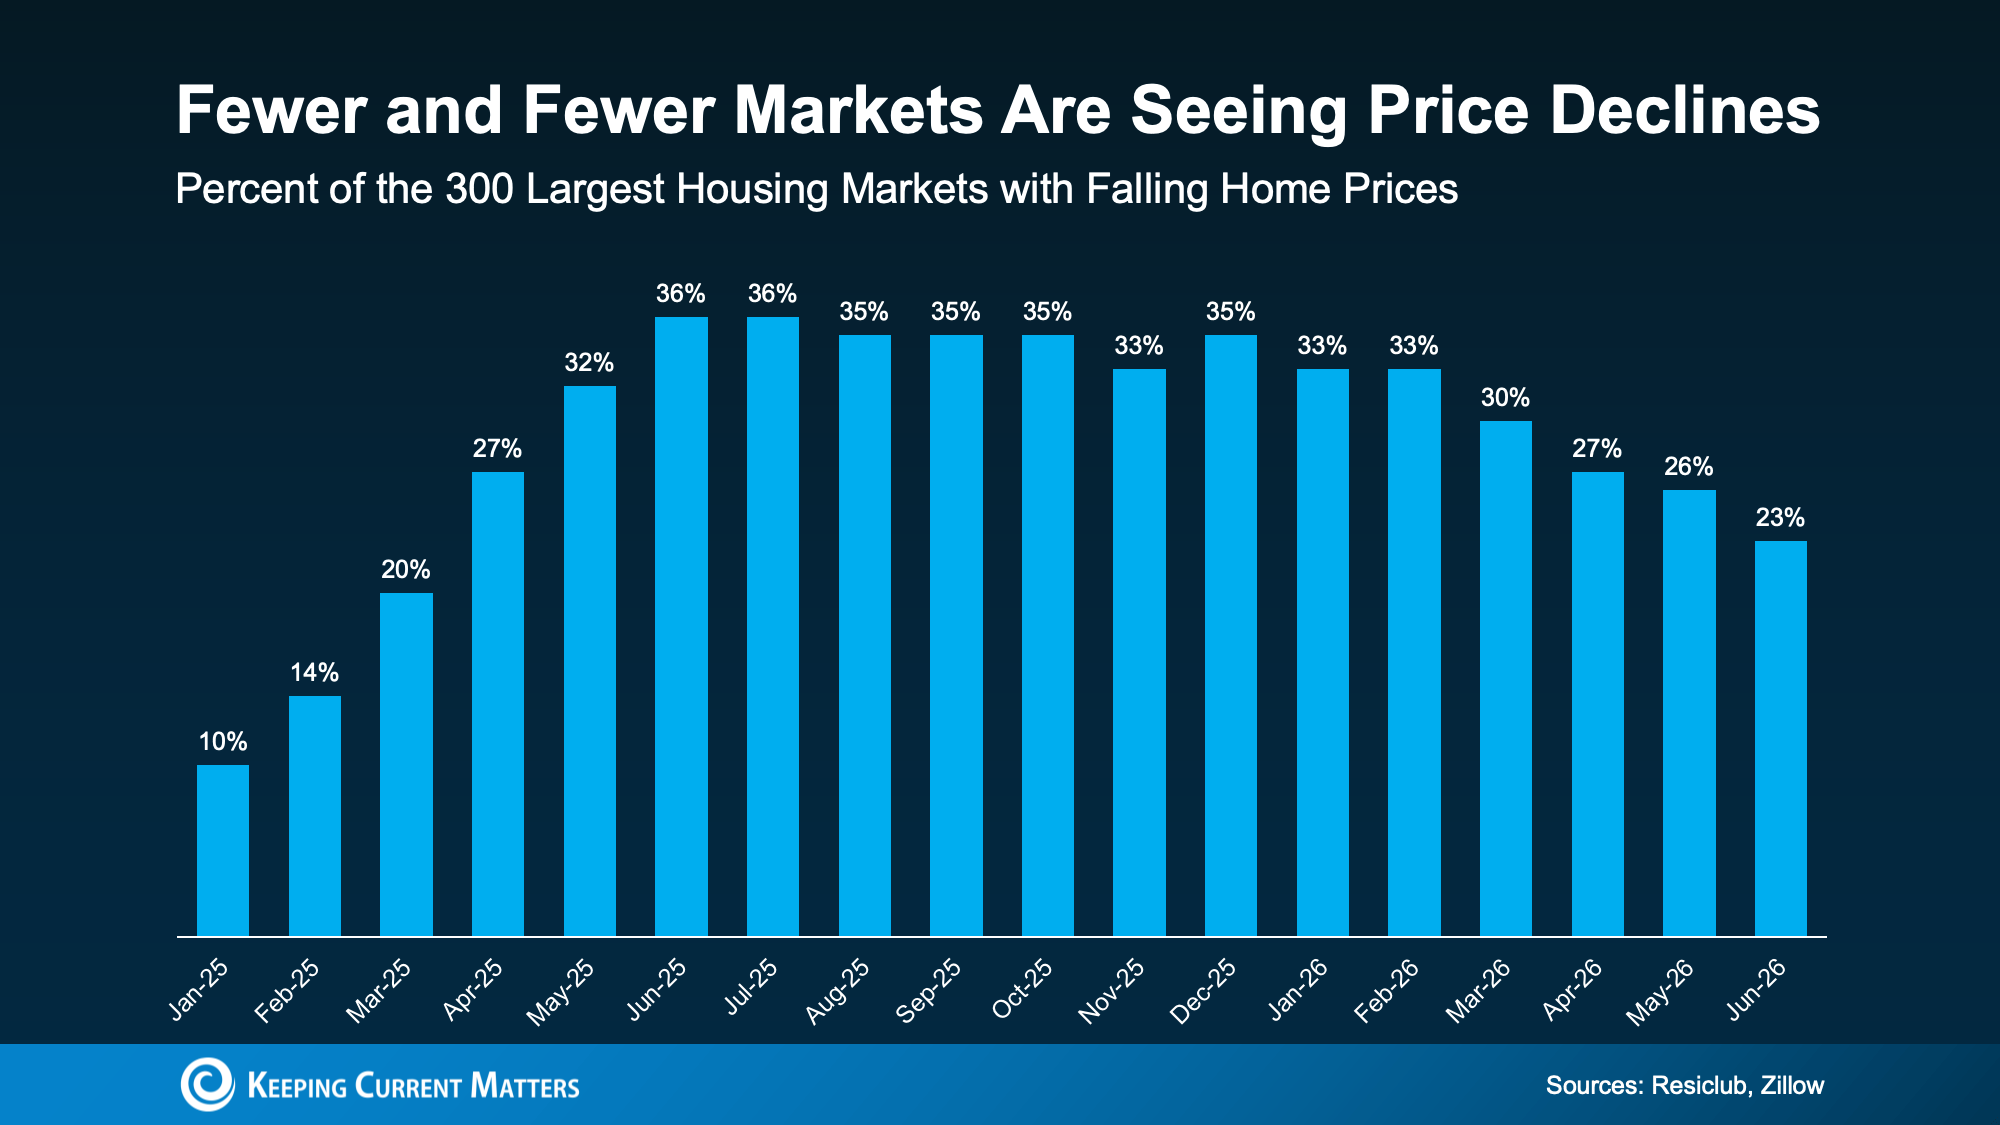
For example, fewer markets are seeing prices decline. According to ResiClub and Zillow, about 36% of the 300 largest housing markets had falling prices as of the middle of last year. Since the start of this year, that share has been shrinking. Now? Only 23% are experiencing those mild dips (see graph below):
When fewer markets see prices falling, that means more markets are seeing prices rise again.
And forecasts suggest this shift has room to run. On average, experts project home prices will rise about 2.3% nationally this year. And for that to happen, price growth would have to pick up a bit in the second half of 2026.
But Remember, Real Estate Is Local
While it looks like national prices may be starting to pick back up a tiny bit, that doesn’t mean that’s what’s happening in your neighborhood.
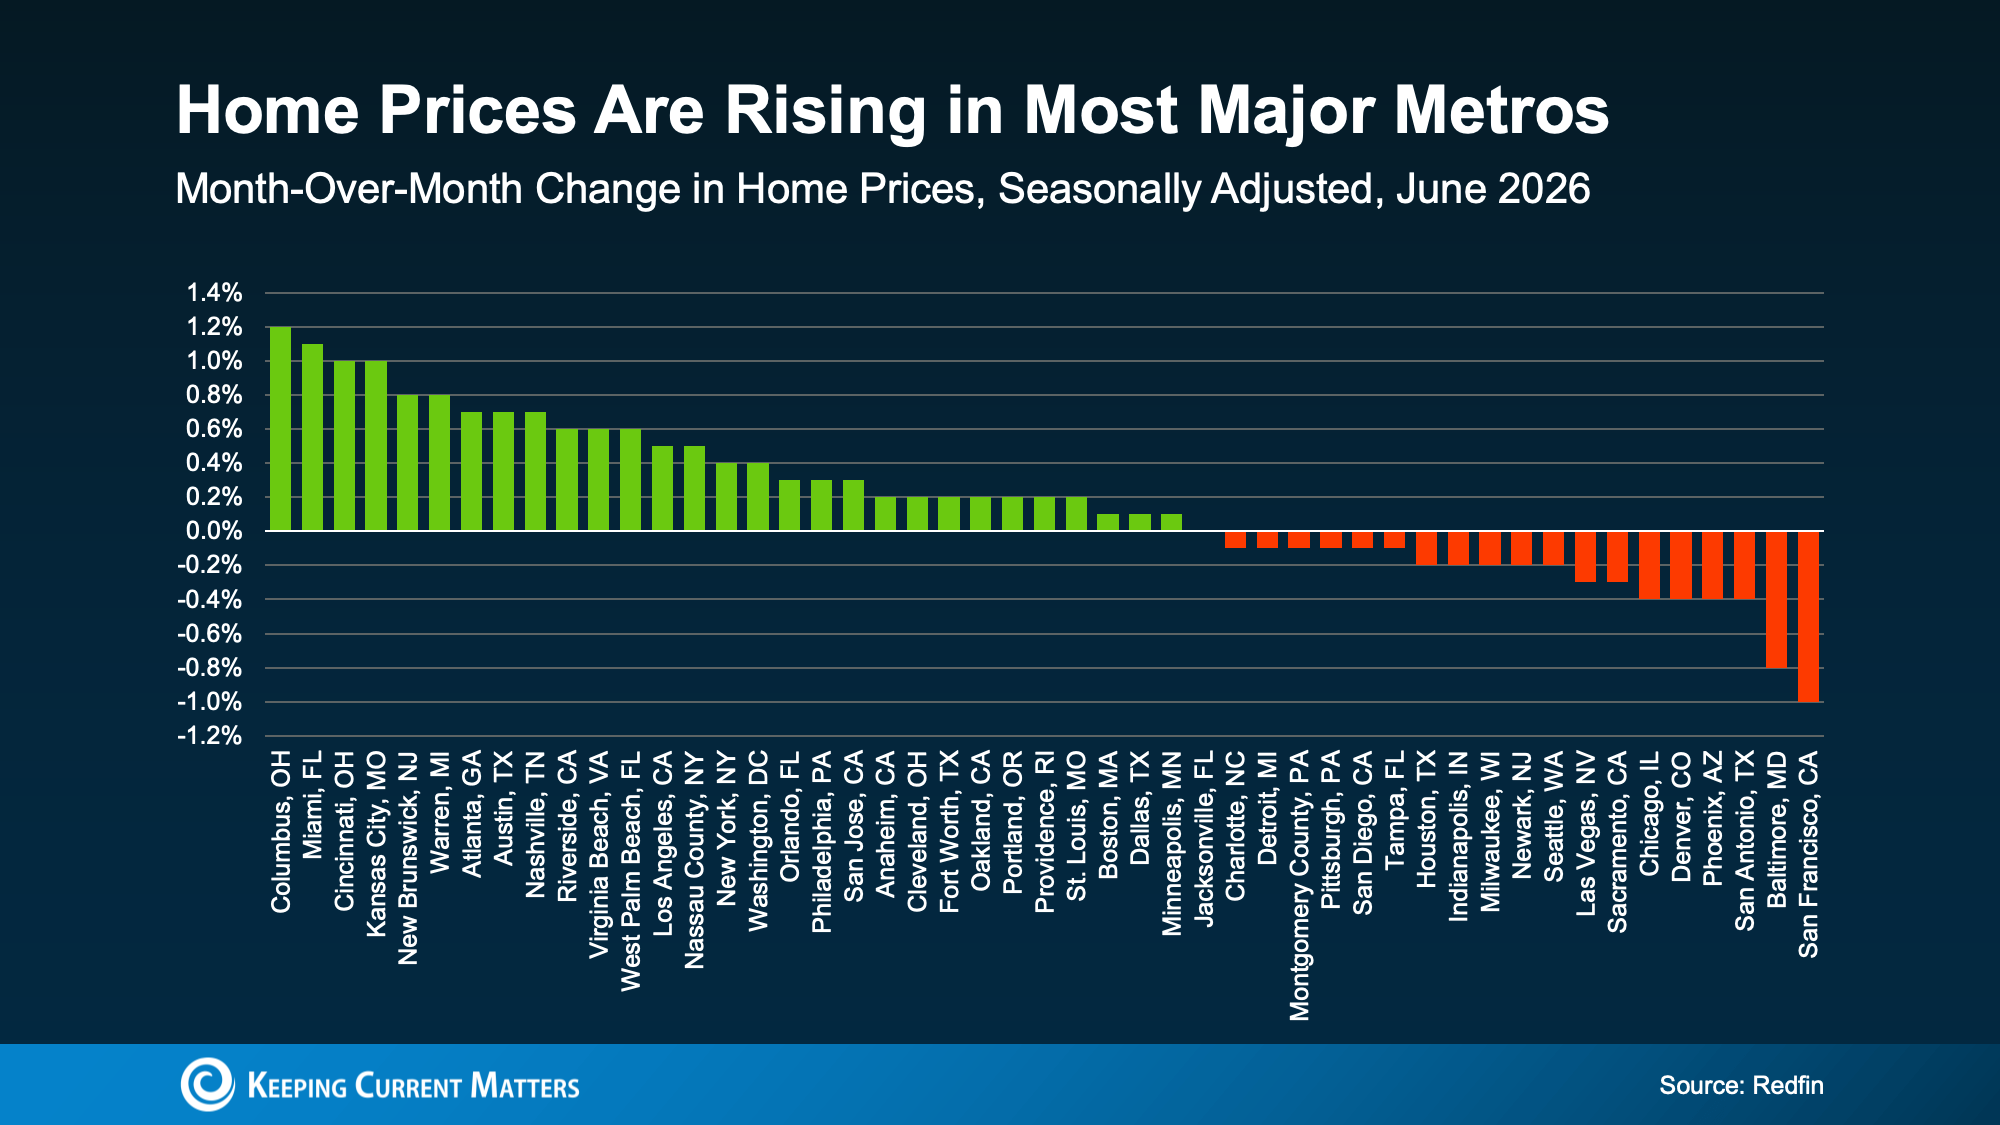
National home prices are really just an average of hundreds of local markets. Some are climbing faster. Others are still cooling. But one reason the national average may be looking up is because a growing number of metros may actually be net positive for prices this year.
Not long ago, the major metros were split about 50/50 – half seeing prices rise and half seeing them fall. Now, that balance looks like it’s starting to tip in a more positive direction. Just last month, more than half of the major metros saw prices go up, according to Redfin (see graph below):
As Selma Hepp, Chief Economist at Cotality, explains:
“. . . local markets continue to tell very different stories. Annual home price growth has changed little since the start of the year, but some markets, especially those supported by strong job and income growth in the West and more affordable Midwest markets, have seen notable acceleration in price gains.”
What This Means for You
Home price headlines can be confusing because they don’t always tell the full picture. Lean on an agent to understand what’s happening in your local market and what the early signs say for where prices may go from here.
That’s the best way to stay one step ahead of the market.
If you’re buying: slower price growth has worked in your favor. You’ve had more room to negotiate and a budget you could plan around. If price growth is picking up in your area, buying now may mean paying less than you would later this year.
If you own a home: you’ve been gaining equity all along, even while growth moderated. If growth keeps picking up, those gains could speed up, too. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), projects the typical homeowner will gain roughly $16,000 in housing wealth this year. And if you’re thinking about selling, this shift is a good early sign for you. Just remember, the market is still pretty balanced and buyer-friendly in a lot of areas right now.
Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, let’s connect so you can see exactly what prices are doing in our local market and what that means for your plans.
Bottom Line
Home price growth slowed way down, and now it’s showing early signs of picking back up. Whether you’re buying or selling, connect with a local real estate agent so you can see exactly what prices are doing in your local market and what that means for your plans.
If buying a home is on your radar, you’ve probably been keeping an eye on mortgage rates and home prices. But don’t forget about homeowners insurance.
Homeowners insurance has always been part of owning a home. But over the past few years, it’s become a larger expense for many homeowners – something that’s especially frustrating when affordability already feels tight.
The good news? While premiums are still rising, the latest data shows those increases are beginning to slow. Here’s what buyers should know.
Home Insurance Costs Have Gone Up
You’ve probably heard stories from friends or family about their premiums going up. And that’s not really a surprise when you consider data from the Pew Research Center shows 71% of homeowners say their insurance costs have gone up over the past few years.
While no one likes rising costs, knowing what to expect can help you plan ahead. Your first insurance payment is typically included in your closing costs, but after that it’ll become part of your monthly housing expenses.
Getting an insurance quote early can help you build a more realistic budget and avoid surprises later.
Premiums Are Rising, But Not as Fast as They Were
Most of the headlines focus on how home insurance is getting more expensive. And that’s true. But here’s the part that’s easy to miss.
Insurance premiums are still rising.
But they’re not rising as fast as they were.
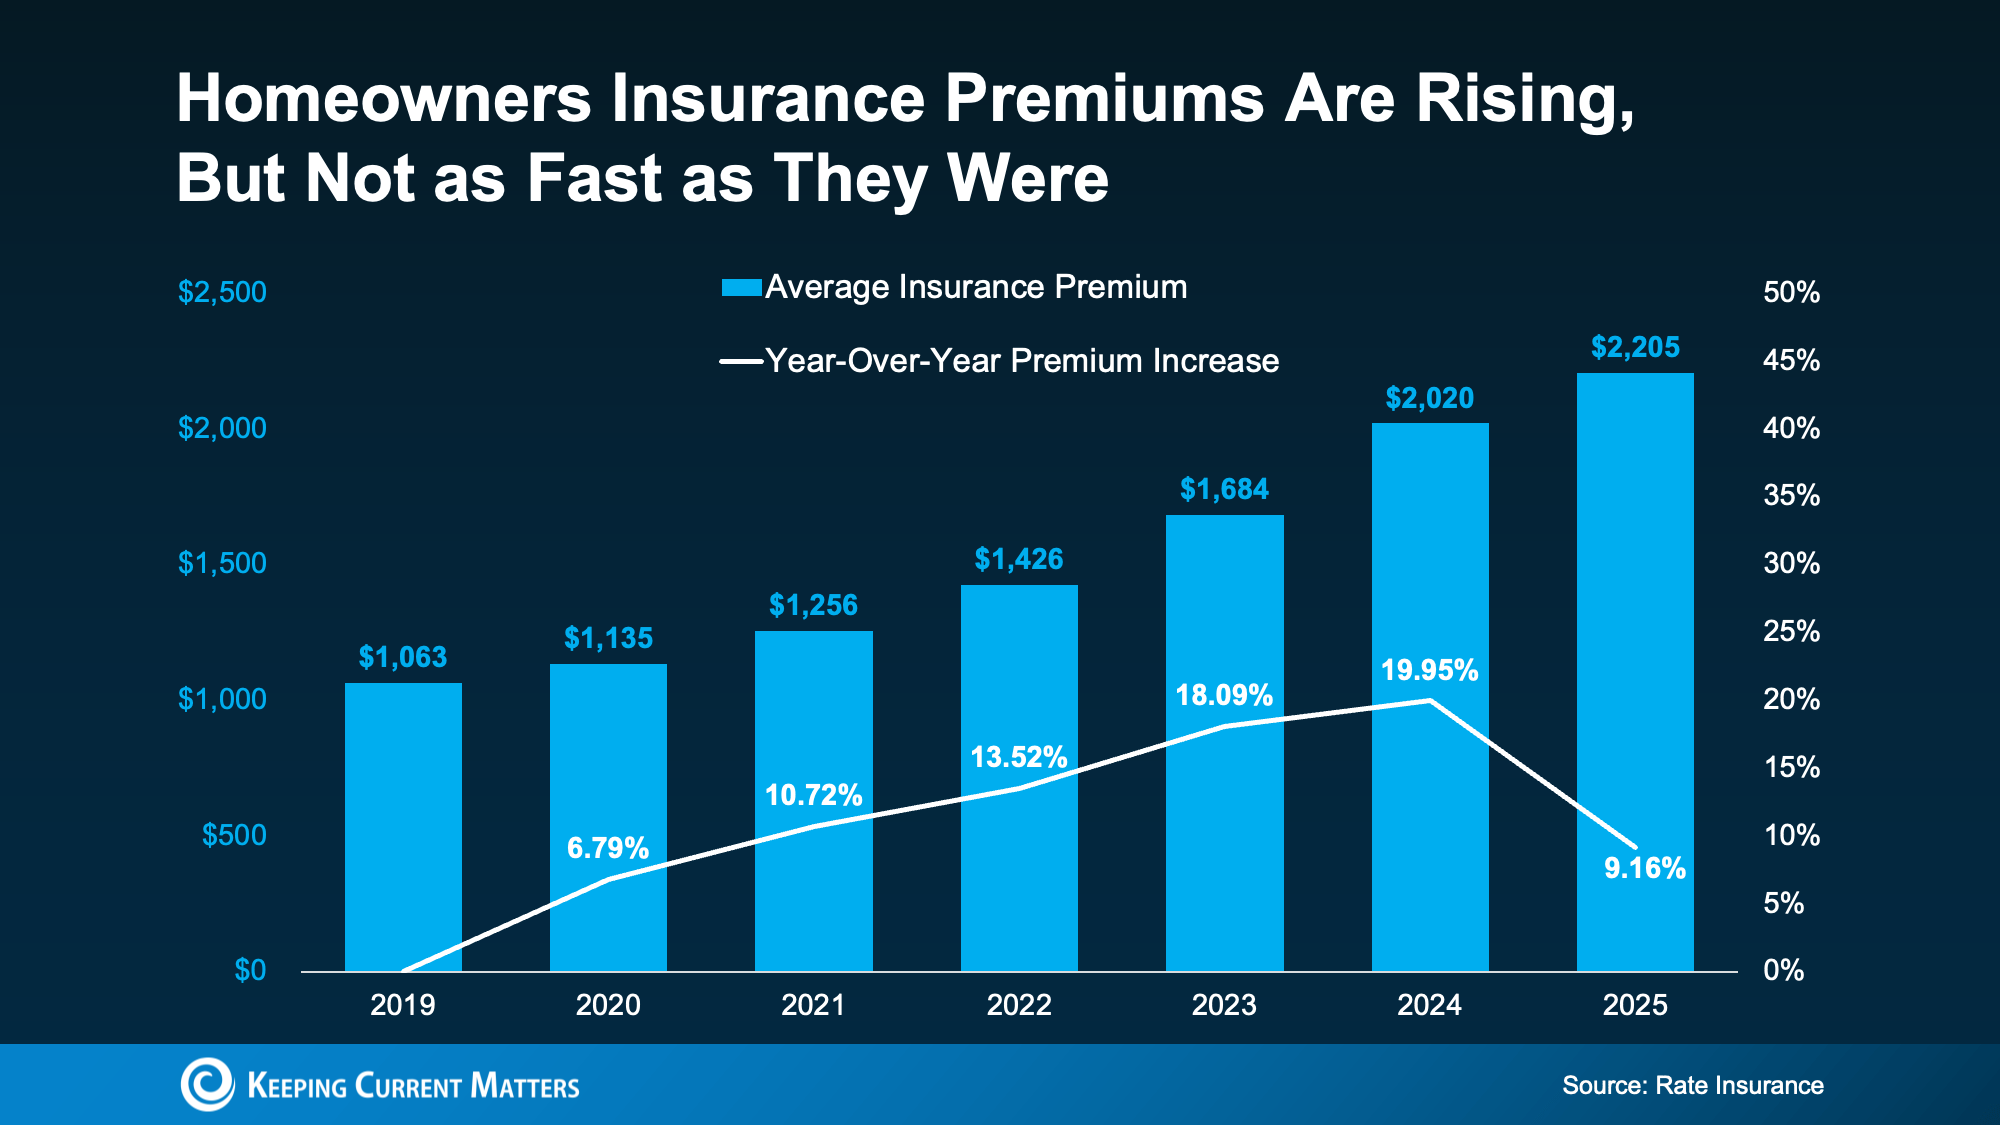
According to the latest report from Rate Insurance, 2025 saw the first slowdown in annual premium increases since 2019 (see graph below):
That doesn’t mean premiums are getting cheaper. It simply means the rapid increases of the past several years may finally be starting to ease – a small but welcome step in the right direction.
But what you’ll pay in one part of the country can look very different from what someone pays somewhere else.
Where You Buy Can Make a Big Difference
Insurance costs vary because some parts of the country experience more claims than others. That’s why it’s important to look at what’s happening locally.
Your premium will depend on things like where you’re buying, the home itself, and the coverage you choose.
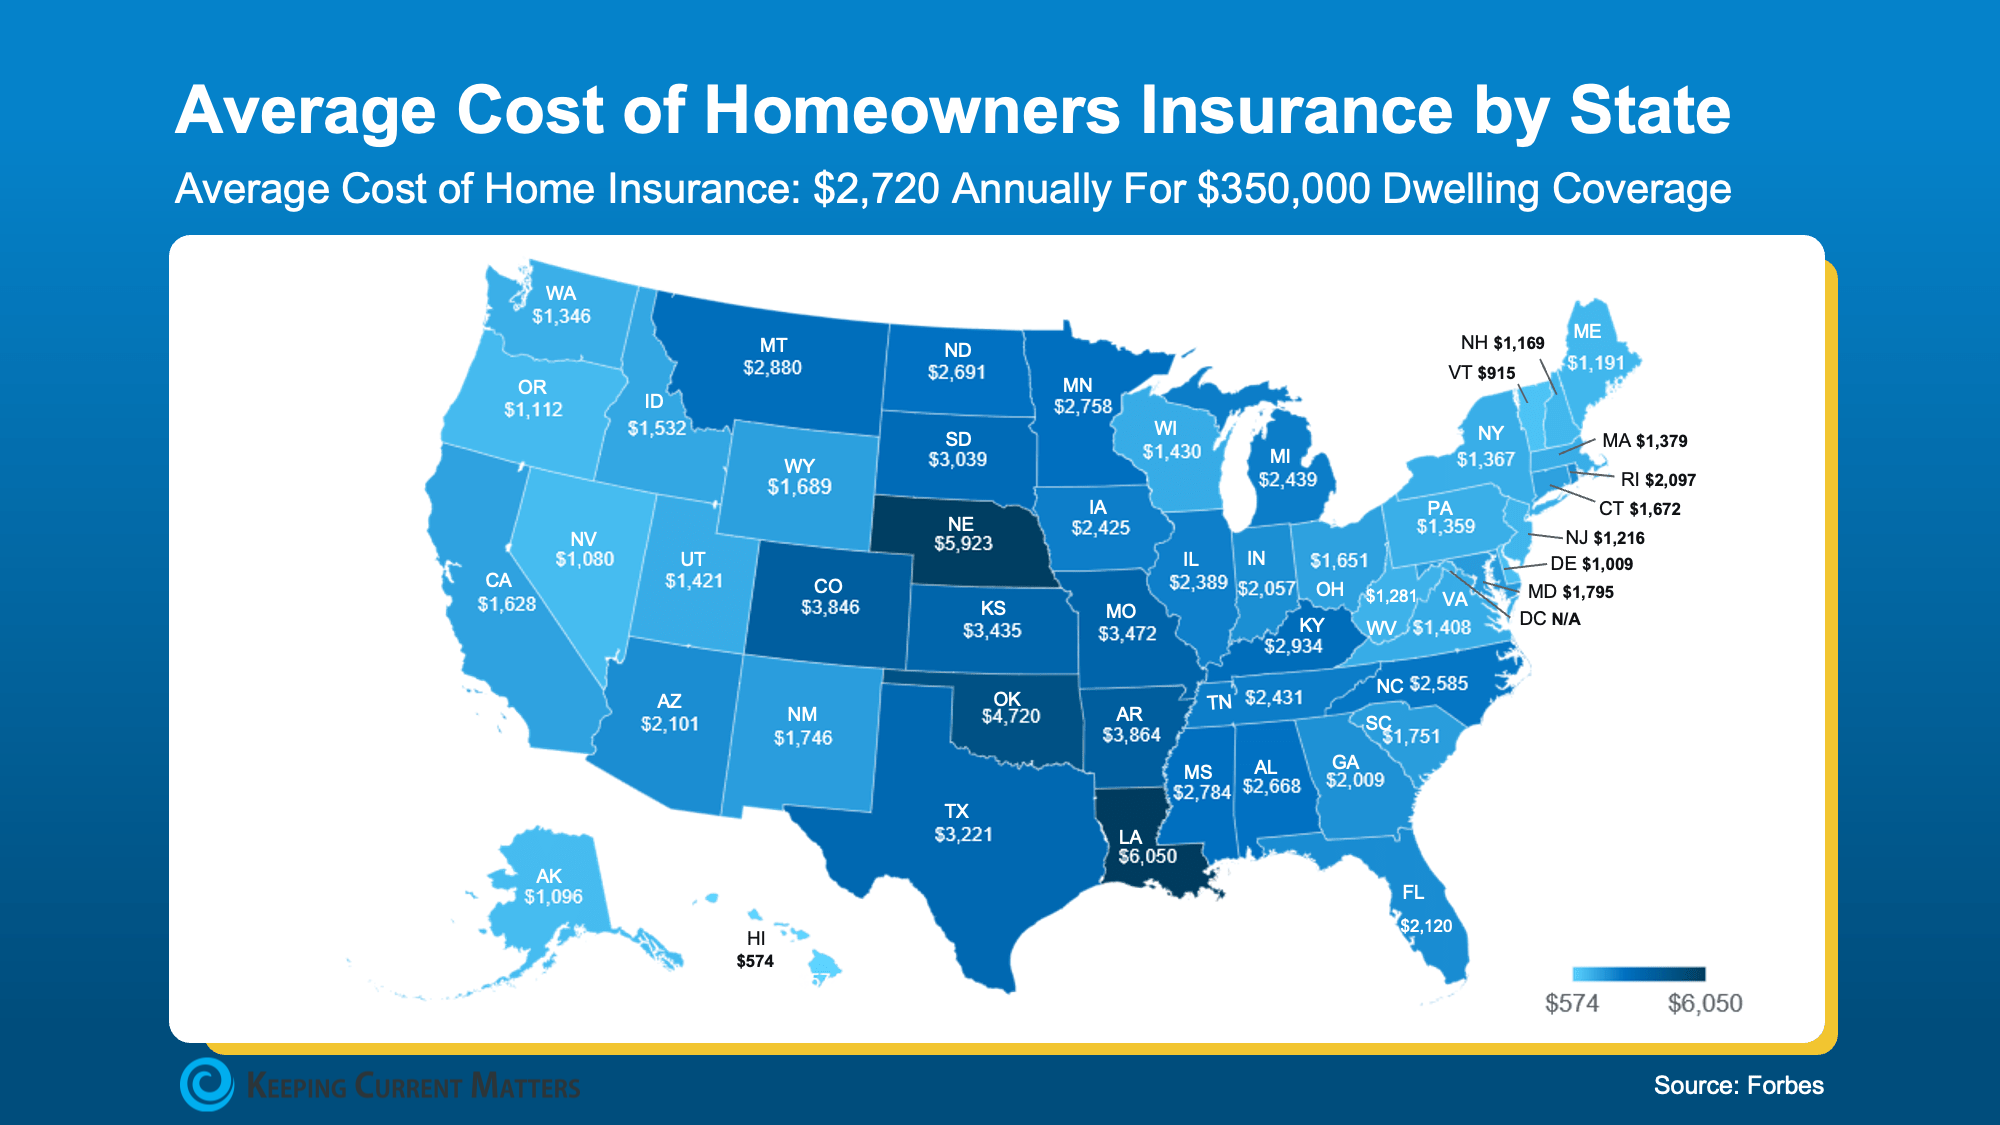
Forbesdata can give a rough idea of your state’s typical premiums. Check out the map below – the darker the blue, the higher the costs tend to be in that state:
Ways To Lower Your Costs
While you can’t control every cost that comes with buying a home, you can control how prepared you are. If you’re crunching the numbers and trying to find ways to save, Insurify and NerdWallet offer these tips that can help you get the best insurance price possible:
Shop Around – Compare quotes from multiple companies.
Bundle Policies – Combine home and auto to see if a bundle price is cheaper.
Ask If There Are Discounts – Don’t miss out on savings you may qualify for.
Highlight Upgrades – Features like a new roof or storm windows can cut costs.
Improve Your Credit – A stronger credit score can mean better premiums.
One of the smartest things you can do is get an insurance quote before you make an offer. That way, you’ll know what your monthly housing costs are likely to be before you commit.
An insurance professional can walk you through your options and help you find coverage that fits both your needs and your budget.
Bottom Line
Homeowners insurance has become a bigger part of the homebuying conversation. But it doesn’t have to become a bigger source of stress.
The key is knowing what to expect before you buy. Get an insurance quote early, factor it into your budget, and lean on trusted local professionals to help you make the most informed decision possible.
I’m a rent-stabilized tenant. My building recently installed a new fire escape, requiring me to remove my window air conditioning unit. Meanwhile, all the newly renovated units in the building have central air. What am I entitled to? Does the landlord have a responsibility to provide AC in some other way?
This summer’s extreme heat serves as a reminder to all New Yorkers that air conditioning is not just an issue of comfort, but one of health and safety at its most fundamental level. NYC passed new legislation that will require landlords to provide AC, however the law will not be enforced until 2030.
Still, there may be some instances in which your landlord can be required to come up with a solution for your AC right now.
“If your apartment came with the air conditioning unit when you moved in, or if the lease explicitly guarantees it, then the landlord has to provide AC,” Altagracia Pierre-Outerbridge, attorney and founder of Outerbridge Law representing residential tenants, condo owners and landlords, said. “But, if you brought the AC unit, it might be a bit harder to force your landlord’s hand.”
Here’s how it works: Rent-stabilized tenants are entitled to any amenities that were provided to them upon move-in, whether that’s air conditioning, an elevator, or an intercom system. “Rent-stabilized tenants can file a complaint with the Division of Housing and Community Renewal (DHCR) if their landlord refuses to return the amenity to its original condition,” Pierre-Outerbridge said. “DCHR would be able to formally compel the landlord to reinstate service, or provide a rent reduction.”
All tenants regardless of stabilization are entitled to air conditioning if provided by the lease terms. “The landlord would be in clear breach of contract if air conditioning is part of the lease terms but they’re preventing you from installing it,” Pierre-Outerbridge said.
New law to the rescue?
A new NYC law may offer some recourse if your lease doesn’t guarantee air conditioning.
“Starting in 2030, landlords will be required to provide air conditioning to tenants that request it,” Pierre-Outerbridge said. “This law was meant to fill in the gaps, so if you’re one of 90 percent of NYC households that already have air conditioning, not much will change for you. But New Yorkers without air conditioning will finally have a legal bolster protecting them from extreme heat exposure in their homes.”
Pierre-Outerbridge gave a glimpse at how this could play out if taken to court. “Prior to this, your best option would have been to argue that not being able to install an AC unit breaches the warranty of habitability,” Pierre-Outerbridge said. “It’s not a surefire argument, you’d have to be prepared for your landlord to argue that the roughly 10 percent of NYC households without air conditioning aren’t taking issue with habitability.”
“But if it’s not included in the lease terms, your argument for habitability may have gotten stronger,” Pierre-Outerbridge said. “Though enforcement won’t begin until 2030, you have a law on your side that mandates AC for all. A lawyer can help you position this new law as leverage if you need to make a case legally.”
Steps you can take
A portable unit may offer you temporary reprieve, but it may not be enough, especially during a heatwave.
“Don’t be a martyr for your cause,” Pierre-Outerbridge said. “Find a way to keep your apartment cool, whether that’s with fans or a portable unit, but remain persistent with your landlord to find a permanent solution that guarantees AC. This new law’s delayed enforcement will make it hard for tenants alone to demonstrate that landlords need to provide air conditioning immediately, but an experienced lawyer can help you maneuver the law and the legal system to bring you relief.”
Pierre-Outerbridge said it will be interesting to see how landlords contend with the new AC law. “I’d wager that most landlords will give their tenants window units once enforcement begins,” she said.
However, since other tenants in your building have central air, your landlord may upgrade your unit too, she said. Wall-mounted mini split units are a typical choice for rental apartments.
Altagracia Pierre-Outerbridge, Esq. is the owner of Outerbridge Law P.C, focusing primarily on tenant representation. The firm represents all sides in landlord-tenant litigation and transactional matters such as month-to-month holdovers, nuisance cases, licensee cases, harassment claims, repair cases, tenant buyouts, succession claims, DHCR overcharges and rent reductions and more. Pierre-Outerbridge has 15 years of experience litigating in Supreme, DHCR, and Housing Court. To submit a question for this column, click here. To contact Outerbridge Law P.C. directly, call 212-364-5612 or 877-OUTERBRIDGE, or schedule a meeting today.
For countless budget-conscious renters in New York City, temporary walls have long offered a way to subdivide an apartment and create an additional bedroom to split the rent with a roommate. After all, it can be hard to meet the stringent income requirements that landlords have for living here if you’re shouldering the rent alone.
These nifty partitions also allow you to avoid having to find a larger apartment when baby makes three—or if you work from home and need a designated office space.
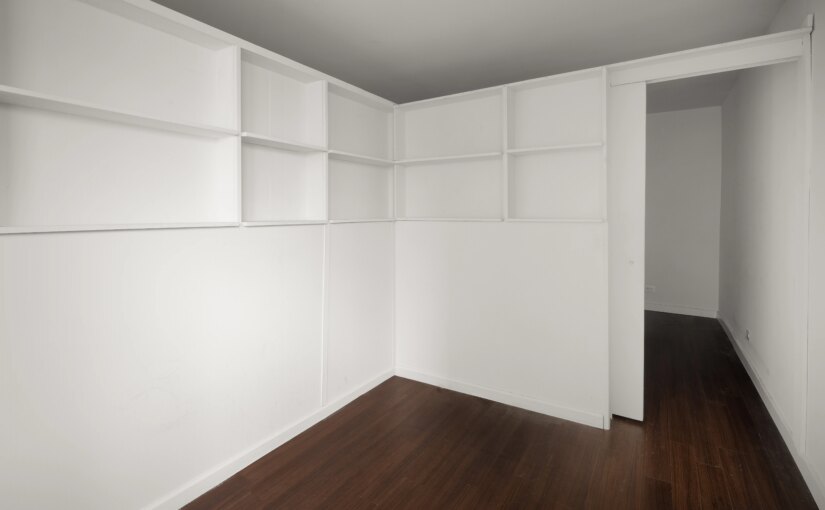
Although pressurized temporary wallsoffer greater privacy, they are not permitted in many NYC rental buildings. On the other hand, freestanding bookshelf-style walls that are not permanently attached to the ceiling, walls, or even the floor can be an acceptable alternative. They are also more popular and customizable than ever.
[Editor’s note: An earlier version of this article was published in July 2025.We are presenting it again with updated information for July 2026.]
How do bookshelf walls make renting affordable?
Moving, even two blocks away (or two floors up), can cost a small fortune in NYC. There’s usually a security deposit on top of the first month’s rent, plus the cost of a moving company if you don’t plan on doing the schlepping yourself.
That’s why temporary bookshelf walls can help you avoid being priced out of your current or target apartment. Even basic models will allow you to carve out more space from your existing square footage, whether that means splitting a bedroom or sectioning off part of the living room (such as for a nursery).
And in addition to at least some semblance of privacy, bookshelf walls offer something else NYC renters are forever short on: vertical storage that doesn’t swallow your floor plan.
What kind of approvals do you need for bookshelf walls?
It helps to know the potential pitfalls of using this type of room divider. Even well-established management companies can be confused by what constitutes a temporary wall that will pass muster with the Department of Buildings. Pressurized walls may require permitting, and landlords can be reluctant to go through the process—and being compliant with the DOB is of the utmost concern.
That’s because dividing apartments with pressurized walls to create illegal bedrooms—rooms that are too small, lack windows, and have only one means of egress, for example—has led to tragic consequences in the past. (There are, however, ways to install a pressurized wall safely. For information, check out Brick’s “From 1 room to 2: The insider’s guide to temporary pressurized walls.”)
According to Adam Stone, a real estate attorney at The Stone Law Firm who also manages rental buildings through Stone Realty Management, “assuming they are truly freestanding, bookshelf walls are not actually walls but rather bookcases used to divide space, and you do not need permission from a management company to furnish your apartment.”
Even though bookshelf walls are technically furniture, you should always check with your building’s property manager to see if they are allowed.
Pro Tip:
If you exhaust the DIY method—or just feel exhausted—sign up here to take advantage of the corporate relocation rate offered by Brick Underground partner The Agency. A tech-savvy real estate brokerage founded by a pair of Yale grads in response to the frustrating apartment searches of classmates and colleagues, The Agency will charge a broker’s fee of 10 percent of a year’s rent versus the usual 12 to 15 percent if the apartment is an “open” listing (versus an “exclusive” listing where the fee is split with the broker holding the listing.) Bonus: The agents at The Agency are a delight to deal with.
What kinds of bookshelf walls are allowed in NYC?
Based on responses from the management companies contacted by Brick Underground, the requirements can run the gamut, and approval is often decided on a case-by-case basis.
Among those who typically allow bookshelf walls, for example, most require 12 inches of clearance below the ceiling and 36 inches between the partition and a permanent wall; if doors are permitted, sliding or pocket doors are often the only allowable options.
“I’d say 75 percent of buildings do not allow any door, just an opening,” said Eddie Sapienza, owner of Wall 2 Wall NY, named Best of New York 2019 in its category by New York Magazine.
It’s important to speak to your landlord before contacting a wall company. However, Sapienza said he has worked with many NYC management companies and has a “general understanding of what is and is not allowed at their buildings, though the landscape changes all the time.” And if he doesn’t know a landlord, he makes sure to send over the specs before constructing anything; in at least a few instances, the landlord has required Sapienza to build a model before approving the installation.
Such are the vagaries of NYC rentals—better to be safe than spend money on something that won’t be allowed. Ask the property manager before signing a new lease and before installing a bookshelf wall in your existing apartment. Preserving the landlord-tenant relationship is always the best course of action.
How much does a bookshelf wall cost?
Once you know the landlord’s parameters, you can begin exploring the different options. Prices range from $1,000 to $1,500 for basic models—by far the most popular and economical choice—and exceed $2,000 for custom configurations.
Like all things related to construction, the cost of materials fluctuates—and by a lot, Sapienza said. “We are still trying to keep it within $1,200 to $1,300 for a basic wall, plus more for doors, plexiglass, closet, and other additions.”
If your building allows you to add doors, consider using sliding or pocket doors so you can place furniture against the bookshelf on either side. Same for the “floating” door with special hinges offered by Wall 2 Wall, which Sapienza created for the most conservative buildings, where nothing is allowed above or below a door within the 36-inch clearance, rather than a transom. (Note that the higher cost of the special door hinges makes this option more expensive now, too.) Bi-fold doors require a 20-inch clearance, swing doors need 36 inches.
Be sure to ask about any fee to remove the bookshelf wall; most wall companies will do this free of charge within a specified period, usually two to three years. After that, you will need to remove it yourself.
Read on for Brick Underground’s roundup of bookshelf walls for NYC apartments.
Wall 2 Wall only makes open-shelving walls (with optional closets or doors) that are 12 inches deep.
“Even tenants who initially balk at the depth and shelving end up thanking me, saying how much they appreciate having all that extra storage, and vertical storage at that,” Sapienza said. “We can also make pretty much anything anyone wants and can afford, completely out of wood.”
For example, the unit shown above has double French doors flanked by bookshelves on either side and costs around $1,980.
If your landlord does not allow doors, see about getting approval for Wall 2 Wall’s freestanding bookcase with a floating door that pulls from behind and has nothing above or below it. This typically runs upward of $2,000, given the higher cost of the special hinges right now, but it might be worth it for the added privacy.
Removal is free during the contract, provided at least 30-days’ notice is given.
1DayWall started in 2013 doing interior remodeling and renovations, transitioning full-time to temporary wall installations in 2019. Installations range from $1,100 to $3,500.
The standard wall is 4.75 inches thick; a three-inch-thick wall, which is helpful in especially tight spaces, is available upon request. Factory-style glass windows can be built into the installation and are one of the features that set their walls apart.
The company’s bookcase walls come with shelves and optional doors in many styles, including a standard door with a lock. The sliding-door version, shown above, costs around $1,200 for a 12-foot wall.
Removal is available for a one-time fee of $350 plus tax. Payment is by certified check only.
If you are particular about matching the color of the partition to your apartment walls, Manhattan Pressurized Walls lets you choose between Benjamin Moore White or any other custom color or finish for an additional price.
The cost for a straight divider with shelves and a sliding door, such as the one shown above, starts at approximately $1,495. An L-shaped divider with shelves and a sliding door (shown at the top) begins at roughly $1,850, including tax.
Removal is free with four-weeks’ notice as per the contract; otherwise, a $420 removal fee applies.
The company’s Bookcase Partition comes in two basic options: a 12-inch-deep wall with shelving or six-inch-deep units when storage isn’t required. Options include different door types, closet rods, and a wardrobe with a sliding mirror front (shown above).
The system can be modified to meet the room’s requirements. You can even have two units stand back-to-back, with different shelving or other components facing each side (as in this entertainment center). The bottom portion is typically left open to free up floor space, though that’s up to you.
Removal is free of charge within three years of purchase.
Pricing for the company’s “freestanding walls” starts at $1,800 and can be customized to match your needs and room dimensions. They will inspect the space and help you develop a solution that fits the footprint. AllWeekWalls now also offers removable plexiglass tops for buildings with strict rules—and is the only company to offer this service, according to a company representative. The unit above, for example, costs $4,500.
Installation takes a few hours. You can paint or otherwise finish the wall as you like.
The real estate market continues to evolve as economic conditions, technology and buyer behavior shift rapidly. Whether you are purchasing your first home, selling property or building an investment portfolio, understanding the best real estate tips can significantly improve your results.
In 2026, success in real estate is no longer based purely on location. It requires strategy, data awareness, financial discipline and market timing. This comprehensive guide outlines actionable real estate tips to help buyers, sellers and investors make informed decisions.
1. Understand Local Market Conditions Before Making Decisions
One of the most important real estate tips is to study your local market carefully. National headlines do not always reflect neighborhood level trends. Property values, rental demand and buyer competition can vary dramatically between cities and even within districts.
Before buying or selling, analyze:
Recent comparable sales
Average days on market
Inventory levels
Mortgage rate trends
Future development plans in the area
Working with a knowledgeable local real estate agent can provide valuable insight into pricing strategy and negotiation opportunities.
2. Get Pre Approved Before House Hunting
For buyers, financial preparation is essential. Pre approval from a lender not only clarifies your budget but also strengthens your position in competitive markets.
Sellers prefer buyers who demonstrate financial readiness. A pre approval letter signals seriousness and reduces the risk of financing delays. Additionally, understanding your borrowing capacity helps you avoid emotional overspending.
Smart buyers also factor in hidden costs such as property taxes, maintenance, insurance and closing fees.
3. Focus on Long Term Value, Not Short Term Trends
Modern real estate markets are influenced by design trends, social media exposure and short term hype. However, successful investors and homeowners focus on long term value.
Properties in areas with strong infrastructure, good schools, transportation access and economic growth tend to appreciate more consistently. Even if a property requires minor upgrades, location quality often outweighs cosmetic appeal.
When evaluating real estate investments, ask:
Is the neighborhood growing or declining
Are new businesses and developments planned
Does the property meet long term lifestyle needs
Strategic thinking protects you from market volatility.
4. Use Technology to Gain Competitive Advantage
Digital transformation has changed how people search, evaluate and purchase property. Buyers now rely heavily on online listings, virtual tours and neighborhood data.
Sellers should invest in:
High quality photography
Video walkthroughs
Accurate property descriptions
Professional staging
Online presentation directly impacts perceived value. In competitive markets, strong digital marketing can significantly shorten selling time.
Investors can also leverage property analysis tools, rental yield calculators and market forecasting platforms to make data driven decisions.
5. Negotiate Strategically, Not Emotionally
Real estate transactions often involve large financial commitments, making emotions difficult to manage. However, strategic negotiation is critical.
For buyers:
Avoid revealing excessive enthusiasm
Request inspection contingencies
Compare multiple options before committing
For sellers:
Price competitively based on market data
Be prepared for counteroffers
Consider overall offer strength, not just price
Successful negotiation balances assertiveness with flexibility.
6. Diversify Real Estate Investments
For investors, diversification reduces risk exposure. Instead of concentrating capital in a single property type, consider exploring:
Residential rental properties
Short term vacation rentals
Commercial real estate
Real estate investment trusts
Each category offers different risk and return profiles. Diversification helps protect against economic downturns affecting specific sectors.
In 2026, emerging markets and secondary cities are gaining attention due to affordability and population growth. Investors willing to research beyond major metropolitan areas may uncover strong opportunities.
7. Prioritize Property Inspections and Due Diligence
Skipping inspections to secure a deal can result in costly mistakes. Structural issues, plumbing defects and electrical problems may not be visible during initial viewings.
Professional inspections protect buyers from unexpected expenses. Sellers who address maintenance issues before listing may also improve property value and buyer confidence.
Due diligence should include:
Reviewing property history
Verifying zoning regulations
Understanding homeowners association rules
Evaluating environmental risks
Comprehensive evaluation reduces legal and financial surprises.
8. Improve Curb Appeal for Higher Selling Value
First impressions strongly influence buyer perception. Simple improvements such as landscaping, exterior painting and lighting upgrades can increase perceived value.
Interior enhancements such as decluttering, neutral color schemes and minor repairs can also improve presentation. Buyers are more likely to make competitive offers on well maintained properties.
Cost effective improvements often generate strong returns when strategically executed.
9. Monitor Interest Rates and Economic Indicators
Mortgage rates significantly impact affordability and demand. Rising interest rates may reduce buyer activity, while lower rates typically increase competition.
Understanding economic indicators such as employment growth, inflation and government housing policies can help predict market movement. Timing transactions strategically can influence profitability.
Real estate success often depends on awareness of broader financial conditions.
10. Think Beyond Buying and Selling
Real estate can serve multiple purposes beyond homeownership. It can provide rental income, tax advantages and portfolio diversification.
Long term investors benefit from:
Rental cash flow
Property appreciation
Equity building
Inflation protection
By viewing property as part of a broader financial strategy, individuals can build sustainable wealth over time.
Final Thoughts
The best real estate tips in 2026 emphasize preparation, research and strategic thinking. Whether you are buying your first home, selling for profit or expanding an investment portfolio, success depends on informed decisions rather than impulse actions.
Market conditions may fluctuate, but strong fundamentals remain constant. Location quality, financial discipline, data driven analysis and professional guidance continue to shape successful outcomes.
Real estate remains one of the most powerful tools for wealth building and long term financial security. With careful planning and the right strategies, you can navigate the property market with confidence and clarity.
Michael Dell, the founder of Dell Technologies Inc., shared his company’s quarterly earnings report dated July 31, 1984, saying, “This one page changed my life.” The billionaire said on his X post that the numbers on that piece of paper convinced his parents that they didn’t need to go back to college. He started the company in 1984, originally known as PC’s Limited, in his dorm room at the University of Texas at Austin, upgrading PCs and building clones of IBM PCs from stock parts.
Go deeper with TH Premium: AI and data centers
(Image credit: Microsoft)
As we see from his X post below, his venture seemed to be successful from the get-go, with Dell selling almost a million dollars’ worth of parts and computers, which resulted in a net income of $134,762.75 for just one quarter — equal to $433,150.05 in 2026 dollars. This is an achievement for any startup not backed by millions of dollars, much less by a 19-year-old college freshman backed by just $1,000, with the investment returning 13,500% in less than a year.
Dell went public four years after it was founded, but after a quarter of a century of being listed on the stock market, Michael Dell and Silver Lake Partners decided to take the company private again in 2013 in a $24.9 billion deal as it struggled with the rise of smartphones and tablets. After five years without mandatory quarterly reports, Dell decided to go public again, and it currently has a market capitalization of around $261.92 billion.
Latest Videos FromTom’s Hardware
This one page changed my life.42 years ago today, it convinced my parents I shouldn’t go back to college.I started by upgrading PCs from a dorm room.Today @Dell is helping build the infrastructure that powers AI, from the edge to some of the world’s largest AI factories.… pic.twitter.com/OF3KTMrBeHJuly 31, 2026
The fledgling dorm-room startup has turned from a niche supplier of off-brand IBM-compatible computers into a massive tech giant. It owns iconic computer brands like Alienware and XPS, and has also jumped on the AI bandwagon, supplying servers to hyperscalers and data centers. Its latest income statement also lists total net revenue of $43 billion and a net income of $3.4 billion. Dell’s risk in 1984 also paid handsomely for him. He’s currently the fifth richest person on Forbes’ real-time billionaires list, with a net worth of $229.2 billion.
The computer company has also had its fair share of controversies. This includes an SEC investigation into improper accounting practices in 2005, a lawsuit and massive recall related to laptop batteries catching fire in 2007, and a security vulnerability in 2015 that could have exposed customer data to bad actors. Despite all that, the company continues to thrive today and release new products like the $699 XPS 13 and an affordable OLED gaming monitor in the Alienware AW3426DW. Dell has made a significant impact on PCs, laptops, and other systems for gaming, productivity, enterprise, and more.
Loans remain one of the most essential financial tools for individuals and businesses alike. Whether you are planning to buy a home, fund education, start a small business, or manage personal finances, understanding smart loan strategies can save money, reduce stress, and protect your credit score.
In 2026, borrowing wisely is about more than just interest rates. It requires planning, awareness of loan types, repayment strategy, and leveraging technology to manage debt efficiently. This article outlines actionable tips and strategies to make the most of loans while minimizing financial risks.
1. Understand Different Types of Loans
Before borrowing, it’s essential to know your options. Common loan types include:
Personal loans – Flexible borrowing for general purposes
Student loans – Specifically designed for education expenses
Mortgages – Long term loans for buying property
Auto loans – Vehicle financing options
Small business loans – Capital for entrepreneurship
Payday and short-term loans – High interest, risky options to avoid if possible
Choosing the right type of loan can save money on interest and fees while aligning with your financial goals.
2. Check Your Credit Score and Financial Health
A strong credit profile directly affects the interest rates and approval chances for loans. Before applying:
Check your credit score
Review your credit report for errors
Reduce outstanding debts if possible
Borrowers with higher credit scores often qualify for lower interest rates and better repayment terms, resulting in significant savings over time.
3. Compare Loan Offers Carefully
Interest rates are only one part of a loan’s total cost. To make an informed choice:
Compare annual percentage rates (APR)
Review origination fees, processing fees, and penalties
Understand prepayment conditions
Evaluate fixed vs variable interest rates
Using online calculators and comparison tools can help identify the loan that fits your budget and repayment capacity.
4. Borrow Only What You Need
A common mistake is borrowing more than necessary. Larger loans lead to higher interest payments and longer repayment periods.
Determine the exact amount required
Create a realistic budget for repayment
Avoid using loans for discretionary spending that can be delayed
Smart borrowing ensures loans serve as financial tools, not burdens.
5. Plan Your Repayment Strategy
Repaying loans efficiently can save hundreds or thousands in interest:
Make consistent, on-time payments to avoid penalties
Consider biweekly payments for mortgages to reduce interest
Use windfalls (bonuses, tax refunds) to pay down principal
Prioritize high-interest loans first
A structured repayment plan reduces stress and improves long-term financial health.
6. Use Loans to Build Credit, Not Debt
Loans, when managed responsibly, can strengthen your credit profile. Tips include:
Keep balances manageable
Avoid opening multiple loans simultaneously
Pay at least the minimum on time
Monitor credit reports regularly
Healthy loan management signals reliability to lenders and can unlock better financing options in the future.
7. Explore Low-Interest and Government-Backed Loans
Government programs and certain lenders offer lower interest loans for specific purposes:
Federal student loans with income-driven repayment plans
Small business loans with government guarantees
First-time homebuyer mortgage programs
Researching these options can reduce borrowing costs and provide more favorable repayment terms.
8. Avoid Predatory Loans
Short-term payday loans, high-interest credit, and aggressive lending schemes can trap borrowers in cycles of debt.
Read all terms carefully
Avoid loans with hidden fees
Compare alternatives before committing
Being cautious protects your finances and reduces stress.
9. Leverage Technology for Loan Management
Apps and online platforms can simplify loan tracking and repayment:
Automatic reminders for payments
Consolidation or refinancing options
Tools to monitor interest savings and payoff timelines
Technology helps borrowers stay organized and avoid missed payments.
10. Educate Yourself Continuously
Financial literacy is key. Understanding interest calculations, amortization schedules, and debt-to-income ratios empowers borrowers to make smarter decisions.
Attend webinars
Read personal finance blogs and books
Consult financial advisors when necessary
Being proactive ensures loans are used strategically, not reactively.
Conclusion
Smart loan strategies in 2026 focus on planning, understanding, and responsible management. By choosing the right loan, comparing offers, and implementing repayment strategies, borrowers can maximize benefits, save money, and protect their financial future.
Loans are powerful tools when used wisely. With awareness, discipline, and the right resources, you can achieve goals ranging from home ownership and education to entrepreneurship without jeopardizing financial stability.
The September 2025 announcement wasn’t just another iPhone launch. Apple unveiled a lineup that signals a fundamental rethinking of what the company believes its customers actually want. The iPhone 17 family introduces four distinct models, each targeting a specific user profile with surgical precision. Most notably, the thin-obsessed iPhone Air replaces the Plus model entirely, suggesting Apple has finally accepted that bigger isn’t always what people are asking for.
After spending weeks with these devices and synthesizing professional reviews, real-world testing data, and technical specifications, a clear picture emerges. This isn’t about incremental upgrades. Apple has made deliberate trade-offs across the lineup, and understanding which compromises you’re willing to accept will determine which model deserves your money.
The iPhone Air Paradox: When Thin Becomes the Feature
At 5.6mm thick and weighing just 165 grams, the iPhone Air represents the most extreme design Apple has attempted since the iPhone 6. The device feels almost impossibly light in hand, prompting the inevitable double-take that every thin device inspires. That Grade 5 titanium frame with its mirror-polished finish doesn’t just look premium. It solves the structural challenges that plagued earlier attempts at ultra-thin smartphones.
The engineering behind this thinness deserves attention. Apple redesigned the internal architecture entirely, creating a raised plateau on the back that houses the camera system, speaker, and Apple silicon. This isn’t aesthetic flourish. By consolidating components into this plateau, Apple maximized space for a high-density battery that delivers up to 27 hours of video playback. For a device this thin, those numbers should be impossible.
Real-world battery performance tells a more nuanced story. Professional reviewers consistently reported getting through a full workday, but just barely. CNN Underscored’s testing showed approximately 11 hours of mixed use, which translates to reaching for a charger by early evening rather than before bed. The optional MagSafe battery pack extends usage to around 40 hours total, but that addition defeats the portability argument somewhat.
The single 48MP fusion camera represents the most significant compromise. Where the standard iPhone 17 offers dual lenses and the Pro models pack three, the Air relies on computational photography alone. For most social media and everyday photography, this works fine. For anyone who regularly zooms beyond 2x or shoots in challenging low-light conditions, the limitations become apparent quickly.
Performance never feels compromised. The A19 Pro chip handles everything from 4K video editing to demanding games without thermal throttling, despite the minimal internal volume. The 12GB of RAM ensures smooth multitasking, and the 6.5-inch Super Retina XDR display with ProMotion at 120Hz delivers the visual experience you’d expect from a flagship device.
The question isn’t whether the iPhone Air works well. It does. The question is whether thinness matters enough to justify a $999 price point when the standard iPhone 17 starts at $799 with more camera versatility and better battery life.
iPhone 17 Pro and Pro Max: Aluminum Returns, Performance Peaks
Apple made a surprising material choice this year. After years of titanium Pro models, the iPhone 17 Pro lineup returns to aluminum. This isn’t a cost-cutting measure. Aluminum offers superior heat dissipation properties, which matters when you’re pushing the A19 Pro chip and its 6-core GPU to maximum performance.
The new unibody aluminum frame incorporates a vapor chamber cooling system, a first for iPhone. During extended gaming sessions or 4K video recording, this thermal management prevents the performance throttling that plagued previous generations. The phone stays noticeably cooler under heavy workloads, which translates to sustained peak performance when you actually need it.
Camera upgrades define the Pro experience this year. All three lenses now feature 48MP sensors, creating what Apple calls eight pro lenses in your pocket when you factor in different focal lengths and computational modes. The standout improvement is the new telephoto lens with its next-generation tetraprism design and 56 percent larger sensor. The jump from 5x to 8x optical zoom at 200mm provides genuine reach for distant subjects without resorting to digital crop quality.
The front-facing camera deserves specific mention. The 18MP Center Stage camera uses a unique square sensor that captures images in any orientation without requiring phone rotation. For video calls, this means the camera can keep you centered while you move around, mimicking the experience of professional conferencing systems. The Dual Capture feature that records simultaneously from front and rear cameras opens creative possibilities for content creators who want reaction shots without separate equipment.
Battery life on the Pro Max reaches new heights. Early testing suggests this is the longest-lasting iPhone ever made, with capacity increasing approximately 9 percent over the previous generation despite similar physical dimensions. Combined with the more efficient A19 Pro chip and new N1 networking chip, all-day battery life becomes an understatement. Heavy users report two-day stretches between charges under normal usage patterns.
Storage configurations start at 256GB for both Pro models, doubling the base storage compared to last generation. The Pro Max now offers up to 2TB, though that configuration hits a steep $2,000 price point. For professional photographers and videographers who shoot extensive 4K ProRes footage, that capacity becomes justifiable. For everyone else, the 512GB option at $1,399 provides ample headroom.
The iPhone 17 Pro starts at $1,099, while the Pro Max comes in at $1,199. That $100 premium over last year’s pricing stings slightly, but the doubled base storage softens the impact somewhat. These remain expensive devices positioned for users who demand maximum capability and are willing to pay for it.
Standard iPhone 17: The Smart Middle Ground
Priced at $799 with 256GB of base storage, the standard iPhone 17 makes a compelling case as the sensible choice for most buyers. This year’s model receives features previously reserved for Pro devices, most notably the 120Hz ProMotion display with Always-On functionality.
The display upgrade alone changes the daily experience significantly. Scrolling through social feeds, navigating maps, or switching between apps all feel noticeably smoother compared to previous 60Hz standard models. The Always-On display shows time, widgets, and notifications without requiring a screen tap, matching Pro functionality at a lower price point.
The A19 chip, while a step down from the Pro’s version, still delivers flagship performance. The 6-core CPU and 5-core GPU handle any task most users throw at it, from photo editing to gaming to multitasking across demanding apps. With 8GB of RAM supporting Apple Intelligence features, the phone feels future-proofed for software updates through at least 2029.
The dual-lens camera system uses 48MP sensors for both main and ultrawide lenses. While missing the Pro’s telephoto reach, the 2x optical quality zoom through sensor cropping provides enough versatility for everyday photography. Low-light performance has improved meaningfully, producing cleaner images with less noise in challenging conditions.
What the iPhone 17 lacks compared to its siblings is the Pro’s advanced telephoto capabilities and the Air’s statement-making thinness. For anyone who isn’t specifically seeking those attributes, the standard model delivers essentially the same daily experience at a significantly lower cost.
The N1 Chip and Connectivity Revolution
Every iPhone 17 model benefits from Apple’s new N1 wireless networking chip, representing a major shift away from Broadcom components. The N1 enables Wi-Fi 7, Bluetooth 6, and Thread connectivity while improving power efficiency across all wireless operations.
Wi-Fi 7 support matters more than it seems on paper. In congested environments with multiple competing networks, Wi-Fi 7’s multi-link operation and improved channel utilization deliver noticeably more consistent performance. Theoretical speeds reach up to 46Gbps, though real-world scenarios rarely approach those peaks. Still, file transfers and streaming feel snappier on compatible networks.
Personal Hotspot and AirDrop both benefit from the N1’s improved efficiency. Battery drain during hotspot usage drops measurably, and AirDrop transfers complete faster with fewer interruptions. These aren’t revolutionary changes, but they smooth out daily friction points that accumulate over thousands of interactions.
The Pro models retain Qualcomm’s Snapdragon X80 modem for 5G connectivity, while the iPhone Air uses Apple’s new C1X modem. This split approach suggests Apple isn’t yet confident in its modem technology for flagship devices but is willing to test it in the Air where network performance matters slightly less to the target demographic.
Software and Apple Intelligence Integration
iOS 26 ships on all iPhone 17 models, bringing the full suite of Apple Intelligence features to devices with sufficient RAM. The writing tools, image generation capabilities, and enhanced Siri functionality work identically across the lineup since all models meet the 8GB RAM minimum threshold.
The new Bright Photographic Style customization offers more control over how photos look straight from the camera, reducing reliance on post-processing. Live Translation in Messages, Phone, and FaceTime works surprisingly well for supported language pairs, though accuracy still varies depending on accent and speaking speed.
Memory Integrity Enforcement, a new security feature enabled by the A19 chips, runs automatically to prevent memory-related exploits. Most users will never think about this feature, which is precisely the point. It operates invisibly while meaningfully improving device security against sophisticated attacks.
Color Options and Aesthetic Choices
The iPhone Air comes in Sky Blue, Midnight, Silver, and Lavender, all with that distinctive polished titanium finish that catches light dramatically. These colors feel more expressive than previous years, though fingerprints accumulate quickly on the mirror-like surface.
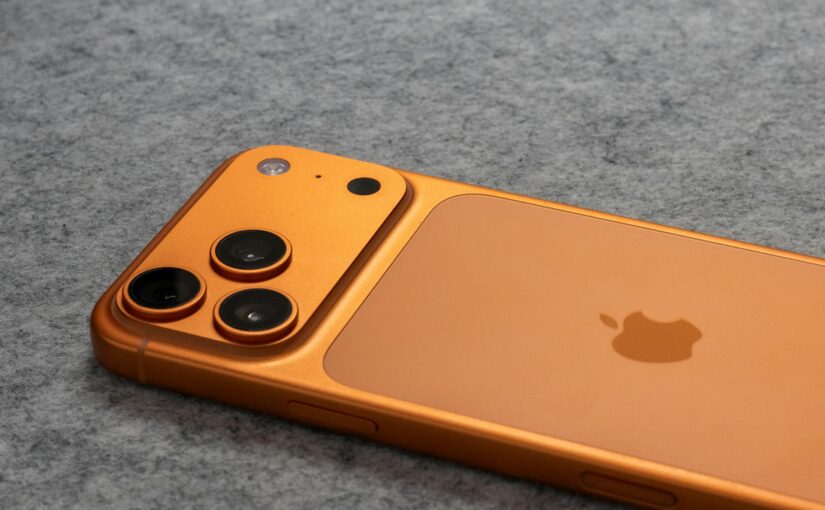
The Pro models offer Cosmic Orange, Deep Blue, and Silver in brushed aluminum. The Cosmic Orange particularly stands out as a departure from Apple’s typically conservative Pro color palette. It’s bold without being garish, and early sales data suggests it’s the most popular Pro color by a significant margin.
Standard iPhone 17 colors include Lavender, Mist Blue, Sage, Black, and White with aluminum frames. The matte finish resists fingerprints better than the Air’s polished titanium but lacks that premium jewel-like quality.
Ceramic Shield 2 and Durability Improvements
All models feature Ceramic Shield 2 on the front, providing three times better scratch resistance compared to previous generation. After weeks of real-world use without screen protectors, professional reviewers noted meaningfully fewer micro-scratches compared to earlier iPhones.
The iPhone Air additionally uses Ceramic Shield on the back for the first time, offering four times better crack resistance than previous glass backs. Combined with the titanium frame’s flex characteristics, the Air withstands pocket stress and accidental drops better than its extreme thinness would suggest.
Drop tests from various tech outlets confirm these durability claims. While no phone is indestructible, the iPhone 17 family shows improved resistance to the types of damage that occur during normal daily use.
The Verdict: Choosing Your iPhone
The iPhone 17 lineup forces a choice between competing priorities more clearly than previous generations. The standard iPhone 17 offers the best overall value, delivering flagship performance and features at a reasonable price. Most buyers should start here unless they have specific needs that justify the additional cost.
The iPhone Air appeals to a particular user profile. If you value aesthetics and portability above all else, and you’re willing to accept slightly shorter battery life and a single camera, the Air delivers on its promise. It’s genuinely impressive engineering. Just understand what you’re trading for that thinness.
The Pro models make sense for photography enthusiasts, content creators, and power users who push their devices hard. The telephoto reach, improved low-light performance, superior thermal management, and extended battery life justify the premium for users who leverage those capabilities daily.
What’s notable about this lineup is that there are no bad choices. Every model succeeds at what it sets out to accomplish. The question is which set of trade-offs aligns with how you actually use your phone rather than how you imagine using it.
Pre-orders began September 12, 2025, with devices shipping September 19. Availability remains strong across all models and storage configurations through Apple’s online store, retail locations, and major carriers.