AMD highlights Ryzen 5 5500 briefly topping Amazon CPU best sellers, beating 9800X3D — $80 DDR4 CPU remains a top seller during memory crunch


If you’ve ever stumbled upon the Amazon CPU best sellers list over the past few years, you’ve been greeted by a wall of red boxes. This list isn’t a good source of data, without hard sales figures and heavily skewed toward what’s available on Amazon at any given time. But AMD senior marketing director Saša Marinković recently shared a screenshot of the Amazon CPU best-sellers list, bragging on AMD’s representation. The interesting bit is that the screenshot Marinković shared shows the $80, DDR4-based Ryzen 5 5500 at the top of the charts.

Go deeper with TH Premium: CPU

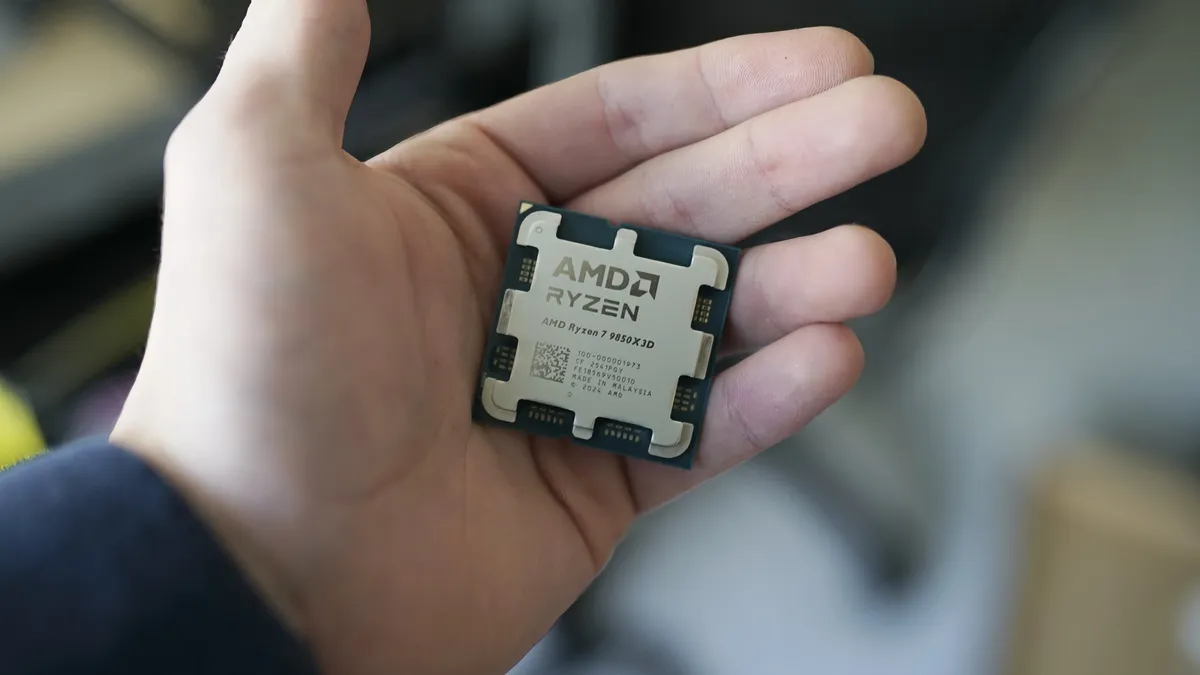
A hand holding the Ryzen 7 9850X3D.

(Image credit: Tom’s Hardware)

The Ryzen 7 9800X3D has since reclaimed the top slot — it is the best CPU for gaming, after all — but the screenshot touches on the prevalence of DDR4 platforms, nearly four years after the launch of Zen 4 and introduction of DDR5 to AMD’s platform. It’s not just the Ryzen 5 5500, either.


Source link

The Case for Putting 20% Down on Your Next Home


If you’re planning to buy your next home soon, you’ve probably heard the old rule about saving 20% for your down payment.

The truth is, you usually don’t have to. Plenty of loan options let qualified buyers put down much less. But a lot of repeat buyers are choosing to put down 20% anyway.

So, why are they if they don’t have to?

Two reasons. They know a bigger down payment pays off, and after years in their current house, they’ve built up enough equity that it’s finally possible.

Repeat Buyers Put More Money Down

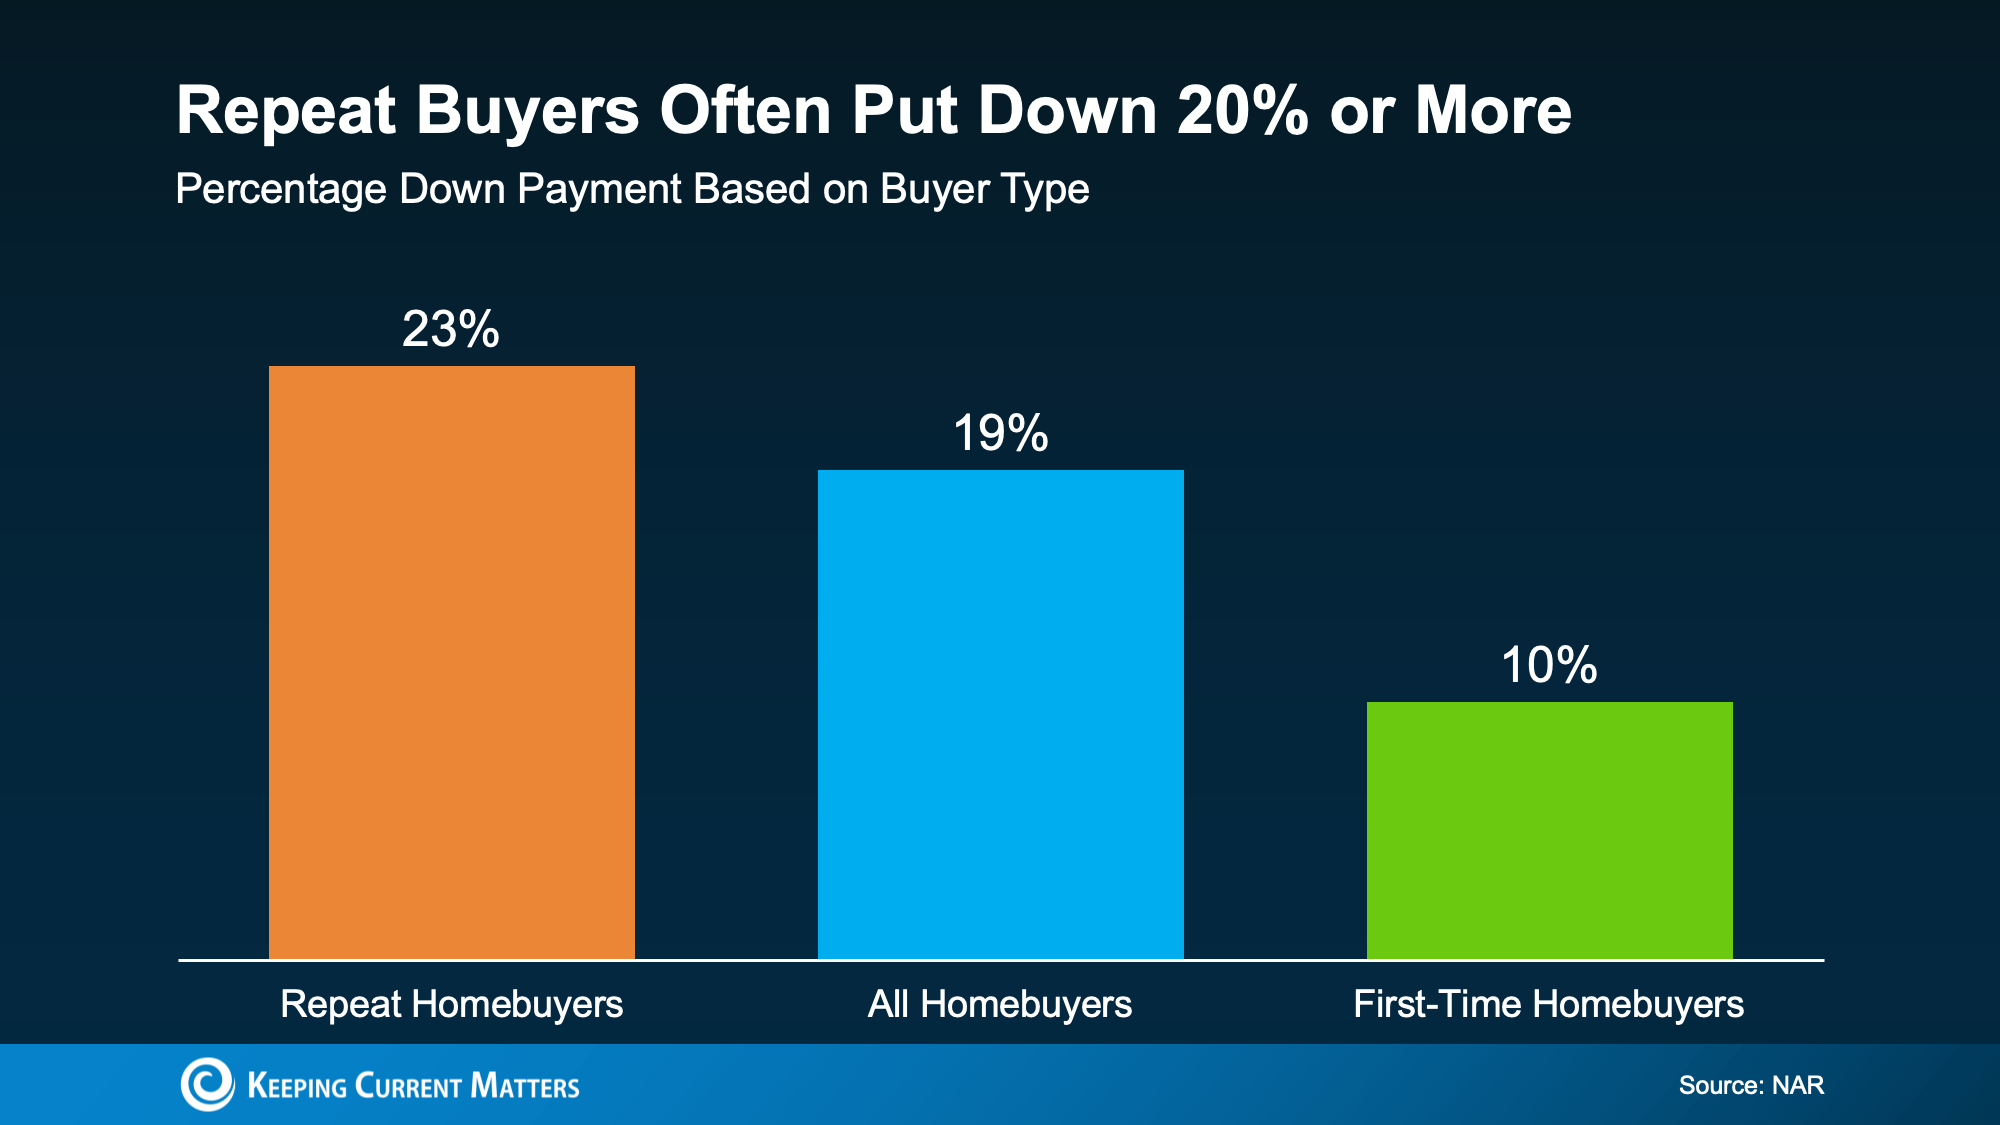
According to the National Association of Realtors (NAR), the typical repeat buyer puts down 23%when they buy a home (see graph below):

a graph of a number of colored squares

That’s more than double the 10% they may have put down as a first-time buyer. So, how do they manage it? Their equity.

When you’ve owned a house for a while, two things tend to happen. One, you pay down your mortgage, and two, your home’s value climbs. The difference between what you still owe on your mortgage and what your house is worth is your equity. And the longer you’ve lived in your house, the bigger that number grows.

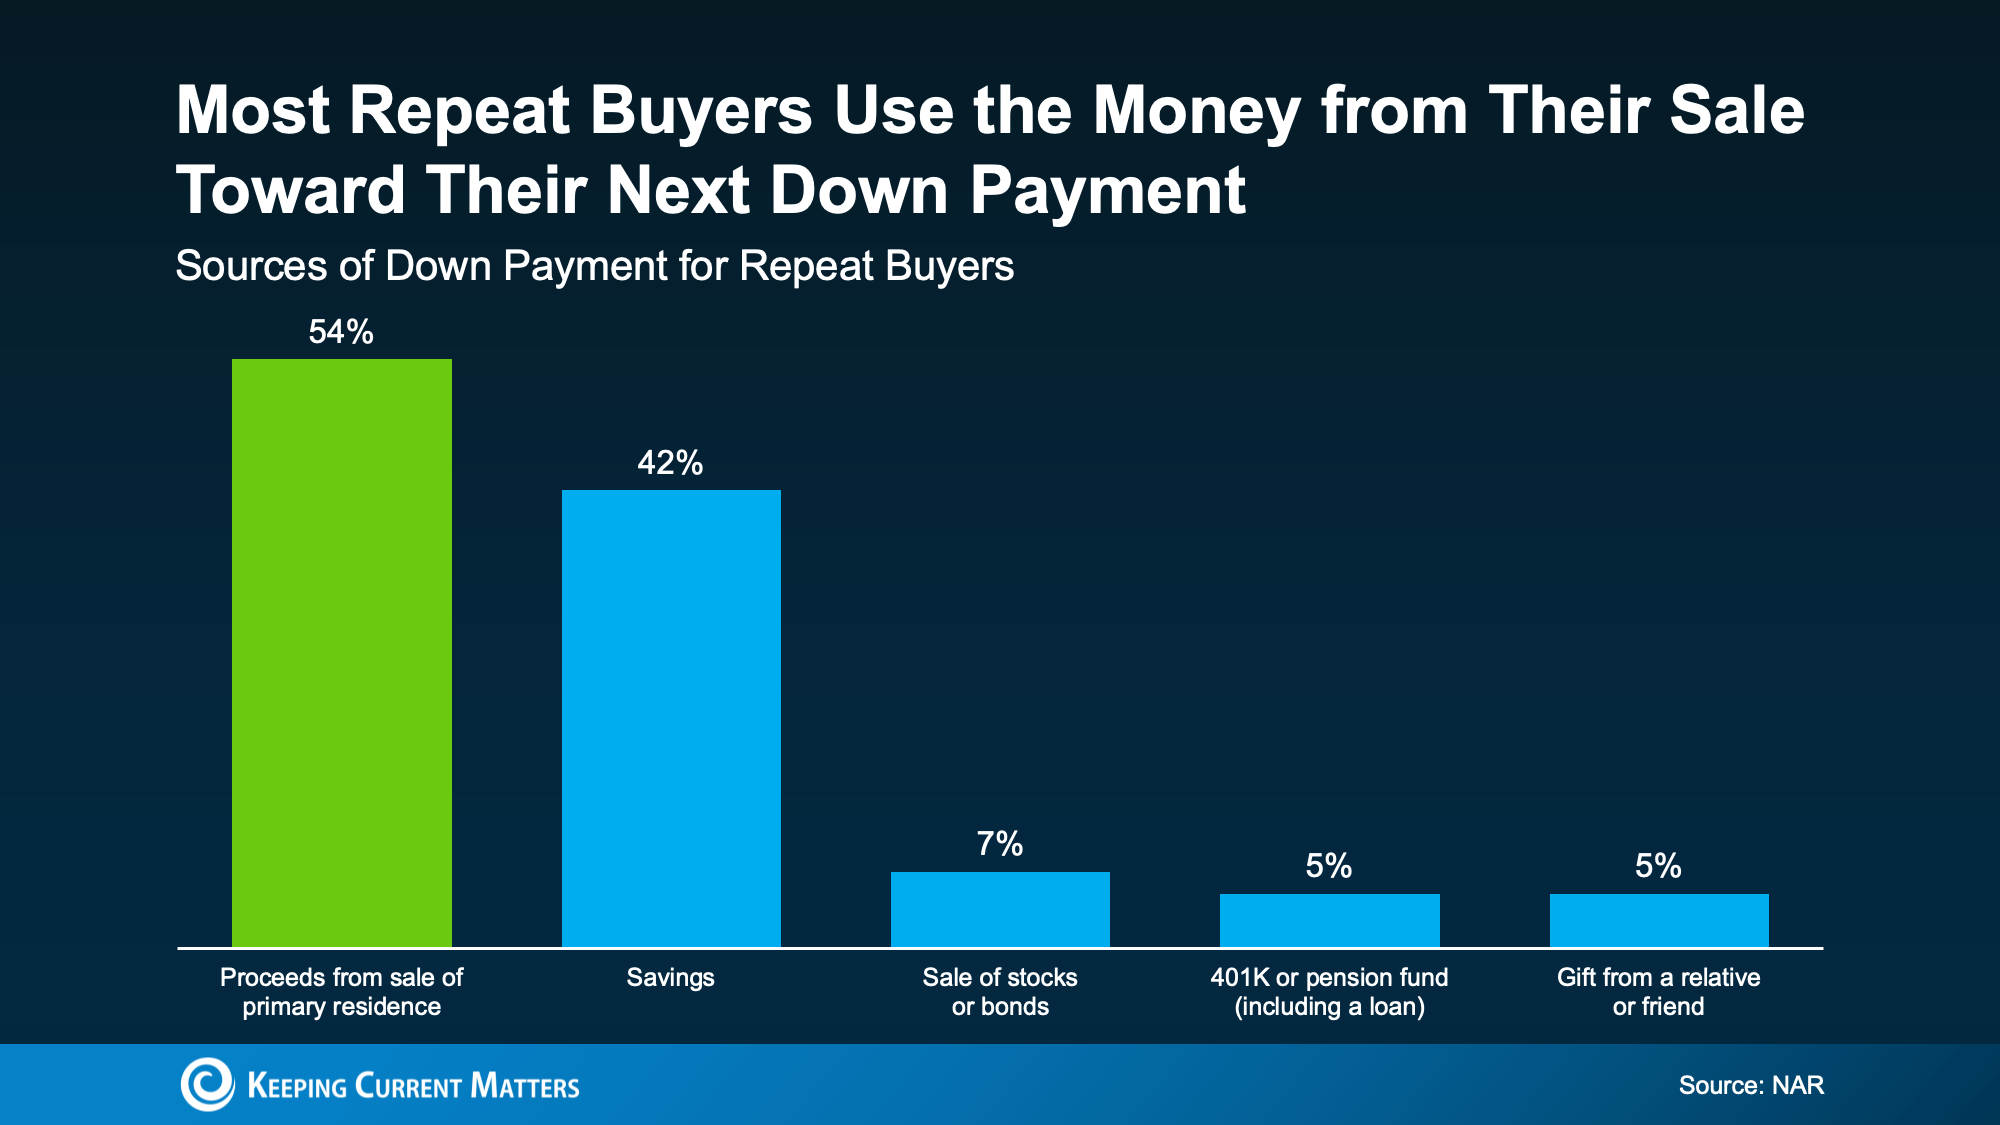
When you sell, your equity turns into cash. And NAR data shows most repeat buyers put it straight toward their next down payment (see chart below):

a graph of a financial graph

First-time buyers don’t have that springboard yet, and that’s normal. But if you already own, you may be holding more buying power than you think because of it.

And if putting 20% down is finally possible, it may be worth at least considering. Here’s why. Let’s go over what you get in return.

4 Perks of Putting 20% (or More) Down

As Redfin explains, putting more down pays off in a few ways:

  • A smaller monthly payment. The more you put down, the less you borrow at today’s rates. And if taking on a higher mortgage rate is one of the reasons you’re debating whether to move, that’s a win.

  • Paying less interest. A smaller loan can also carry less interest across the life of your mortgage. If you put 20% down, you’ll only pay interest on the remaining 80%. Put 5% down and you’ll pay interest on the remaining 95%, which will cost you more over the lifetime of the loan.

  • No private mortgage insurance (PMI). When you put down less than 20% on a conventional loan, lenders usually add a monthly fee called private mortgage insurance. With 20% down, PMI isn’t required and that saves your money every month. 

  • A stronger offer. A larger down payment can make your offer more attractive, since sellers tend to read it as a sign your financing is solid and the deal is more likely to close.

Bottom Line

So, no. You don’t need to put 20% down to buy your next home. But you may want to. If your equity puts it within reach, going bigger can lower your costs and make moving more doable than you think – even with today’s rates.

A trusted lender can run the numbers on your financing, and a local agent can help you figure out what your current house could add to your next down payment.


Source link

Intel’s Core Ultra 5 250K Plus is down to its lowest price ever at $154 — get a 20-core midrange CPU with 5.5 GHz boost for an entry-level price


The Intel Core Ultra 5 250K Plus is down to its lowest price ever, with Amazon slashing 30% off the list price to bring it down to $154. That’s even cheaper than the lowest price we’ve seen on the Core Ultra 5 250KF, which sells for about $20 less. Despite being priced like an entry-level CPU, the 250K Plus ranks among our best CPUs for gaming.

The Core Ultra 5 250K Plus originally launched for $200, but it didn’t take long for its recommended price to climb to $220. That’s because it punches far above what its price would suggest, even at full MSRP. It, along with the Core Ultra 7 270K Plus, was framed as a last-ditch effort to bring Arrow Lake to the masses after the failed launch of the original range.

And the refresh worked. The Ultra 5 250K Plus is a 20-core CPU with a split between six Lion Cove P-cores and 12 Skymont E-cores. As with all Arrow Lake CPUs, the 250K Plus doesn’t have Hyper-Threading, so it comes with 20 threads, as well. The chip comes with a maximum boost clock of 5.5 GHz, and a PL1/PL2 power of 125W/250W. As it’s an unlocked K-series processor, you can overclock the chip, though you’ll need to pair it with a Z-series chipset.

Although we almost always recommend a Z-series chipset with a K-series SKU, there actually isn’t a locked version of the 250K Plus. Further, many of the OC improvements are baked into the chip, including a 900 MHz bump in die-to-die frequency and a 400 MHz increase in memory fabric speed. Overclocking is a big upside, though it’s not strictly required, especially when we’re looking at a $154 CPU.


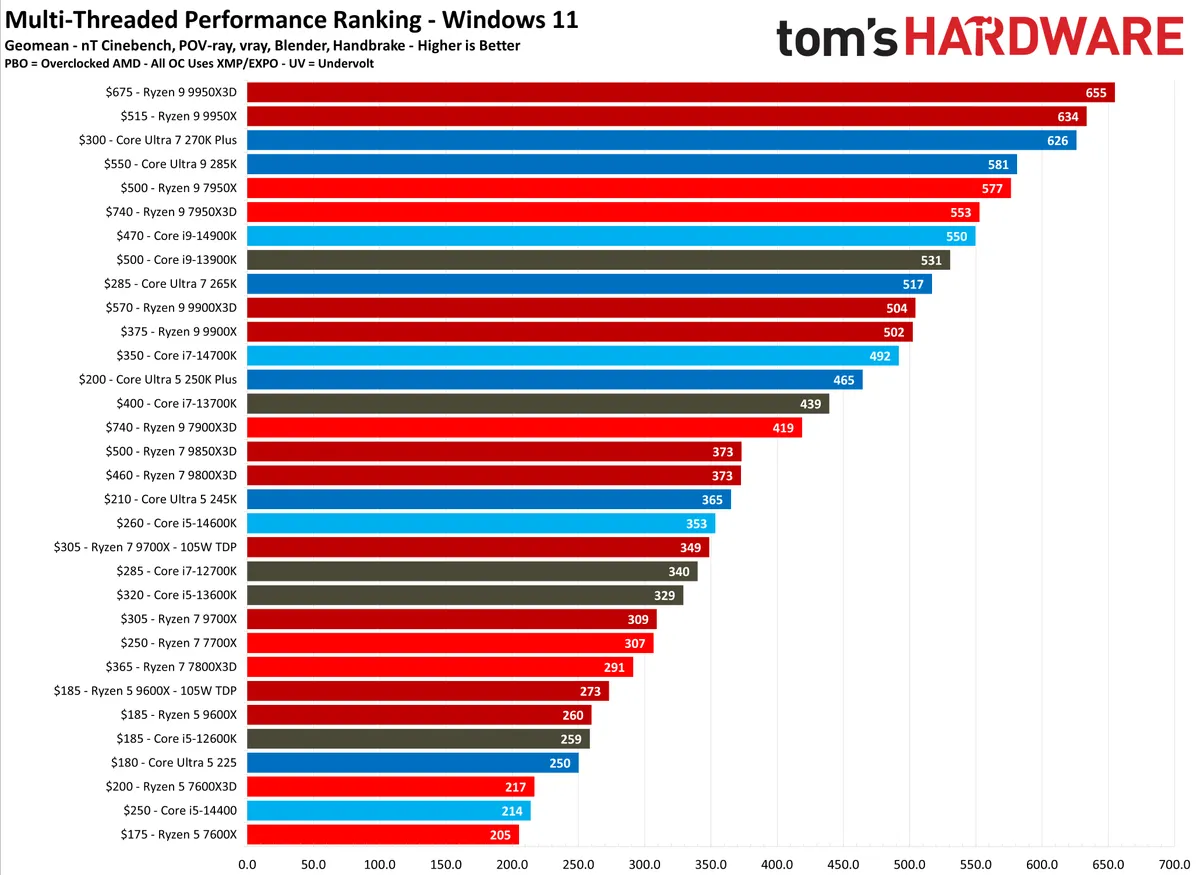
Although the Core Ultra 5 250K Plus is priced like an entry-level CPU, it performs much better than its current sales price would suggest, particularly in productivity workloads. You can see the results for the 250K Plus from our CPU benchmark hierarchy in the gallery below.

The 20 cores and threads help it to punch up in multithreaded performance. The chip is 33% faster in our multithreaded geomean compared to AMD’s competing Ryzen 7 9700X, despite Team Red’s chip costing twice as much right now. Compared to the Ryzen 5 9600X that’s around the same price, Intel is a massive 80% ahead.

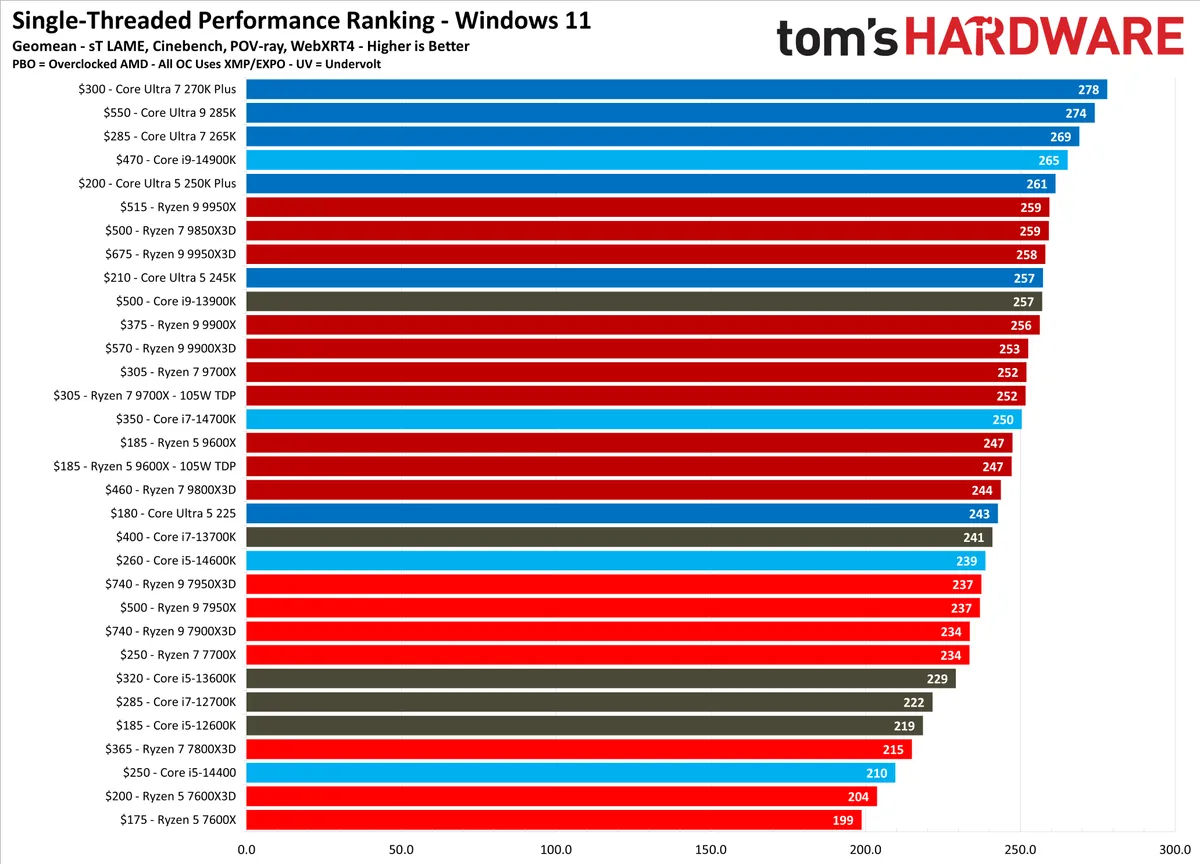
The multithreaded performance isn’t a result of simply throwing a ton of weak cores at the problem. As you can see from our single-threaded rankings, the Core Ultra 5 250K Plus came out ahead of every AMD offering we tested, including the flagship Ryzen 9 9950X. Last-gen’s Core i9-14900K is slightly faster, though it also costs nearly three times as much.

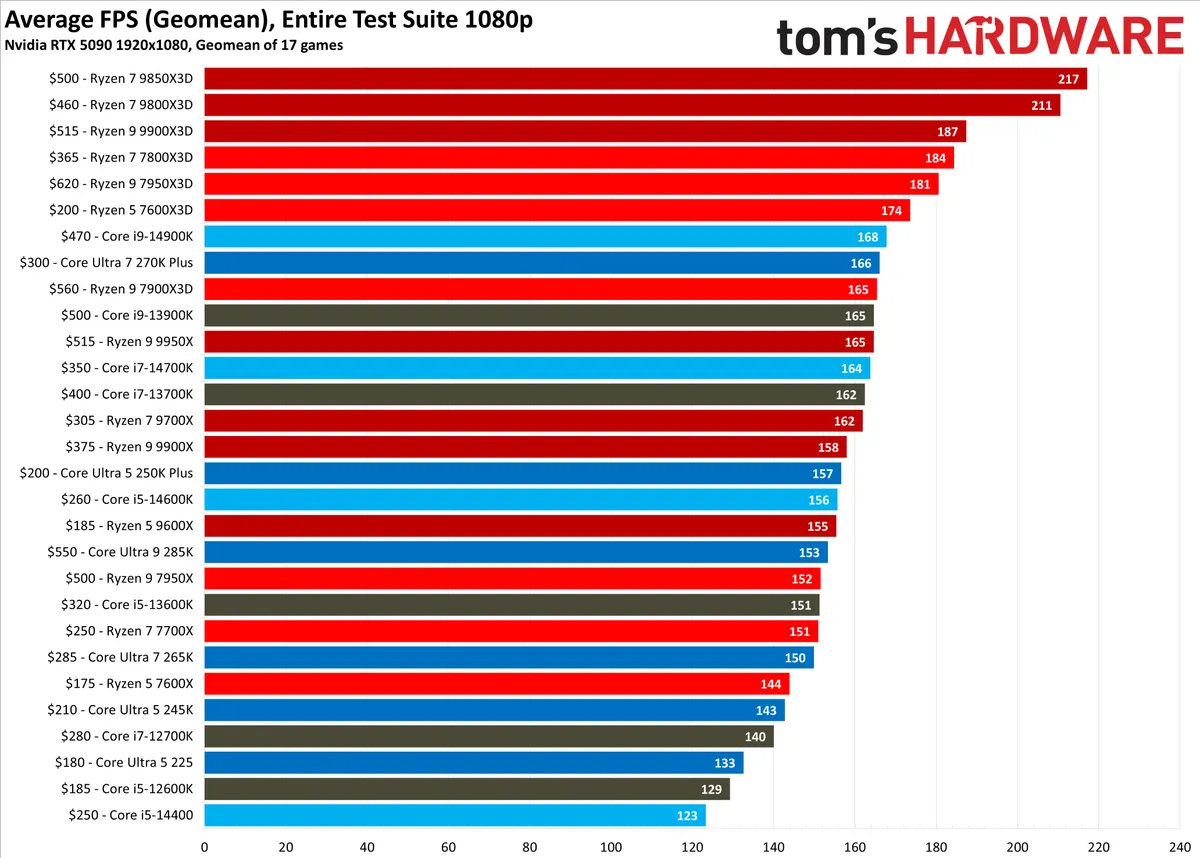
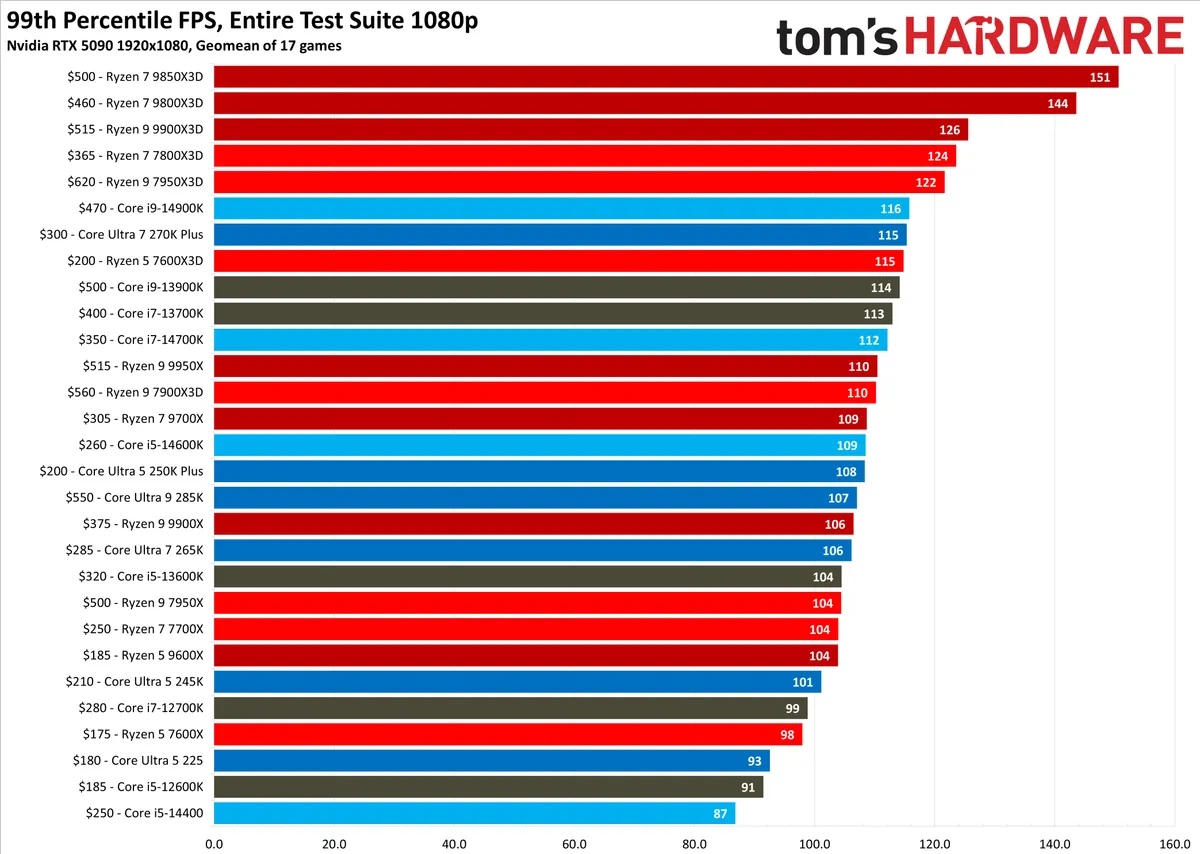
Gaming is where Intel has started to take a backseat to AMD, and the Core Ultra 5 250K Plus slips some rankings. On average, the chip is about as fast as the Core i5-14600K. That’s marginally faster than the Ryzen 5 9600X and about 3% behind the Ryzen 7 9700X. AMD’s Ryzen 5 7600X3D is about 10% faster, though in this current Core Ultra 5 250K Plus sale, Intel’s CPU is about $100 cheaper.

At $150, just getting a competent CPU is tough — just see our list of the best budget CPUs — and the Core Ultra 5 250K Plus is more than competent. Don’t miss this deal on Amazon.

If you’re looking for more savings, check out our Best PC Hardware deals for a range of products, or dive deeper into our specialized SSD and Storage Deals, Hard Drive Deals, Gaming Monitor Deals, Graphics Card Deals, gaming chair, or CPU Deals pages.


Source link

Thinking About Waiting for Lower Mortgage Rates? Read This First.


Imagine waiting a year to buy a home, only to find mortgage rates haven’t changed much. That may sound frustrating.But it’s a real possibility.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today’s forecasts, that may not happen. And you should know that before you decide what to do.

Let’s look at why experts don’t expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.

1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way

If you’re waiting for rates to fall, you’re not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.

The challenge is, that’s not what the experts who study mortgage rates every day are expecting.

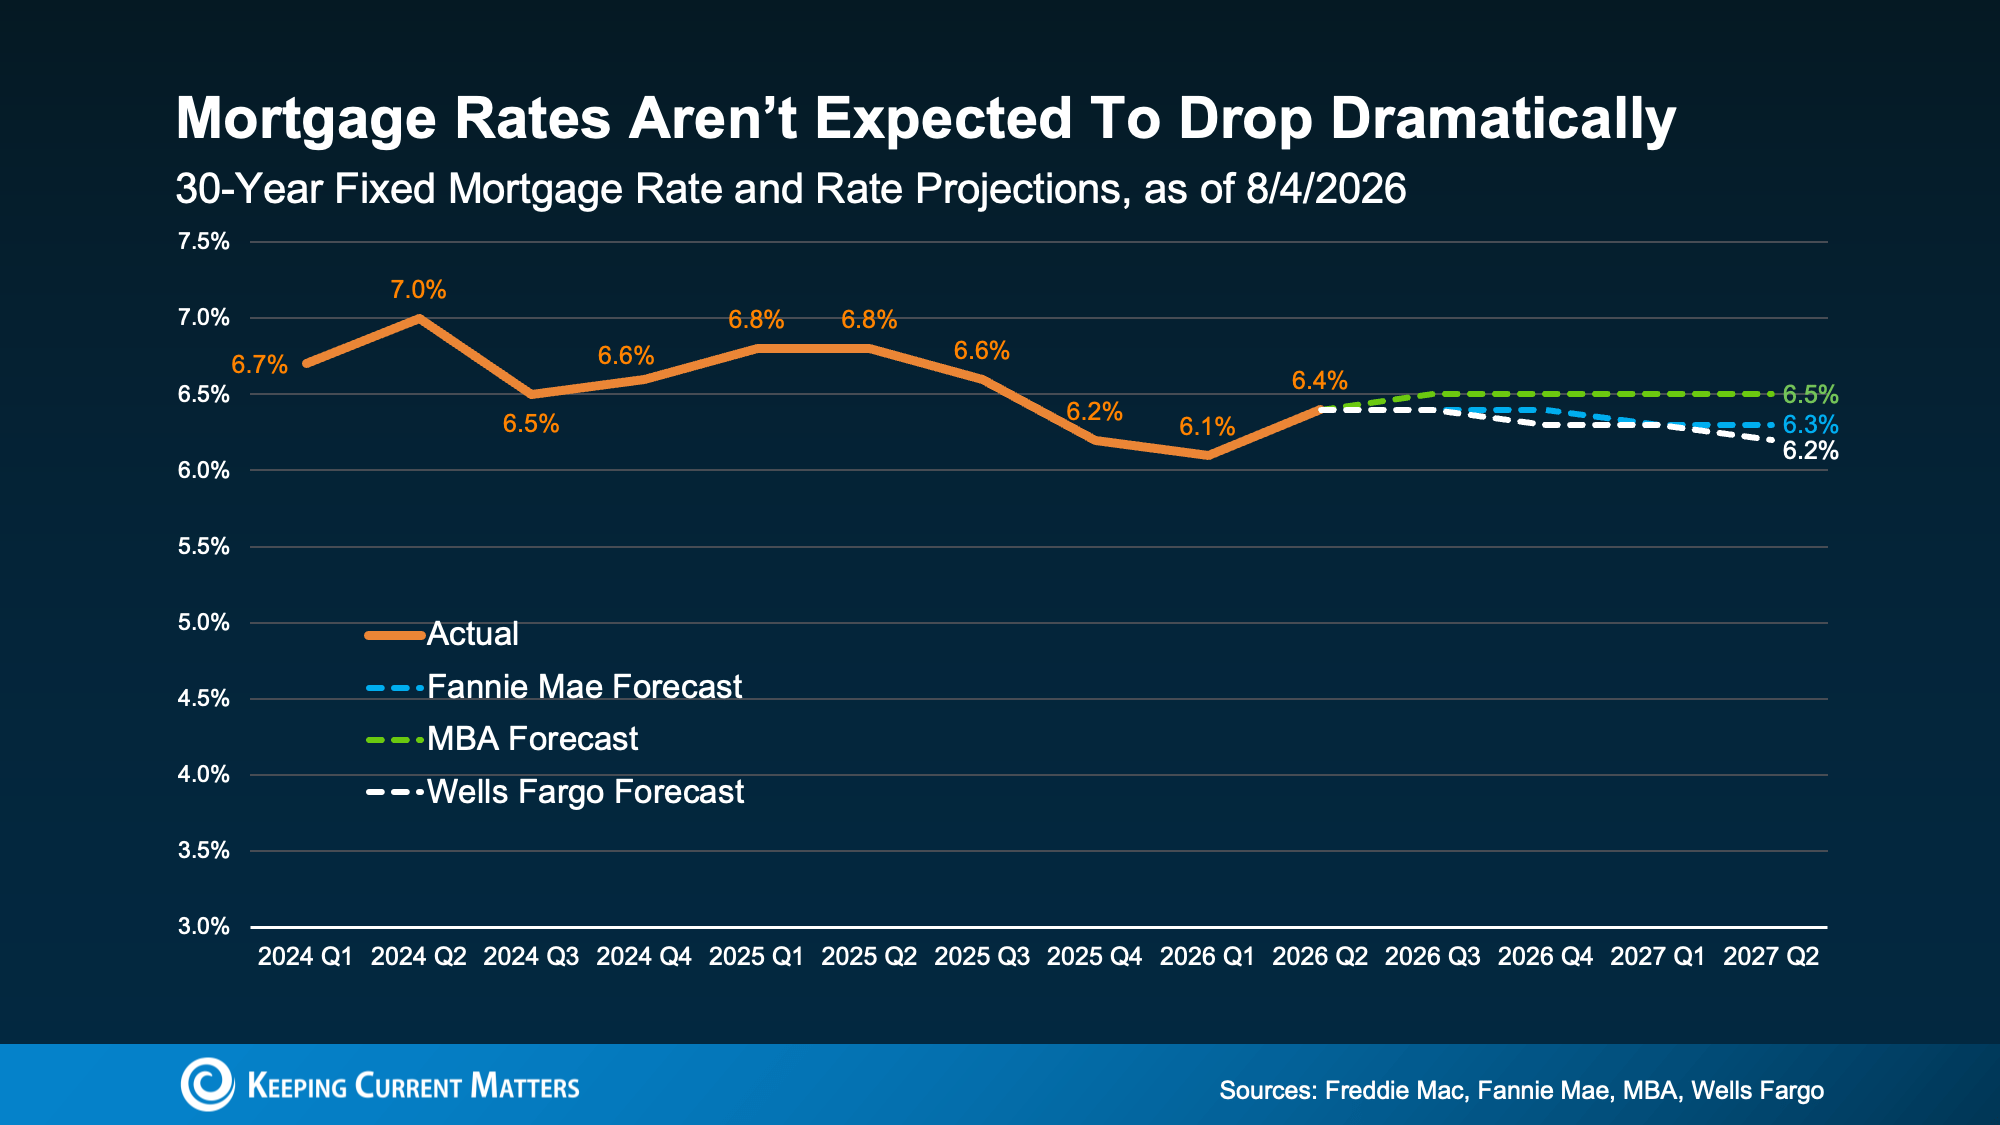
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):

a graph with numbers and lines

Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren’t pointing toward the kind of dramatic rate drop many buyers are waiting for.

Could rates move a little? Of course. But if you’re holding out for a bigger drop, today’s forecasts suggest you may be waiting a lot longer than you expect.

2. Inflation Is Still Elevated – And That’s Working Against Lower Rates 

One reason experts aren’t expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.

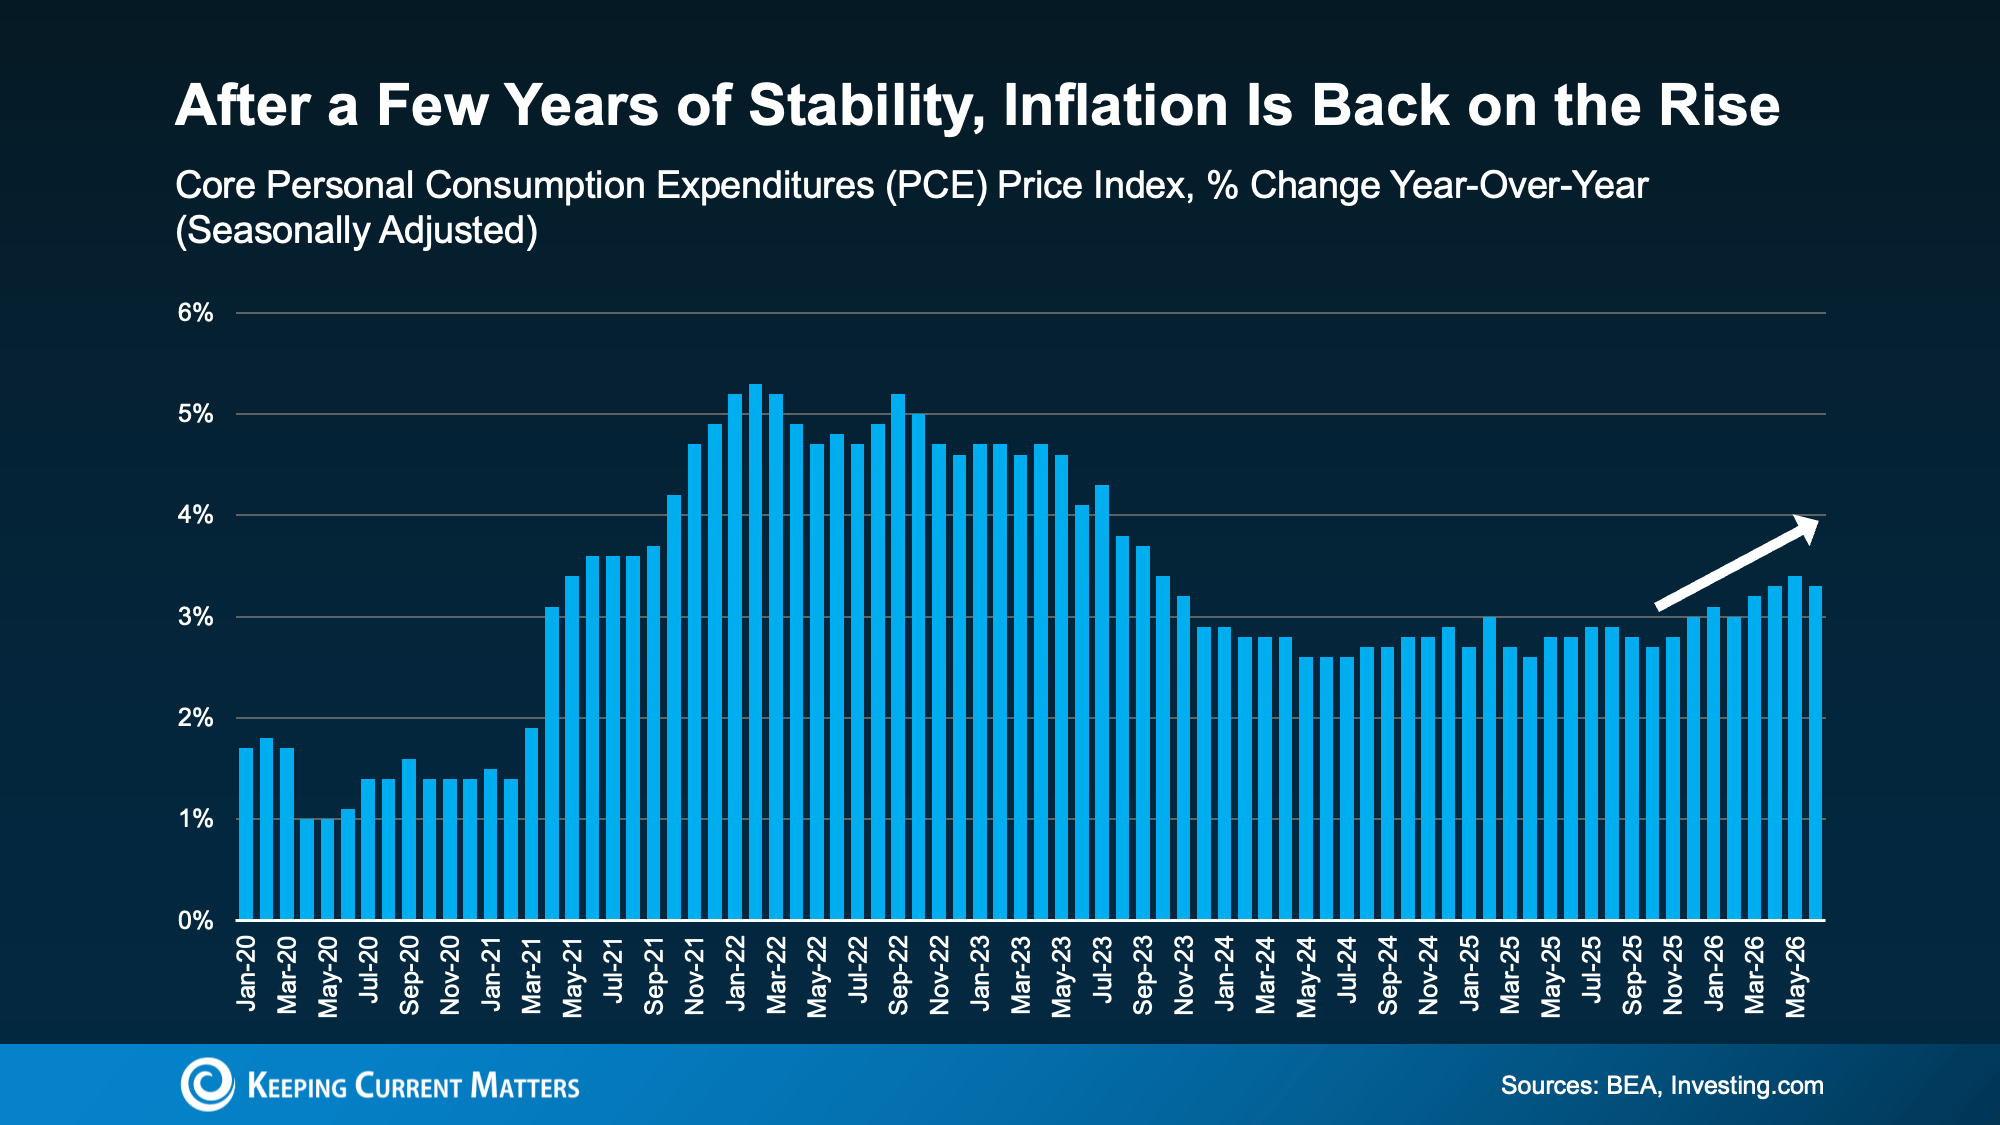
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

a graph of a number of people 

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn’t in place today. That helps explain why experts aren’t forecasting the kind of meaningful decline so many buyers are hoping for.

3. Today’s Rates Aren’t High, They’re “Normal”

And this may be the biggest mindset shift of all. The reality is, while today’s rates may feel high compared to a few years ago, they’re not high. They’re normal.

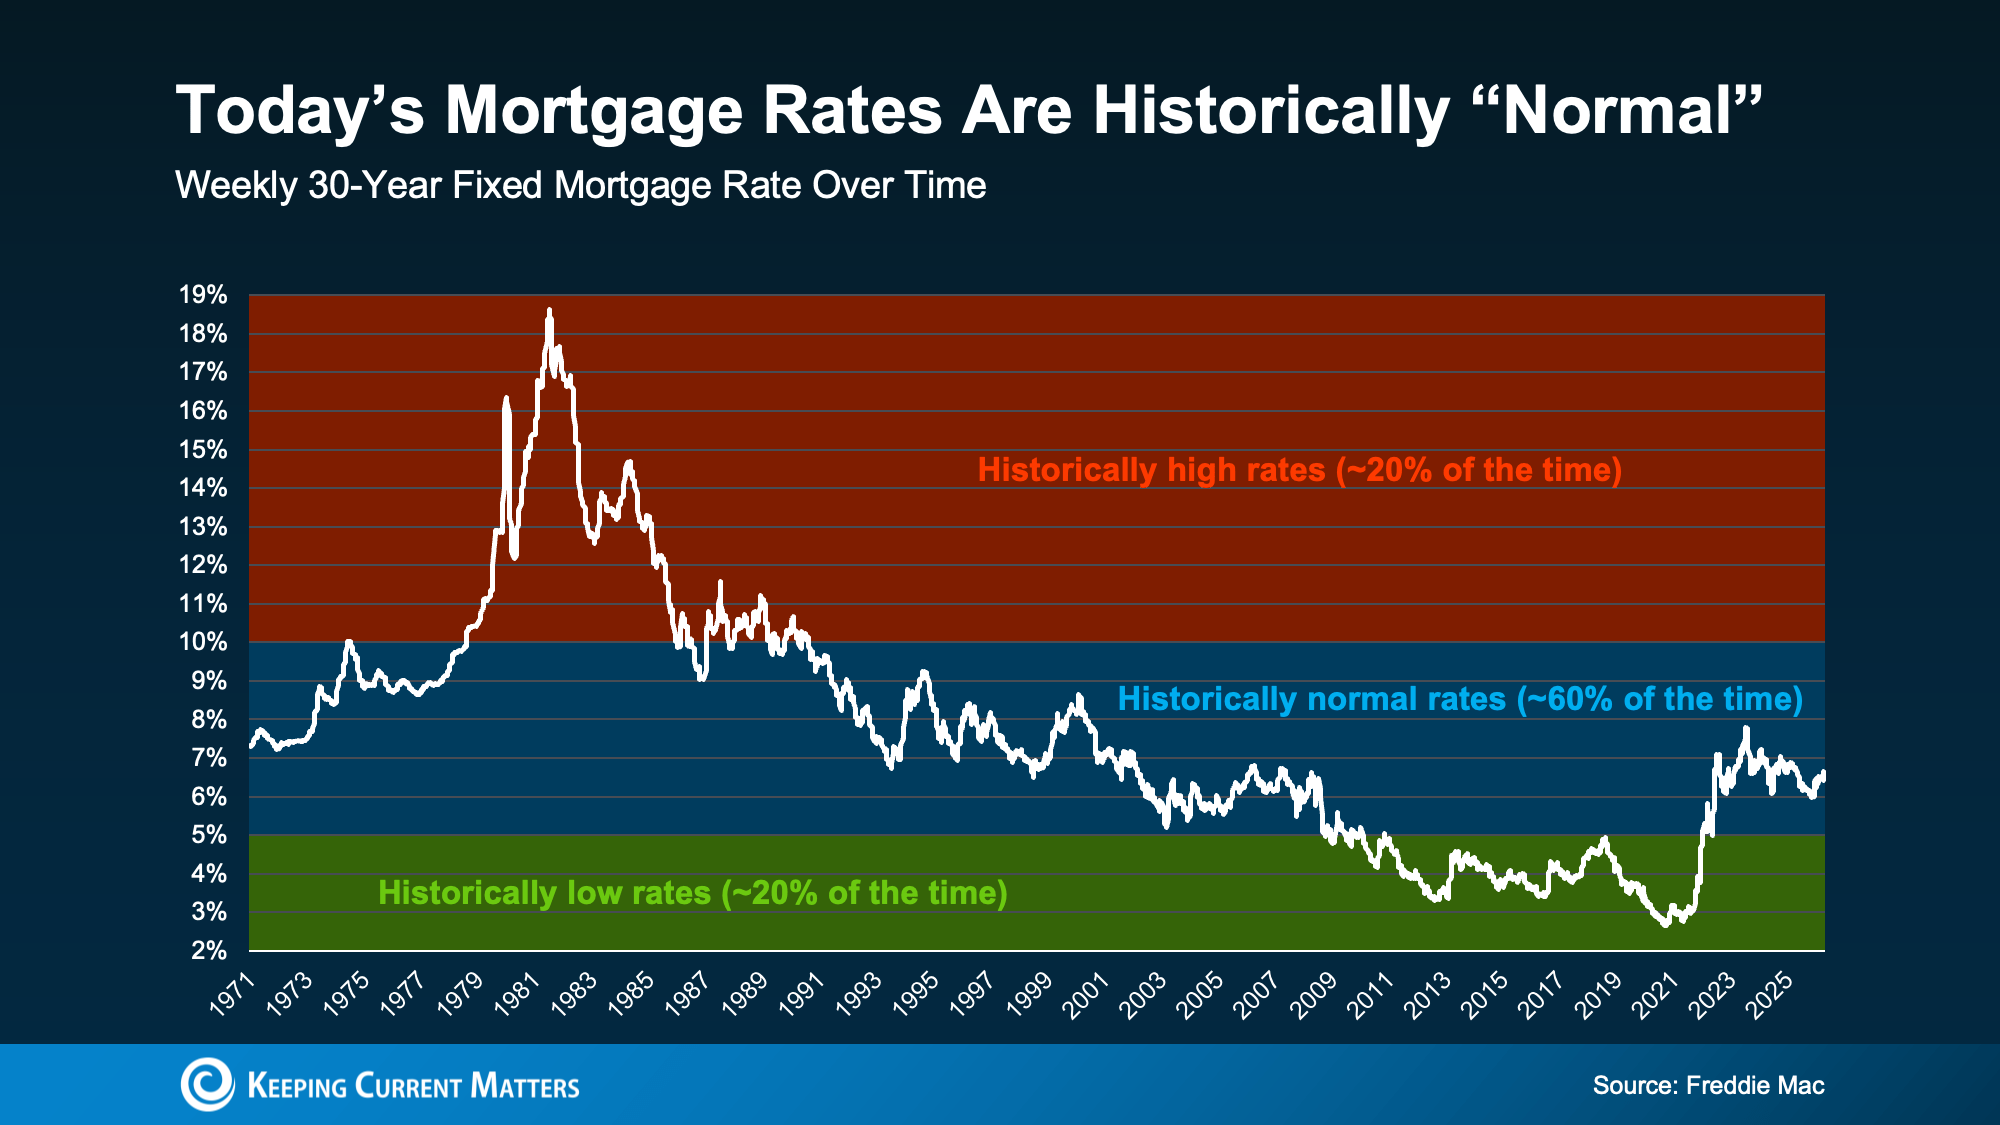
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):

a graph of a graph showing the rise of a mortgage rate 

Now, this doesn’t suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.

So… What Should You Do Instead?

None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.

  • Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.

  • Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It’s not the right choice for everyone, but it’s worth asking a lender if it fits your plans.

  • Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.

  • Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.

The important thing is you shouldn’t assume waiting is your only option.

Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.

Bottom Line

If you’ve been putting your home search on hold because you’re convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.

Connect with an agent or lender so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.


Source link

What is a co-op sponsor unit and why is it more expensive?


If you’re looking to buy a co-op in New York City, the term “sponsor unit” may have caught your eye while scanning listings. This type of co-op apartment offers several advantages, including the ability to skip the board approval process—a huge relief for many buyers.

Rather than being sold by an individual shareholder, a sponsor unit is an apartment still owned by the entity that originally converted the building into a co-op—usually the developer or the original landlord. Here’s how that happens: When a rental building converts to a co-op (such as during the big conversion wave of the 1970s and 1980s), existing tenants can choose to buy their apartment or keep renting under their existing lease. Any apartments that tenants didn’t buy remain in the sponsor’s hands, and the sponsor continues collecting rent from them. Those units only hit the market as “sponsor units” once the tenant eventually moves out and the sponsor decides to sell.

Keep in mind that sponsor apartments can be more expensive than resale co-ops, despite the wear and tear from their rental histories. These places can also have higher closing costs than regular units. 

Consider this your go-to guide to sponsor apartments, so you know what’s involved in buying one.


[Editor’s note: An earlier version of this article was published in July 2025 and has been updated with new information for August 2026.]


Pro: No board approval is required

Hands down, avoiding this step is the most significant advantage of buying a sponsor apartment. In a typical co-op purchase, the application process can feel invasive, with scrutiny of your finances and your character. 

In addition to jumping through fewer financial hoops, the buying process is also quicker in a sponsor sale because you don’t have to wait for the review of your board package and an interview. That said, your finances will still need to be assessed. But as long as your offer is accepted—and assuming you can get a mortgage if you are financing—you won’t need further vetting.  

“Buying in a sponsor-owned co-op allows you to finance as much as the banks will allow you,” said Melissa Cohn, regional vice president at William Raveis Mortgage. 

So if you’re seeking a conforming loan—the 2026 limit is $1,249,125 in NYC—then it’s possible to get up to 97 percent financing, she said. This is in contrast to a resale co-op, where the board often limits financing to 80 percent.

Sponsor units also open opportunities for buyers with less traditional incomes—such as freelancers, contract workers, or self-employed individuals. “There are banks that do not require income verification or use alternative means of verifying income if qualifying using conventional loans doesn’t work,” Cohn said. 

The bylaws of the individual co-op will dictate the rules about these transactions, but the sponsor doesn’t necessarily have to abide by the same standards, said Patrick Lavell, branch manager at Crosscountry Mortgage, noting that sponsor units continue to be a good alternative for some buyers who may not otherwise get approved by most co-op boards.

According to Lavell, down payment requirements, post-closing assets (aka “reserves”), and debt-to-income ratios with many co-op boards are far more conservative than what lenders allow. That means a buyer could be approved for a mortgage but still be declined by a board due to insufficient assets or a debt-to-income ratio that’s too high.

“With a sponsor-owned unit, the buyer often bypasses the co-op board approval process and only needs to obtain underwriting approval from their lender before closing almost immediately,” he said.

Pro: You often get original prewar details

Sponsor units will typically have been rented out for decades and, in many cases, are in original condition. They may have attractive prewar details, such as dentil moldings and herringbone floors. Of course, these architectural features may well be obscured behind the paint applied with every new lease, but they can give the place a character that can be difficult to find elsewhere. 

On the other hand, it’s possible the units aren’t in great shape and may require specialists to remove lead-based paint or asbestos—or to do a full-scale renovation. In that case, Karen Sonn, a closing attorney at Sonn Associates, said the building’s alteration agreement or sales package may require the incoming buyer to do upgrades to the electric panel, windows, or radiators. 

As with all resales, some units will have been renovated to sell at a higher price, and these sponsor makeovers are not always necessarily in keeping with what you would do yourself. Some buyers find themselves re-renovating within a couple of years when the sponsor’s upgrades are not up to par.

Compounding the matter, sponsors do not need board approvals for pre-sale renovations. So, for example, if the sponsor installed an in-unit washer/dryer in a building that doesn’t permit it, the board will not grandfather that washer/dryer to the next buyer (i.e., you!), Sonn said. In other words, no such luck—and you may get stuck paying for the machines to be removed.

Be aware that pre-purchase inspections are essential for “as is” apartments, providing a clear picture of their overall condition and what may be involved in a renovation. Inspections can also help determine the quality of upgrades in renovated units.

If you purchase a sponsor unit, know that all renovation plans must be approved by the co-op board, the building architect, and the management company. Make sure to review the board’s alteration policy before signing the contract.

“Most buildings have strict rules for renovations: limits on the number of renovations at any one time [or on the] length of any renovation,” Sonn said.

Con: They often cost more than non-sponsor units

All things being equal, sponsor apartments can be more expensive than resale apartments. 

Jonathan Miller, president and CEO of real estate appraisal firm Miller Samuel, said the higher price tag is partly due to sponsor apartments that are often newly renovated. But even if there are two similar renovated or unrenovated apartments and sponsor ownership is the only difference, “you might see a 5 percent or even a 10 percent premium on the sponsor unit.” 

On the bright side, if you purchase from a sponsor, you typically do not have to pay the transfer tax (more on that below). Chalk it up to paying a premium for not having to go through the board approval process.

Miller said it’s not a hard-and-fast rule that sponsor apartments have a higher price tag, but in situations where a sponsor unit sells for less than a comparable resale, it’s often because the sponsor apartment is “far more derelict in condition than a typical unrenovated non-sponsor apartment.”

Con: The closing costs might be higher, too

Although most co-ops require buyers to put down 20 to 25 percent of the purchase price, you might be allowed to pay a smaller down payment of only 10 percent when buying a sponsor co-op.

However, you may face higher closing costs because buyers are expected to pay city and state transfer taxes on co-op sponsor sales. 

The city transfer tax is 1 percent of the purchase price for sales under $500,000, or 1.425 percent for purchases of $500,000 or more. Additionally,  a 0.4 percent state transfer tax is applied across the board. You may be able to negotiate with the seller to have them pay these taxes in a resale scenario, but this is less likely if it’s a sponsor unit.

You still need to do your due diligence

It’s important to find out as much as possible about the building, the previous tenant, and the sponsor. Your broker and attorney can help you with this. 

Ask how many apartments the sponsor owns in the building and how many are occupied by owners. Why’s that? Banks are more likely to view the building as a sound investment if most units are privately owned, rather than rentals. Therefore, the higher the percentage of privately owned apartments in the building, the easier it should be to secure financing.

Lavell said one of the biggest hurdles for buyers seeking a mortgage is when a sponsor owns a large number of units. For example, if a single investor owns more than 40 percent of units, or if multiple investors own more than 50 percent of units, the building’s owner-occupancy ratio would be too low for most lenders. 

That means that “the building would be deemed non-warrantable, which usually means that a fixed-rate loan may not be available or will be available at a higher rate,” he said.

Beware of legal issues with the previous tenant

Renters in NYC have many protections. As with any rental unit, you must ensure that the prior rental lease was terminated correctly and that the tenant has vacated the property or was properly evicted.  

What could happen? One scenario could be that a family member claims they were living with the previous tenant and were unfairly evicted, or that the apartment was vacated while they were on vacation.

Building rules still apply

Even though you don’t have to get board approval for the purchase of a sponsor apartment, you will still have to abide by the building’s rules and bylaws. 

Although the sponsor may not have “control” as defined by the offering plan, there are buildings where the sponsor has a significant vested interest and remains involved. Some buildings actually benefit from the expertise and relationships that the original sponsor or successor sponsor has established, bypassing a management company and getting answers from an individual instead.

Where to find them

Sponsor units are located throughout the city. The majority are in prewar buildings on the Upper East and Upper West Side of Manhattan, although a few new development co-op buildings with sponsor units can also be found in the Bronx and Queens.

Depending on your needs and the available inventory, you should plan to devote six to 12 months to finding a suitable sponsor-owned apartment. And, this being NYC, some buyers who want to avoid board approval are always on the lookout for them.

Let your broker know you are interested in sponsor apartments. You can also look for them on listing sites by entering the terms “sponsor unit” or “no board approval” in the search parameters. Some listing sites, including StreetEasy, offer a specific “sponsor unit” filter (under the “more” tab) that returned 246 co-op listings across the five boroughs in a recent search. 

—Previous versions of this article included writing and reporting by Tracy Kaler, Emily Myers, and Celia Young. It was updated for 2026 by Evelyn Battaglia.



Source link

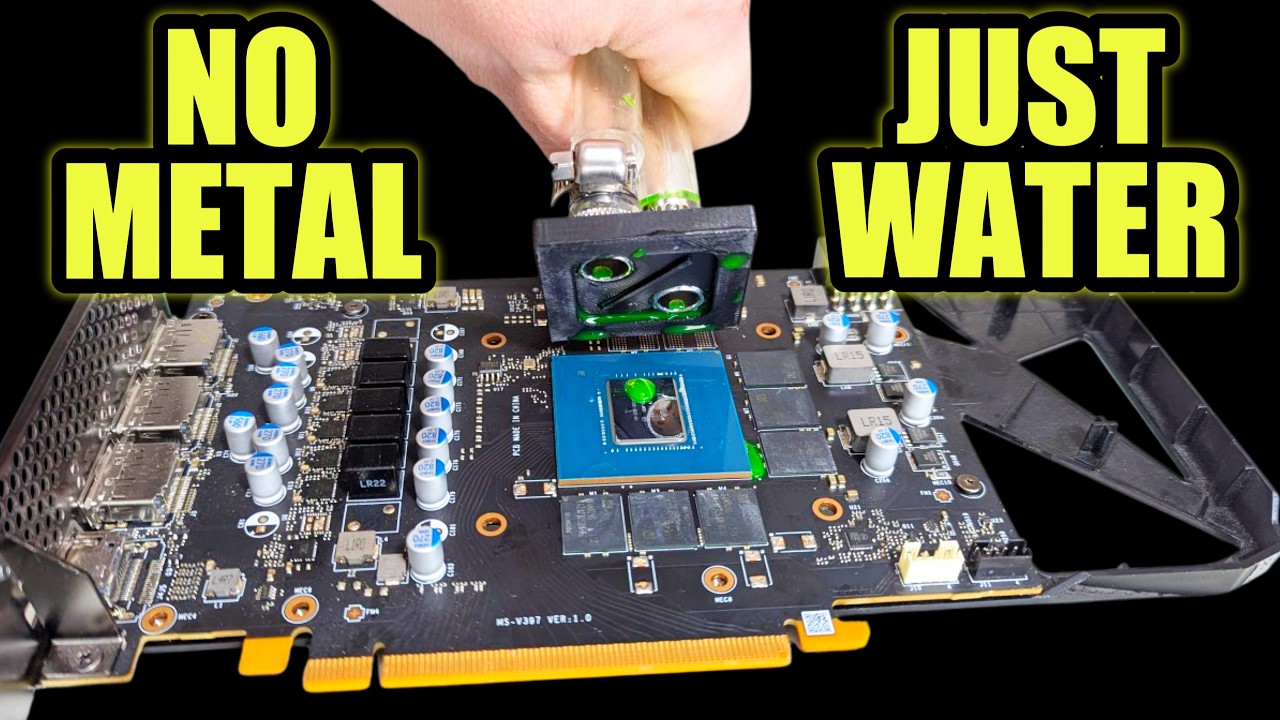
Modder pumps liquid directly over bare GPU silicon via 3D-printed block — drops RTX 2060 Super load temps to 28°C despite initial leaks


The fearless TrashBench has been testing direct die water cooling of graphics cards. The inevitable twist here is that they removed the metal waterblock from the equation. Despite initial leaky results and much concern of water damage to the expensive parts thrown into the mix, some of the end results are eyebrow-raising in a good way.

I Pumped Water Directly Onto a Running GPU – YouTube
I Pumped Water Directly Onto a Running GPU - YouTube


Watch On

“In my pursuit of the perfect water block, I realized, why do we need metal at all?” queried the antipodean host of the punk-rock GPU death lab. “Why can’t we just pump water directly over the bare silicon? Makes sense to me.”


Source link

Why I moved to NYC from India: To attend Columbia Business School and advance my career in technology


Sasank moved from Bangalore, India, to attend Columbia Business School. He navigated his apartment search online, landing in university housing in a very small place shared with two roommates. He loves the Morningside Heights area, with the lack of space and a faulty elevator his only pet peeves. Here’s his story as told to Kelly Kreth.

I was born and raised in Vizag, a coastal city in the southern part of India but prior to coming to New York City, I lived in Bangalore.

I had a 1,000-square-foot, two-bedroom apartment with my best friend from college. We had in-unit laundry and ample closet space. My portion of the rent was INR 30,000, about $320.

I liked that the residential complex had a feeling of community, plus amenities like tennis courts, a swimming pool, and gym, but I disliked the ongoing construction that made nearby streets dusty and filled with potholes.


[Editor’s note: Brick Underground’s series The Newcomers features first-person accounts about why a renter or buyer decided to take a chance on NYC.]


I spent weekends riding my bicycle to nearby breakfast places and lakes—shout out to Arogya Ahaara and Agara Lake. I also spent time at the movies at a Cubbon Park (it’s the Central Park of Bangalore). My roommate and I often had friends over for board games or parties.

I worked remotely for a technology startup as a product manager, so I only used my car for traveling.

Why he decided to move

In early 2025, I was admitted to the MBA program at Columbia Business School. I wanted to advance my career and explore a new city, one at the forefront of advances in technology. 

Because I couldn’t visit units in person, prior to my move I looked at floor plans online and checked locations using the street view feature on Google Maps.

I wanted to find the lowest possible rent because I took out a loan for my tuition and the currency exchange rate drastically cut into my savings.

In Bangalore, getting a rental involved a lot of negotiation. Typically you would offer a large security deposit to help convince an owner you would be a good tenant. 

In NYC, you have to pounce quickly to get an apartment.

I landed in NYC that August, moving into a Columbia University residential property. Columbia has its own process for renting to students—they give preference to those coming from farther locations and moving to NYC for the first time. I am thankful that my apartment hunt was fairly easy because much of it was handled by the university. It saved me a lot of hassle.

What he likes about his new place

I now rent a three-bedroom unit with two roommates—my bedroom is just about 100 square feet and the whole apartment is just 800 square feet. The building is on Riverside Drive and has an elevator, security, and in-building laundry. It’s close to the subway on 125th St. My portion of the rent is $1,350 and includes utilities.

The apartment is furnished, so I all brought were clothes and few cooking utensils and spices. That’s very Indian—spices are essential to our cuisine.

My biggest pet peeve is the elevator, which is probably older than my grandmom— it sometimes gets stuck and shuts down completely. My second pet peeve is that I grossly underestimated how small a NYC apartment can be. My friends from other places in the U.S. are surprised at how small it is. 

What he thinks of the neighborhood

I love that my place is right next to Riverside Park, which looks prettiest in fall, and Sakura Park, which looks prettiest in spring. I like that I can spend my evenings practicing my tennis game at the 116th Street tennis courts. I also love living near the Hudson River.

My favorite place to eat is El Porton, a Mexican restaurant, along with The ExPat and The Craftsman, which are Columbia Business School go-to bars. 

I like hitting Target, Trader Joe’s, and Whole Foods at 125th and Amsterdam in Harlem—those are monthly rituals. I rarely order in. I’m a regular at CTown supermarket and the deli nearby for groceries or a quick bagel. 

I no longer have a car. I take the bus and subway now. Everyone complaints about the train, but I like that I get home from any area even at 2 a.m. That’s incredible.

I will stay in this area at least for another year. Moving to NYC was a great idea and I would not change living in this neighborhood, but I may want to move to a different apartment.


Source link

Pre-modded 22GB RTX 2080 Ti cards surface on eBay for $500 as VRAM-hungry local AI fans chase down every spare FLOP — Hong Kong-based seller offers AI-friendly memory mod for a reasonable price


The AI boom means that no matrix math FLOPS are disposable, and that means older Nvidia GPUs with Tensor Cores are getting a new lease on life. Services are popping up that will outfit your RTX 2080 Ti with 22GB of VRAM, doubling its original memory pool and making it more useful for modern LLM and diffusion workloads. If you’re hard up for compute and you don’t have an RTX 2080 Ti to modify, however, eBay has just the thing. A Hong Kong-based seller will send you a pre-modded 22GB 2080 Ti in exchange for $499.

Go deeper with TH Premium: GPUs

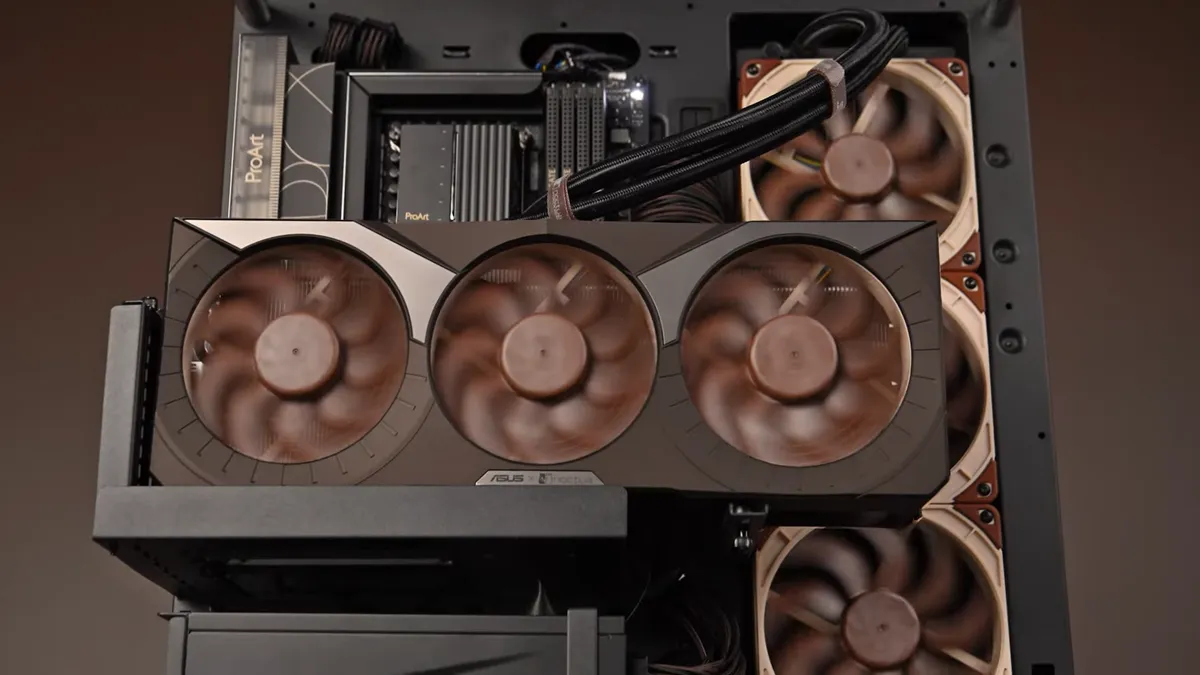
Asus RTX 5080 Noctua Edition

(Image credit: Noctua)

The listing only promises that you’ll receive a “Turbo,” i.e., blower-style, RTX 2080 Ti with the 22GB mod. Don’t get too picky about the particular brand of card you might receive, as the seller says: “The GPU brand could be Gigabyte, MSI, ASUS, Leadtek or others. It depends on what we have in hand.”


Source link

The 1881 Dr. Herman B. Sheffield House at 127 West 87th St: A narrow home with exuberant decoration


Have you ever passed by an interesting residential building in New York City and wanted to know more about its history? In this series, Brick Underground teams up with Tom Miller, creator of Daytonian in Manhattan, a blog about Manhattan buildings and other historic architecture. Each week, we run an excerpt from the Daytonian’s archives with a link to the full article.

In 1881, developer John W. Stevens acquired a 50-foot-wide parcel on West 87th Street between Ninth and Tenth avenues. (The avenues would be renamed Columbus and Amsterdam in 1890.) Rather than erect two commodious townhouses, Stevens directed his architect, William Howe, to squeeze three onto the plot. Each would be just over 16-feet-wide and would cost $8,000.

Like its identical siblings, 127 West 87th St. was faced in brownstone and designed in the neo-Grec style. Howe compensated for the home’s lack of width with exuberant decoration. The windows were flanked by paneled piers upon bracketed sills. Mimicking the doorway, the lintels were decorated with foliate designs. A complex pressed metal cornice of corbels, brackets and a paneled fascia completed the design.

The house was initially owned by Albert M. Crouter and his family. They sold it at auction on September 29, 1891. Norman and Sarah E. Macdonald placed the winning bid of $16,900.

Norman Macdonald was one of hundreds of New Yorkers who were frustrated with the city’s lack of street signs. Some residents or businessmen erected their own signs, and stone blocks on the second floor of some corner buildings were carved with the avenue and street names. In January 1901, Macdonald signed a petition that urging the city to address the issue.

Later that year, the Guggenheim Ordinance was enacted, instituting a system of standardized street signs. 

The Macdonalds sold 127 West 87th St. in April 1905 and the property changed hands several times in quick succession purchased in March 1909 by Dr. Herman B. Sheffield, a pediatrician and prolific author. His expertise was often sought by attorneys as an expert witness, such as the lunacy hearing of 22-year-old Walter Lathrop Hanson.  

Hanson’s mother, Mrs. Aimes Hanson, had multiple homes and was the niece of Leland Stanford, the founder of Leland Stanford University. Hanson’s father died in January 1912, and Walter was receiving payments from a $50,000 trust, administered by his mother. The New York Times reported that on November 5th, 1912, Walter married Henriette Keutti “without his mother’s consent.”  She cut him off from his “allowance” and sought to have him committed as a lunatic.

In the courtroom on March 5th, 1913, Dr. Herman B. Sheffield “pronounced him mentally competent,” reported The New York Times. The article added, “On the side of young Hanson sat his young bride, who returned stare for stare of her mother-in-law.”

No. 127 West 87th Street is remarkably intact after more than 140 years. Even the interior shutters survive on the upper floors.  

For more on the property and the people that lived here, check out the full article.


Source link

PC cooling outfit Arctic reverses tariff-era price hikes after US government refund — lowers prices across lineup, including coolers and case fans


Following a tariff refund from the United States government, popular PC cooling hardware manufacturer Arctic has announced a price rollback for its products sold in the U.S. The refund was made possible after a February 2026 Supreme Court ruling found that the 1977 International Emergency Economic Powers Act (IEEPA) does not grant the President unilateral authority to impose import duties without prior approval from Congress.

The reduced price will be applicable across Arctic’s direct-to-consumer sales channels in the U.S. and is claimed to be already in effect on Amazon and eBay. In its latest blog post, Arctic said, “When U.S. trade tariffs significantly increased, Arctic proactively absorbed as much of the tariffs as possible to protect our customers. While most of the product lineup remained unaffected, price adjustments became necessary for a limited number of products in the U.S. market. At the time, Arctic committed to reversing those increases if circumstances allowed. “


Source link