An app engineer has showcased his homemade breadboard 486 DX2 PC running Doom. The intricate explosion-of-wires system build appears to have taken just 16 days, with the first appearance of the legendary Intel CPU on @nagakurage’s timeline on October 24, and a video demo of some fragging in Doom published on November 9. Moreover, the Tokyo-based app engineer behind the project also developed and made a bezelicious ‘CRT monitor’ to go with the homemade early-90s-era gaming beast.
はじめてDOOMで遊びます、自作のi486 PCで https://t.co/feosWgd6deNovember 9, 2026
Latest Videos FromTom’s Hardware

If selling your house is on your calendar for 2027, you may be thinking you’ve got plenty of time. Maybe you’re aiming for January. Maybe you’re waiting for spring. Either way, next year probably feels far enough away that getting ready can wait, too.
But waiting until 2027 to sell doesn’t mean waiting until 2027 to get started.
Today’s buyers have more homes to choose from than they’ve had in years. So, if you want your house to stand out when it’s time to list, a little preparation now can make a big difference later.
As a general rule of thumb, Zillow recommends giving yourself about 2-3 months to get your house ready to list. And that makes sense when you consider that the vast majority of sellers (78%) did at least one home improvement project before their house hit the market.
That gives you plenty of time to decide what to fix, find contractors, get on their schedules, actually make the updates, and get everything ready for photos and showings.
But don’t worry – that doesn’t mean every seller had some big to-do. The most common? Interior painting (see graph below):
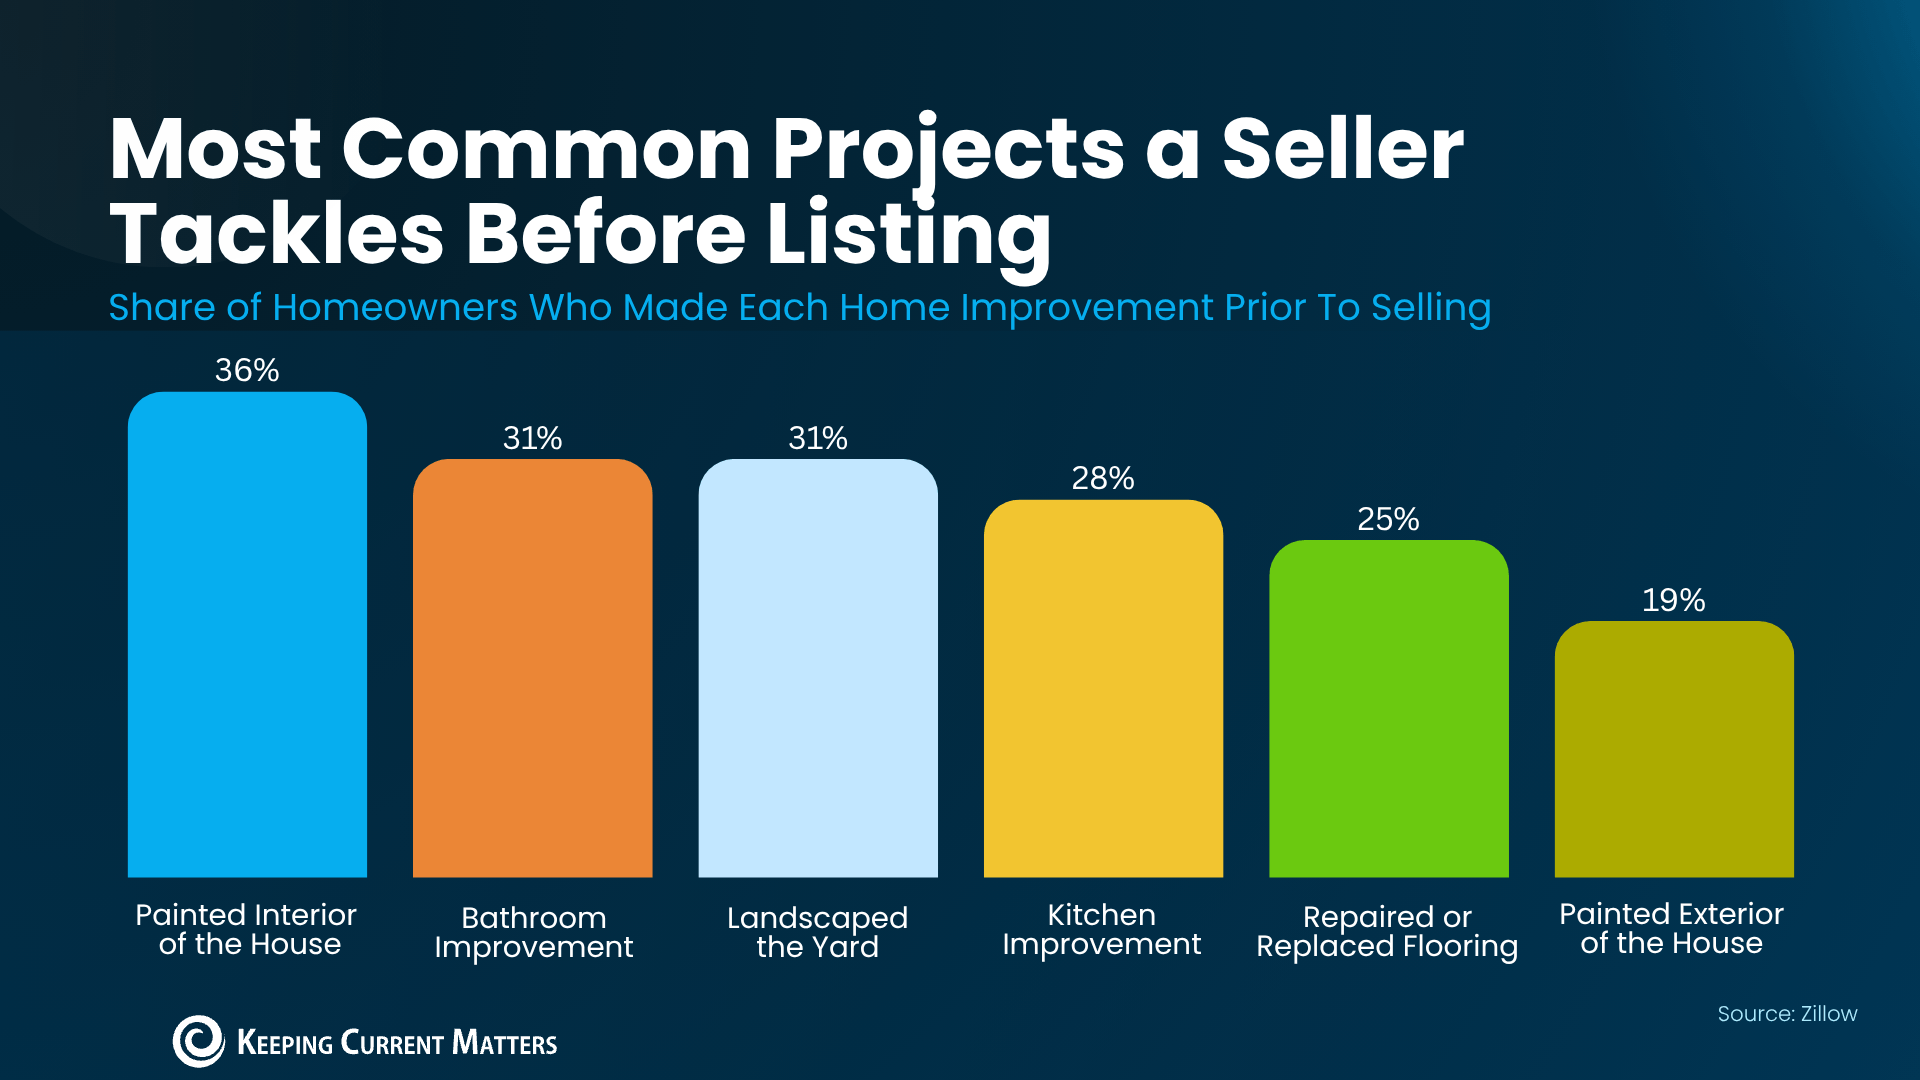
That certainly doesn’t mean you need to tackle everything on this list. You may not need to do any of it. But odds are there’s at least one project you’ll want to do. And starting that conversation now gives you a leg up before next year.
Here’s how to tackle it.
While you might have a long list of things you think need updating, that doesn’t mean they’re all worth the time, effort, or money.
An agent will help you figure out which projects deserve a spot on your to-do list based on what buyers want most and what other sellers are doing. That way, you’re not investing in updates that won’t make much of a difference when you sell.
One thing your agent may recommend today is that you go ahead and get a pre-listing inspection. It’s basically your cheatsheet to what a buyer’s inspection may turn up later on.
And now that buyers have more options, they’re pickier – and you don’t want anything popping up in an inspection that could put them off.
For example, you know that HVAC system you’ve been hoping will make it through one more season? Now’s a good time to give it some attention – along with anything else you know needs a little TLC. That way a repair you could’ve handled months ago won’t become a surprise in the middle of your sale.
According to Angi, a pre-listing inspection typically costs $300-600 and that can be money well spent. As the National Association of Realtors (NAR) explains:
“An inspector will be able to give you a good indication of the trouble areas that will stand out to potential buyers, and you’ll be able to make repairs before open houses begin.”
The advantage isn’t just knowing what may come up, but being able to get ahead of it and space out the projects on your own schedule. So you don’t feel stressed during go-time.
But remember, not everything needs to happen right away. Some things are better saved for when you’re closer to listing.
Think deep cleaning, staging, touching up paint, and tidying up the landscaping. Those are the finishing touches that’ll help your house look its best when buyers walk through the door.
But there’s one thing you can start anytime: decluttering. Go ahead and tackle the closets, garage, or storage room you’ve been avoiding. Future you will appreciate having a few less boxes to pack.
The idea isn’t to get everything done today. It’s to spread the work out so you’re not scrambling when listing day arrives. As Redfin puts it:
“Smart preparation leads to a smoother sale, stronger offers, and fewer surprises during closing. . . Homes that are clean, well-staged, priced right, and professionally photographed tend to sell quickly.”
You don’t need to spend the rest of the year renovating your house or packing up your life. But you can start making a plan.
The earlier you figure out what needs to be done, the more time you’ll have to do it right. And that means less rushing, fewer last-minute surprises, and a better chance to make a great first impression when you’re ready to sell.
Thinking about selling in 2027? Get a local agent’s opinion on what your house needs, what it doesn’t, and how to get everything ready on your timeline.

Manhattan median rent continues to soar while renters compete for fewer apartments
Median rent for new leases increased to $4,965 last month, the second highest on record, according to The Real Deal Rental Report by appraiser Jonathan Miller. He noted that inventory has been falling year over year each month in Manhattan since July 2025, when median rent was $5,000.
Listings in Manhattan were down 27.8 percent from October 2025, which contributed to a 9.8 percent drop in leases signed last month compared to a year ago, a pattern that has been ongoing since March, Miller said in his report.
Rents for Manhattan apartments of all sizes, from studios through three bedrooms, reached new highs in October, with the biggest leap seen in apartments with three bedrooms or more, which are the scarcest. Those large units saw a 25 percent increase in median rent to $9,997.
It is a similar story in the Brooklyn rental market, where median rent has not seen an annual decline in more than two years, Miller wrote. It was up by 4.6 percent annually to $4,028 in October.
Listings fell dramatically: They were down 68 percent compared to a year ago and 33.5 percent compared to last month. Despite the decline in Brooklyn rental inventory, new lease signings rose annually for the first time since June 2025, increasing by 7 percent.
The share of leases with renters paying more than what the landlord was asking shrank by half—dropping to 15.6 percent from 29.6 percent a year ago.
For the northwest section of Queens covered by the report (Long Island City, Astoria, Sunnyside, and Woodside) median rent has been rising on annual basis for more than two years. It reached $3,782 last month, an increase of 5.1 percent compared to the previous year.
Listings declined 24.1 percent while new lease signings were 16.4 percent on an annual basis.
Vacant units were snapped up much faster in October compared to a year ago. Days on market was 18 versus 38 in October 2025.
Corcoran also released Manhattan and Brooklyn rental market reports, which noted that this October marked the lowest Manhattan residential vacancy rate recorded in any month since March 2020.
Gary Malin, chief operating officer at Corcoran, said that “with vacancy falling to just 1.31 percent … competition remains intense whenever quality inventory becomes available. Until supply meaningfully improves, renters should expect pricing power to remain firmly in landlords’ hands.”
Brooklyn also continues to see strong upward pressure on rents because of lower supply, Malin said. “Would-be tenants are increasingly competing for a shrinking pool of apartments, helping push prices to new highs. The reality is that demand hasn’t gone away, but a lot of the available inventory has.”
Editor’s note: This article has been updated with Corcoran’s rental market coverage.
Housing lottery applications are open for 217 rent-stabilized apartments at a new development in East Williamsburg. Households that earn $29,418 to $168,320 are eligible to apply, depending on the number of people you live with. Rents start at $751 for a one bedroom and $846 for a studio.
The building next to the corner of Cooper Park will have a 24/7 security guard, gym, bike storage, a children’s playroom, shared laundry, and in-unit dishwashers and microwaves. Heat, cooling and hot water are all included in the rent.
Magnusson Architecture and Planning designed Kingsland Commons, located at 89 Maspeth Ave. at the site of the former Greenpoint Hospital. In addition to affordable housing, developers Maspeth Manager and St. Nicks Alliance will include a homeless shelter, senior living, health clinic, and retail space within the complex. The L and G trains are accessible at the nearby Graham Avenue station.
The apartments are set aside for New Yorkers earning from 30 to 80 percent of the area median income (AMI)—a metric that depends on how many people you live with. Currently the AMI for New York City is $129,600 for a two-person household. The apartments available include studios as well as one-, two-, and three-bedroom apartments.
There are 27 two-bedroom apartments available for households earning from $100,766 to $146,560, with an asset limit of $135,680. The rent for these apartments is $2,798.
The developers have set aside 20 percent of the rent-stabilized apartments for applicants who already live in the area. Another 10 percent of the apartments will be preferentially given to NYC employees or military veterans. A small percentage of the apartments are also set aside for residents with mobility, vision, and hearing needs.
Applications must be submitted online or postmarked no later than Nov. 25th.
If you’re interested and think you might qualify for one of these apartments, you can create a profile and apply online via NYC Housing Connect. For details on this particular lottery, click here. Don’t apply more than once, or you could be disqualified.
Winning a rent-stabilized apartment can be life changing: Rent increases are capped and lease renewals are automatic, providing long-term stability for NYC renters. Need more information on how the housing lottery works? Check out “6 steps for applying to NYC’s affordable housing lottery.”
For some advice from successful applicants read “How to land a rental apartment through NYC’s affordable housing lottery.” And if you or someone you know is having trouble with the application process, consider reaching out to a housing ambassador in the community.
Note: Brick Underground is in no way affiliated with New York City’s Department of Housing Preservation and Development or the Housing Development Corporation. If you are interested in applying to these or other affordable housing developments, please go to NYC Housing Connect for information and instructions.
Have you successfully won an apartment through the affordable housing lottery? If you have first-person advice to share about the process, we’d love to hear from you. Please send us an email. We respect all requests for anonymity.
Figuring out whether to stay or move to the suburbs has long been a point of debate for New Yorkers, especially families that have outgrown their apartments. Discussions typically focus on housing costs, commute times, and lifestyle preferences. But in recent years, the conversation has shifted.
“It’s still an incredibly personal decision and absolutely not one-size-fits-all,” said Jennifer Ross, a Westchester-based broker at Compass who has helped dozens of New Yorkers relocate over the past decade. “But the reasons people are moving today are different. It’s less about escape and more about designing the lifestyle they want for the next 10 years—space, community, schools, and balance.”
Below is a look at the real costs and trade-offs of moving to the NYC suburbs.
[Editor’s note: An earlier version of this post was published in November 2025. We are presenting it with updated information for November 2026.]
You’ll still get more bang for your buck in the suburbs, but pricing there has climbed dramatically since the early 2020s.
“The $800,000 to $900,000 range is no longer the sweet spot it once was in lower Westchester,” Ross said. “That used to get you a move-in-ready home; now it’s often the entry point for something smaller or needing updates.”
She noted that while the market has been challenging for buyers since Covid, last season was even more intensely competitive. Inventory remains low, and during the spring selling season, bidding wars were the norm.
“The average price in Westchester county-wide for a single-family home is approximately $1.4 million, but a move-in ready home in Scarsdale, Larchmont, Bronxville, or Rye will easily start at well over the $2 million mark,” Ross said.
By comparison, the median sales price for Manhattan co-ops and condos hit $1.25 million, and in Brooklyn, it reached $1.15 million, in the third quarter of 2026.
“Families tell me: ‘If we’re going to spend this much money, we want room to actually live.’ And suburban homes deliver on that more consistently,” Ross said.
On livable space, Shawn Elliott, a broker at NestSeekers International, said the suburbs win every time. “You can get double the square footage in the suburbs for half the price of the city,” he noted, putting the savings between 25 and 50 percent if you buy in the suburbs versus the city.
“On Long Island, you could easily find something that goes for under $600 per square foot,” he said, adding that the suburban houses he’s selling are typically on multiple acres and have tennis courts, pools, wine cellars, and garages. (The average price per square foot in Manhattan was $1,526 in the third quarter, as per the Elliman Report.)
While more square footage is the number one draw, it comes with increased upkeep.
What’s more, “You’re trading the convenience of a super for the freedom of a backyard,” Ross said. “And that comes with responsibilities.”
She always advises buyers to build a maintenance cushion into their yearly budget, estimating that most clients budget $8,000 to $15,000 a year for lawn care, HVAC servicing, snow removal, gutter cleaning, and the myriad repairs that come with homeownership.
In a large, suburban, single-family house, utilities will also cost more, as will all the additional furniture, home decor, lighting, and fixtures you’ll need. That can add up to tens of thousands of dollars.
Transportation remains one of the most significant adjustments for city dwellers.
According to AAA’s 2026 analysis, the total cost of owning and operating a new vehicle is currently $12,863, or $1,072 per month. So if you plan on going from zero cars to two, the numbers add up fast.
You’ll need to budget for auto insurance as well—averaging $335 per month for full coverage. On a bright note, the premiums are generally cheaper in the suburbs. For example, MarketWatch shows $404 as the average cost of full-service coverage in Larchmont, compared to $650 in Brooklyn.
Of course, many New Yorkers already own a car and shell out $500 to $600 per month for parking garages. “When they move, that garage expense simply shifts into other budget categories. You’re not saving the money, but you are reallocating it,” Ross said.
She also noted that not every suburb requires two cars. “Walkability is huge. Larchmont, Pelham, Hastings-on-Hudson, Dobbs Ferry, Pleasantville, and Tarrytown continue to be great options for people who want a village lifestyle where you can walk to town, the train, coffee shops, parks, and schools.”
Walkable neighborhoods in New Jersey include Montclair, Maplewood, Summit, and Chatham, while Greenwich and Westport are good options in Connecticut.
Are you required to work in person? If so, consider the added travel cost and time when contemplating a move.
An 80-mile round trip from Westchester to Manhattan will cost about $1,300 per month in gas if you drive alone. Monthly Metro-North tickets can run $250-$350 for Westchester commuters and $350-$500 for Connecticut commuters. Long Island Rail Road commuters pay $300 to $500 for monthly fares.
Property taxes are generally higher in the suburbs, though the difference varies significantly by location. In NYC, the effective property tax rate for homeowners is below 1 percent, compared with statewide averages of 1.30 percent in New York State, 1.88 percent in New Jersey, and 1.54 percent in Connecticut. Effective rates are calculated by comparing annual property taxes with a home’s estimated market value.
On the flip side, moving outside NYC can eliminate the city’s personal income taxes, provided you establish residency elsewhere. Depending on your income and tax bracket, the savings can be substantial—more than $30,000 if you earn $800,000 a year.
Homeowners insurance premiums vary considerably by location, property value, and coverage. According to Insurance.com, 2026 estimates put the average annual premium at approximately $1,900 in Westchester County and $3,180 in Suffolk County, compared with $2,585 in Manhattan and $2,484 in Brooklyn. Coastal exposure, severe-weather risks, and rebuilding costs can all influence premiums.
The ultimate takeaway is to factor this cost into your initial buying calculation, following the same rule of thumb for both the city and the suburbs: The sum of your mortgage payment, property taxes, and insurance premiums should not exceed 30 percent of your annual income.
Education often becomes the deciding factor—and one of the biggest financial wins.
According to Ross, public school quality is still the top driver in Westchester—especially for those considering private school in Manhattan, where tuition now averages $50,000 to over $75,000 per child per year. That adds up quickly.
“I’ve had clients accept a $60,000 to $80,000 property tax bill with zero hesitation because they’re no longer paying $150,000 in private school tuition for their three kids,” Ross said. “It’s simple math—and it’s compelling.”
Suburban extracurriculars are not only less expensive but also more accessible, with much less competition for sports, music, clubs, and more. “Parents love that. Their kids get to explore without the stress of waitlists and lotteries,” she added.
Ultimately, the decision is deeply personal—but much clearer when framed in terms of lifestyle, not just cost. “It’s about building the life you want for the next decade,” Ross said. “For many families, the suburbs feel like the right place to do that.”
—Earlier versions of this article contained reporting and writing by Emily Myers. It was updated for November 2025 by Evelyn Battaglia.
In recent months, high-profile headlines about AI models letting loose from their safeguards dominated headlines. Now, the Frontier Model Forum (FMF) has released a new Jailbreak Rating Framework that aims to track how easy it might be for a given AI model to get around safeguards. The framework also estimates the scale of the collateral damage, should an AI model wreak cyber-havoc across the internet.
The project started in 2023 with the support of four founding companies: Anthropic, Google, Microsoft, and OpenAI. The published Jailbreak Rating Framework is a rough analog to the well-known CVSS security rating system, but specifically targeted at classifying the type and severity of LLM jailbreaks across various axes and multiple frontier LLM providers.
Latest Videos FromTom’s Hardware
When it comes to housing, two of the biggest questions on everyone’s mind right now are:
What’s next for mortgage rates?
Where will home prices go from here?
And if you’re weighing whether to move in the next few months or wait until 2027, here’s what you should know.
When experts look ahead to 2027, they see a steady housing market. No wild swings. No big surprises. Just a calmer, more balanced market.
And steady makes planning a whole lot easier. Let’s break it down.
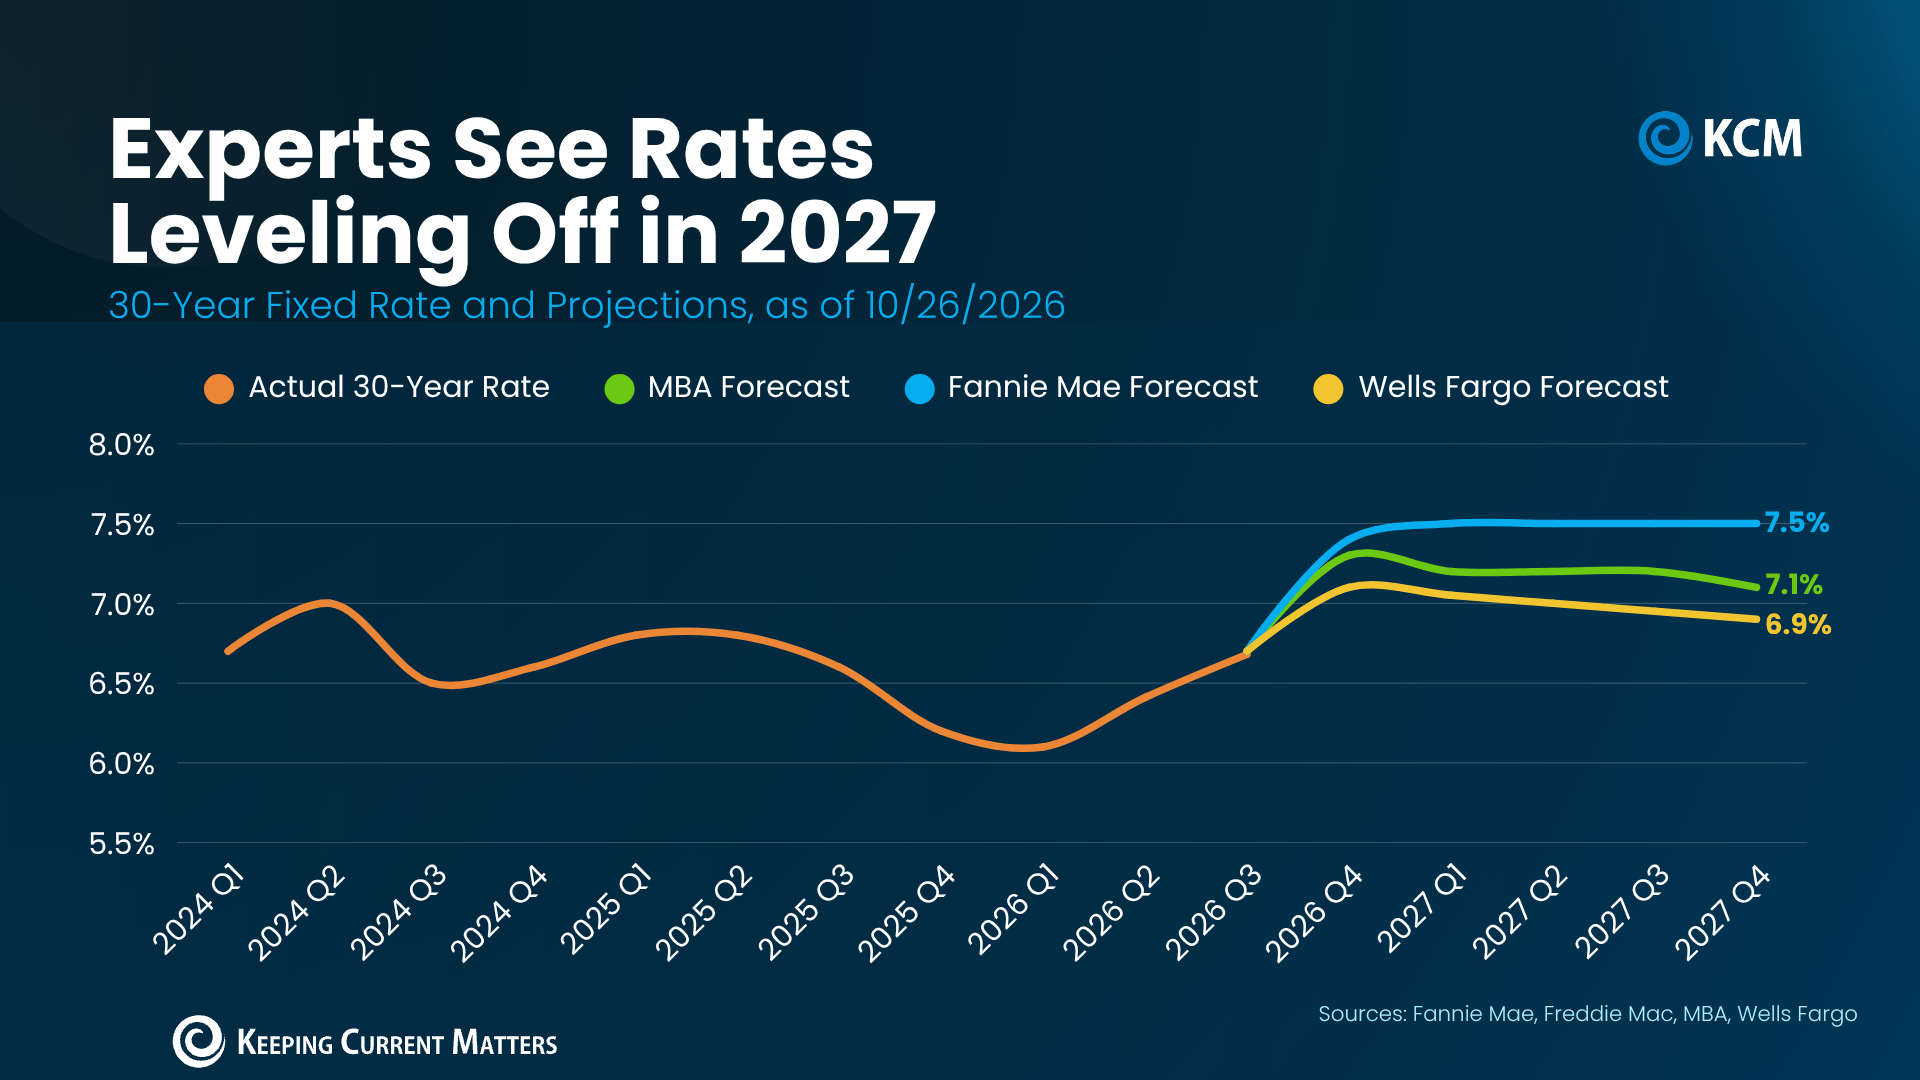
Lots of people are holding out for lower rates. But the latest forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo show rates holding fairly flat through 2027 (see graph below):
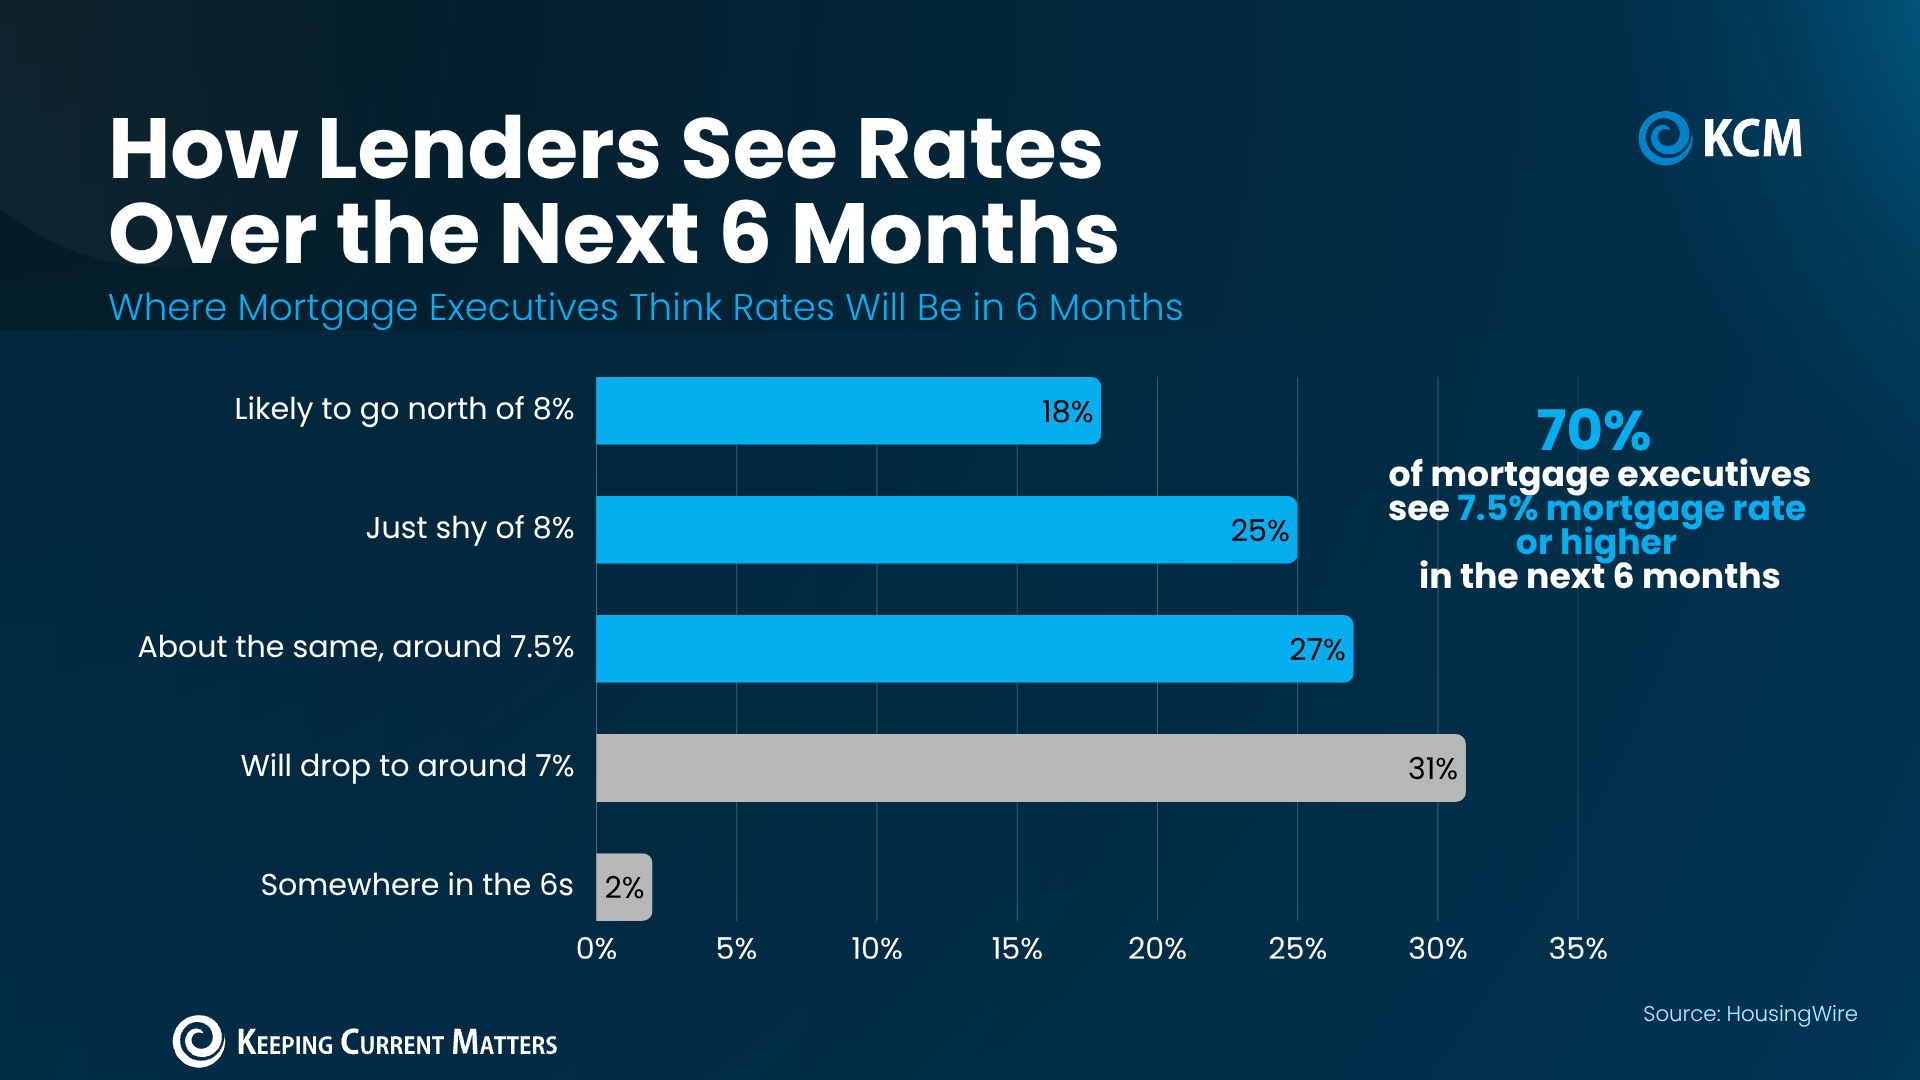
Lenders see it the same way. In a recent survey from HousingWire, 70% of mortgage executives said they expect rates to be around 7.5% or higher six months from now (see graph below):
And if you’re wondering why, the answer is fairly simple. Chen Zhao, Head of Economics Research at Redfin, says:
“Until the underlying economic fundamentals—everything from oil prices to AI–that are keeping rates high change, mortgage rates are unlikely to fall significantly.”
So what does that mean for you? Instead of trying to guess where rates go next, focus on what you can control. Even if rates don’t budge, there are still ways to get the best rate possible. When you talk with your lender, ask about:
Your credit score. Even a small bump in your score could help lower your rate.
Different loan types. Some programs offer lower rates or smaller down payments than you might expect.
Buying down your rate. Paying a little more upfront (called “points”) can lower your rate and your monthly payment.
That way, you’ll know exactly where you stand and what a comfortable monthly payment looks like for you.
But what about prices? Here’s where steady really works in your favor.
Experts don’t see a home price drop coming. On average, forecasts from Fannie Mae, MBA, and Wells Fargo show prices rising about 1% to 1.5% a year through 2027 (see graph below):
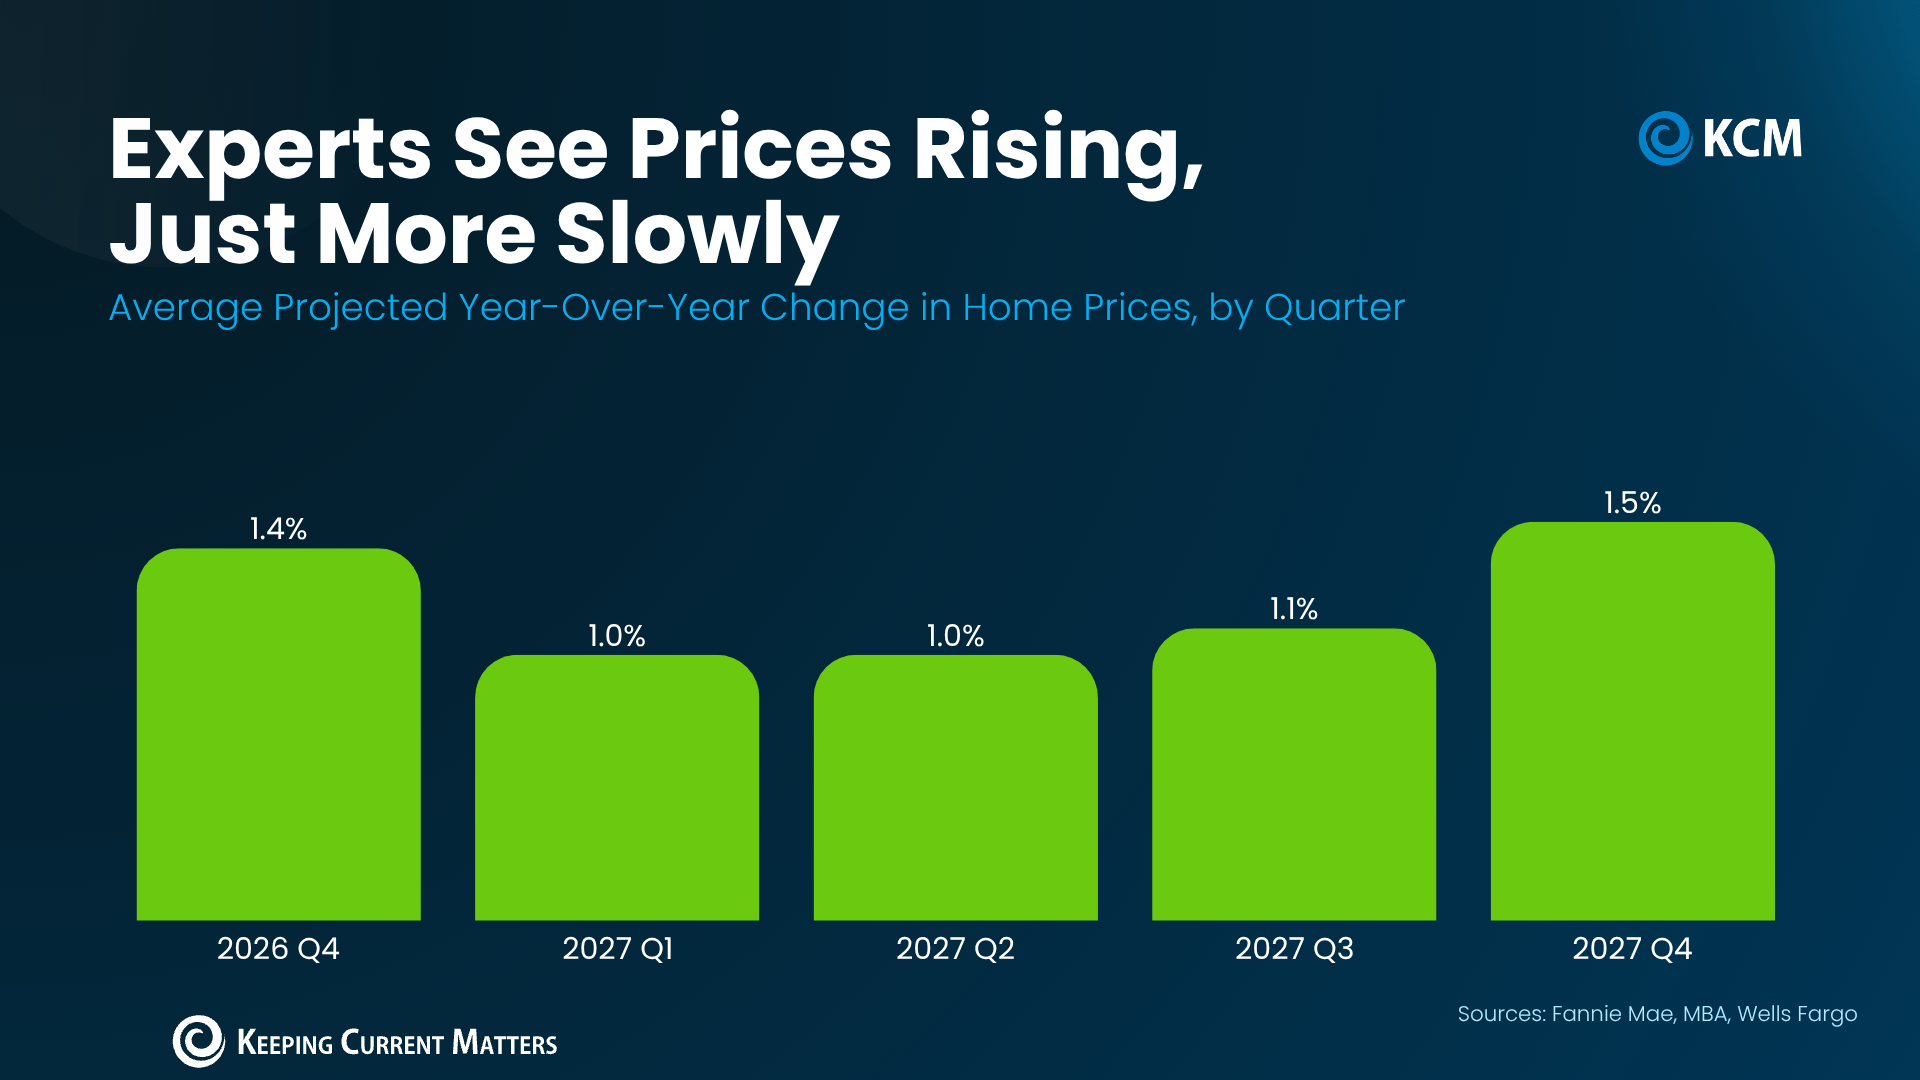
In plain terms, in most places prices are still going up, just not as fast. For sellers, that means your home should hold onto its value. For buyers, slower growth gives you a little more breathing room. Just don’t count on prices getting cheaper while you wait.
But keep in mind, these are national forecasts. Prices can look very different from one area to the next, so what matters most is what’s happening where you live.
When the market is steady, you don’t have to try to time it perfectly. There’s no big swing to wait out.
That puts the focus back on you. Maybe you need more space for a growing family. Maybe you’re ready for less upkeep. A steady market makes it easier to plan for either one.
If you’re asking yourself should you move now or wait? You should know experts see a steady market through 2027, with rates holding near today’s levels and prices rising slowly.
So, rather than waiting for a big shift that may not come, connect with a local real estate agent and run the numbers on what a move looks like at today’s rates and prices, so you can decide based on your goals instead of the headlines.
In today’s market, a growing number of sellers are opting to do something called a price cut – especially when their house has been on the market for a while without any bites.
According to HousingWire Data as many as 4 in 10 (43%) sellers are going this route – that’s the highest it’s been in 4 years. But what if there’s another (potentially better option) for your bottom line? And it’s just as appealing, if not more so, to today’s buyers?
Enter the rate buydown.
First, let’s set the stage on why some compromise may be necessary in today’s market.
In September, Redfin says there were 63% more sellers than buyers in the market. And with so many sellers active and relatively few buyers by comparison, those purchasers are realizing they have more power. And as mortgage rates continue to put a squeeze on their budgets, they’re leaning in and using it.
One of the most common negotiation points? The price.
That’s because they want to feel like they’re getting a deal and they want to see their monthly payment drop. And since buyers can’t control rates, the price feels like the most obvious lever to pull.
But the savviest sellers realize being flexible doesn’t always mean a lower price, paying for a buyer’s rate buydown might work better.
A buydown is money paid at closing to lower the buyer’s mortgage rate. When you pay it as the seller, you are paying some of the buyer’s interest ahead of time, so the buyer gets a lower rate and monthly payment. And that’s especially appealing to today’s buyers.
Temporary buydowns lower the rate for the first few years, then it goes back to the full rate. The more years a buydown covers, the more it costs. These work well for buyers who expect to refinance within a certain amount of time.
A permanent buydown lowers the rate for the whole loan. These are paid for with “discount points.” One point costs 1% of the loan. According to FICO, each point generally lowers the rate by about a quarter of a percent. This type of buydown works well for buyers who plan to stay in the home for a long time.
And here’s why these can be a win-win for both buyers and sellers. Rate buydowns help sellers stand out in a crowded market and they can have a bigger impact on your buyer than a price cut would.
Here’s an example to show you what that could look like.
Let’s say you’re willing to make a $10,000 concession to help get the deal done. Take a look at these three ways to spend that money and the impact they could have on a buyer’s $420,000, 30-year fixed loan at 7%:
It’s the same $10,000 from the seller. But a 2-1 buydown saves the buyer about eight times more each month in the first year.
And since most buyers shop by monthly payment, that’s what grabs their attention.
That’s what makes a rate buydown worth considering. Instead of reducing your asking price, you may be able to use that same money to have a bigger impact on your buyer’s monthly payments. And depending on what matters most to that buyer, the immediate savings could be more appealing than a price reduction.
The key is working with your agent and the buyer’s lender to compare the options and see which one makes the most sense.
Loan programs cap how much a seller can pay toward a buyer’s costs.
Money toward buydowns doesn’t limit what else a buyer may ask a seller to pay for. Buyers may still ask for repairs or other concessions.
Putting the buydown offer in your listing lets agents and buyers know it’s an option.
Your agent can run scenarios on buydowns and other costs of selling in advance so you’re prepared when an offer comes in.
As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:
“Home sellers need to be realistic about local market conditions, which could require price discounts and other incentives to attract buyers.”
And sellers who offer solutions like buydowns can make meaningful impact where home buyers need it most: in their wallets.
When you’re looking for ways to make your house more appealing to buyers, a price reduction isn’t your only option. A mortgage rate buydown could help a buyer save more each month, especially in the early years of their loan.
Talk to your agent or a trusted lender which incentives could make the biggest difference for buyers in our market, while still protecting your bottom line.